
2i Limited
Miggins
GAIL Network Ltd
Luminapro Limited
ControlOne UK
Fenway Data Group
Aveni extends market leading wealth and compliance platform into consumer agentic AI for financial services
£12m investment accelerates launch of Agent Assure, closing the AI agent safety gap
Aveni, the UK’s leading AI fintech specialist in wealth management, financial advice and banking, today announced a £12 million funding round led by PXN Ventures, the UK’s fastest-growing venture and investments firm outside London and the South East, and supported by existing investors Puma Growth Partners, Lloyds Banking Group, Nationwide and Scottish Enterprise. The investment will accelerate development of Aveni’s Unified Assurance Platform (UAP) and the launch of its new Agent Assure and Agent Approve solutions, purpose-built to assess the conduct risk of AI agents that interact with consumers in financial services.
Aveni is the established market leader in AI adoption across UK wealth and banking, with over seven years of live deployments and product development. Its products Aveni Assist, an AI productivity solution for advisers and operations teams, and Aveni Detect, its AI compliance monitoring tool, are deployed across the UK’s leading banks, wealth managers and financial advisers. Underpinning both is FinLLM, Aveni’s proprietary suite of specialist small language models built for and utilising UK financial services data.
Agentic AI adoption in financial services is accelerating, but deployment at scale is being held back by a critical gap in assurance. With just 2% of firms reporting adequate AI guardrails, the absence of robust, regulated oversight for AI agents that interact directly with consumers is the number one challenge for the industry. Regulators are clear that the mode of engagement, human or machine, is secondary to consumer outcomes, which must be assessed consistently across all interactions.
Agent Assure directly addresses this gap. A natural extension of the Aveni Detect proposition, it enables firms to monitor and manage the conduct risk of AI agents alongside human interactions, in a single unified view. Together with Aveni Assist, Aveni Detect and the new Agent Approve solution, this Assure forms the Unified Assurance Platform: the financial service industry’s first comprehensive framework for assuring both human and agent interactions with consumers at scale.
Aveni is a participant in the FCA’s Supercharged Sandbox programme and has established the Agent Assurance Expert Council to support development of responsible AI governance frameworks. The company is working directly with regulators and industry bodies to shape the emerging standards for AI in financial services.
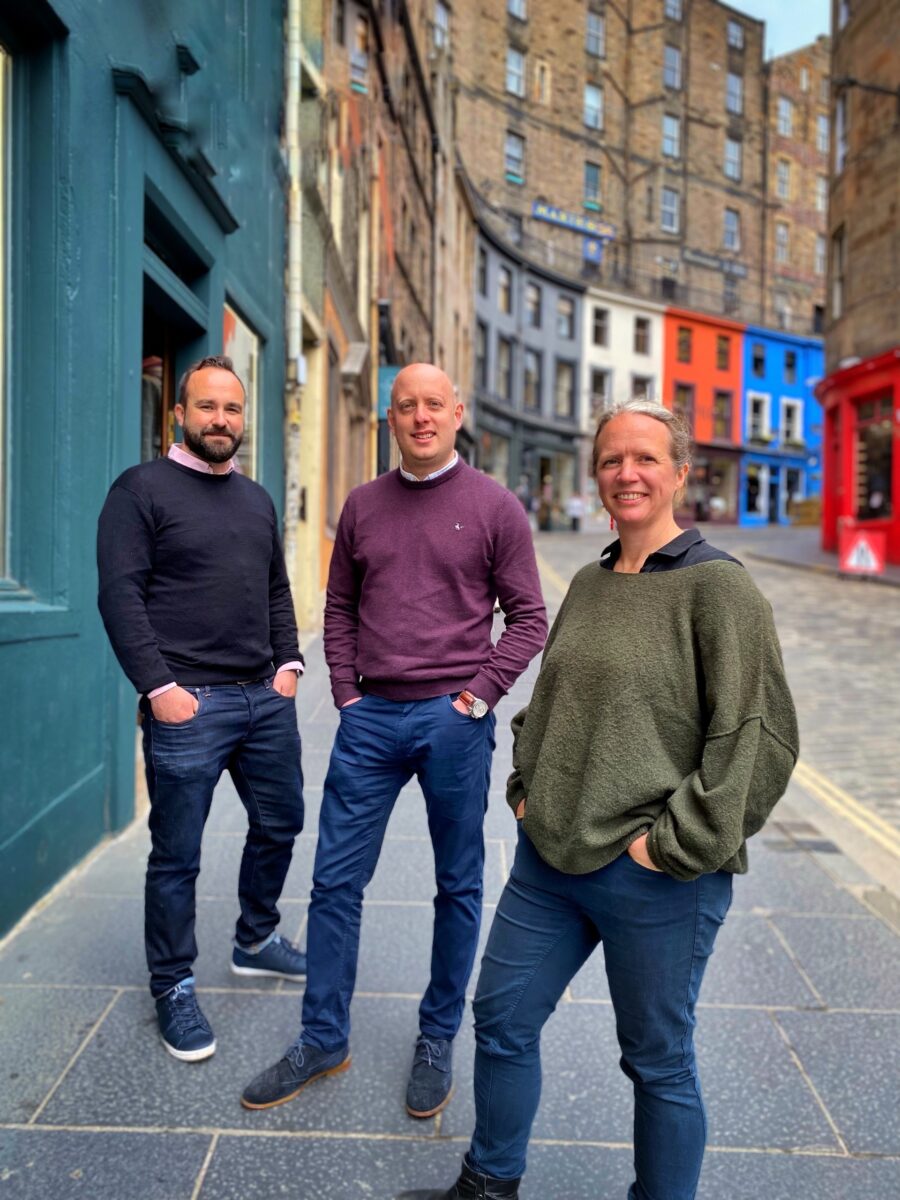
Joseph Twigg, CEO of Aveni, said: “The continued confidence shown by our existing investors is a powerful endorsement of the direction we’re taking. We have spent seven years building the models, the experience and the regulatory relationships that make us uniquely qualified to solve the hardest problem in AI adoption right now: how do you assure the conduct of an AI agent interacting with a real consumer? Agent Assure is our answer — and this investment accelerates our ability to deliver our full platform at scale.”
Alastair Moore at PXN Ventures, said: “Aveni is fast becoming financial advisers’ go-to tool for helping them leverage AI in a safe and appropriate way. The team now has seven years of live deployments and proprietary models built within the UK financial services sector. Their infrastructure is answering one of the biggest questions in AI adoption: how to manage real client interactions and build trust, so advisers can focus on what they do best. We’re proud to support Aveni through multiple PXN funds, including the Praetura Growth VCT, as they continue their growth journey and demonstrate the world-class fintech capabilities of the North of the UK.”
Ben Leslie, Investment Director, Puma Growth Partners, commented: “The impact Aveni is making in deploying AI into UK financial services is already significant, and we continue to see a substantial growth opportunity ahead. With agentic AI adoption accelerating and regulators rightly focused on consistent consumer outcomes, robust assurance for AI agents is rapidly becoming a core requirement for the sector. As a standout example of Scotland’s growing strength as a technology hub, Aveni is well placed to lead this next phase. We are delighted to invest again from our Scotland office to support Joseph, Jamie, Professor Lexi Birch and the wider team as they scale the Unified Assurance Platform and launch Agent Assure.”
Kirsty Rutter, Fintech Investment Director at Lloyds Banking Group, said: “Agentic AI represents a significant opportunity for financial services to enhance customer experience through more personalised interactions. Aveni is helping firms adopt this technology in a safe and responsible way. We’re pleased to continue supporting Aveni’s ongoing development through investment and partnership.”
The continued backing of existing investors reflects confidence in Aveni’s roadmap and market position. PXN Ventures led the round alongside Puma Growth Partners, Lloyds Banking Group, Nationwide and Scottish Enterprise.
Scotland invests £3.18m to fast‑track fintech growth, jobs and collaborative innovation
Funding backs a Scottish programme turning strengths into real‑world impact
The Financial Regulation Innovation Lab (FRIL), the UK’s centre of excellence for innovation in technology to efficiently meet financial regulation requirements, has secured £3.18 million from Scottish Enterprise to deliver three years of the award-winning programme. The funding will deepen collaboration amongst academia, industry and regulators, and further accelerate the adoption of responsible technology-driven innovation in financial services, supporting the sector’s competitiveness and that of the economy.
Led by FinTech Scotland in partnership with the University of Strathclyde, FRIL will accelerate the adoption of new solutions enabling fairer financial futures and supporting technology innovators to scale their businesses.
The types of industry regulatory challenges that FRIL will address include:
- ensuring AI is adopted by providers in a way that is responsible and explainable to ensure fair financial outcomes for businesses and consumers;
- finding solutions that strengthen the effectiveness, integrity and efficiency of financial crime controls.
Agile prioritisation during the programme will address industry needs and emerging regulations around the use of AI, open data and digital assets. By uniting industry, academia, technology innovators, government and regulators, FRIL will turn shared insight into products, partnerships, investment and real‑world adoption.
To date, FRIL has successfully supported 120 fintech SMEs to accelerate solutions, enabled £28 million in committed private investment and delivered a projected 6:1 economic return on investment for every £1 of public funding.
Jane Martin, Managing Director Innovation and Investment, Scottish Enterprise, said: “FRIL is a shining example of how collaboration between industry, academia and regulators can make a real impact, utilising the development of advanced technologies to create high‑value jobs and attract private investment.
This funding underscores our commitment to fintech innovation and our support for innovative businesses, helping them to scale with confidence and build the global competitiveness of Scotland’s financial services sector.”
Aleks Tomczyk, Chief Executive, FinTech Scotland, added: “The opportunity from the current and forecast future growth of fintech is huge. We are proud of FRIL’s impact to date. FRIL’s success evidences the strategic value of innovation to the economy and the strength of our fintech cluster in simultaneously delivering growth and better outcomes for consumers. Scottish Enterprise’s investment will use FinTech Scotland’s proven Innovation Labs model to accelerate innovation in large companies and speed growth in fintechs.”
Professor Eleanor Shaw, University of Strathclyde, stated:“We are delighted to be a partner again in delivery of FRIL phase 3. Continuing our triple helix partnership approach ensures we can deliver on our mission to drive positive impact through useful research, learning, and innovation. This approach has so far demonstrated its success in delivering for Glasgow City Region, and we are excited about supporting this to become a national programme.”
Derek Shanks, Technology Platform Lead, Lloyds Banking Group, commented: “We’ve supported three FRIL innovation calls as a challenge partner and have seen first-hand the value of this model. It brings together the right mix of expertise, technology and challenge to turn ideas into real solutions. We welcome Scottish Enterprise’s investment and look forward to building on this partnership over the next three years.”
Calum Murray, CEO and Founder, Amiqus, noted:“The potential impact delivered by FRIL over the next three years to the broader Ecosystem is enormous. Thanks to a previous FRIL financial crime innovation call, we were able to build, pilot and take to production new capability to directly support Virgin Money with their new business onboarding journeys.
This three-year commitment effectively sets the stage for collaborative and rapid progress across both financial services developing new capabilities with the support of a wide range of fintechs going forward. It’s a win win on all accounts.”
Benefits reliance rising in every region of Great Britain, new financial data shows
Smart Data Foundry launches new Benefits Reliance Indicator using transactional data from 5 million bank accounts
Smart Data Foundry has launched a new data indicator designed to help policymakers, local authorities and researchers better understand where people may be coming under increasing financial pressure.
The new Benefits Reliance Indicator, available through their map-based Economic Wellbeing Explorer uses aggregated anonymised transactional data from NatWest. This data covers five million consumer current accounts across Great Britain and highlights areas where benefits from Universal Credit, Housing Credit and Tax Credits constitute 20% or more of people’s incomes.
The launch comes at a time of continued cost-of-living pressure, with the Food and Drink Federation forecasting food inflation could reach up to 10% by the end of 2026 and the energy price cap expected to rise again this summer, local authorities face growing pressure to target support effectively. At the same time. Department for Work and Pensions statistics show that more than a third of people (32%) receiving Universal Credit are in work, underlining the growing role benefits play in supplementing low or variable incomes.
Unlike traditional survey-based datasets, the Benefits Reliance Indicator provides a near-real-time view of how people’s income composition changes month-to-month. The indicator measures the proportion of people in a local area for whom means-tested benefits account for 20% or more of total income. This threshold was developed in consultation with local authority stakeholders as a meaningful signal of financial vulnerability.
The data combines income from Universal Credit, Housing Credit and Tax Credit with earnings, pensions and other income sources to provide a fuller picture of financial wellbeing – and where communities may be more exposed to labour market changes and welfare policy reforms.
Data to 29 March 2026 reveals:
- A rising proportion of people across England, Scotland and Wales relying on benefits for at least 20% of their income. This has been rising for the last two years. Scotland has seen the biggest increase, at 1.83% over the past 2 years, with benefits reliance in Wales increasing by 1.7% and in England by 1.25%.
- There are strong regional variations within England, Scotland and Wales:
- Wales has the overall highest rate of benefits reliance, with South East Wales at 9.36% – an increase of 2.11 percentage points over the last two years. Whilst North Wales has the lowest proportion at 6.64%, it has also seen a rise in benefits reliance over the last 2 years, as has Mid and South-West Wales – rising from 6.05% in March 2024 to 7.59% in March 2026.
- In Scotland, overall reliance is lower than in Wales and whilst there is an upward trend, it is much less steep. However, in recent months Eastern Scotland has seen a rise of 4.82 percentage points to 7.37% of our sample in that region with incomes consisting of 20% or more from Universal Credit, Housing Credit and Tax Credit. West Central Scotland has seen a similar rise, with a 2.42 percentage pointincrease over two years and 8.38% of our sample now showing benefits reliance. North East Central and the Highlands and Islands have shown the smallest increases, both under 1 percentage point.
- In the North of England, the area with the highest rate of benefits reliance is North East England, at 9.49% of our sample. North East England is also the region with the biggest growth (1.6 percentage points), followed by Yorkshire and the Humber (1.51 percentage points and North West England (1.42 percentage points).
- In the South of England, benefits reliance becomes less prevalent; the South East has the lowest proportion at 4.85%, but similarly to Scotland and Wales all English regions are seeing a growing reliance on benefits. London is an outlier in the south, with 7.75% of our sample showing benefits reliance.
The new indicator has been developed to help organisations identify emerging hardship earlier, target support more effectively and monitor the impact of welfare reforms, labour market changes and wider economic shocks. It will be updated monthly, and can also be filtered by age group and income range.
Dougie Robb, DEO of Smart Data Foundry added “Too often, financial hardship only becomes visible once people reach crisis point. By showing where people’s incomes are supplemented by means-tested benefits in near real time, we can better understand the role these benefits play in supporting people’s living standards – and where financial vulnerability is building.
“That means organisations can better understand changing economic conditions and target support where it may be needed most, as well as evaluate policy changes much more quickly.”
The Benefits Reliance Indicator is available to all users of the Economic Wellbeing Explorer, alongside a companion aggregated research dataset in Smart Data Foundry’s secure research environment, MyFoundry. The Economic Wellbeing Explorer is free to access at national and regional level, with local-level data available on subscription. Organisations interested in understanding benefits reliance within their own local authority area can request a personalised walkthrough of the data and platform.
To support the launch, Smart Data Foundry will host a webinar on 26 May 2026 exploring the new indicator, emerging trends and practical applications for targeting interventions and tackling poverty.
Navigating Consumer Duty: The Hidden Cost of Friction
By Shiyu Chen, behavioural scientist and founder at BehaviourAI Lab
Consumer Duty has reshaped the way financial services firms need to think about customer journey. The FCA’s shift from tick-box compliance to outcome-based evidence doesn’t come with sirens or warning, but it does change the ground we’re standing on.
What used to be a design preference is now part of a firm’s regulator responsibility. And this shift invites a different kind of conversation: not about what we’ve declared to customers, but about what they actually encounter.
It’s time to step back, understanding how user journey shapes outcomes, and to diagnose, redesign, and measure those behavioural dynamics through a behavioural science approach.
Sludge: The Silent Enemy in Consumer Duty
Behavioural scientists often talk about nudges – subtle design choices that help people make better decisions. But there is a darker twin: sludge. Where a nudge supports good outcomes, sludge creates friction that slows, confuses, or traps consumers, often preventing them from acting in their own best interests. Sometimes it’s deliberate. More often, it’s accidental by product of growth driven design.
Under Consumer Duty, however, sludge is no longer a UX flaw. It is a regulatory risk. In other words, user journey is no longer a design preference; it is a regulatory obligation.
From Theory to Practice: Where Sludge Hides
Across the four Consumer Duty outcomes, sludge shows up in predictable and measurable ways. Here are some of the most common patterns observed when conducting behavioural diagnostics:
In Consumer Understanding, sludge emerges when complex layouts bury key risks “below the fold”, leading users to skim past critical information. This becomes visible when users spend only a few seconds on a lengthy Terms and Conditions page before clicking “Accept”.
In Consumer Support, sludge takes the form of exit friction, where cancelling a product requires far more effort than signing up. For example, a two step onboarding journey contrasted with a ten step cancellation process.
In Price & Value, sludge appears through fee shrouding, where total costs are only revealed at the final payment stage, often triggering sharp drop offs when users encounter unexpected charges.
In Products & Services, sludge shows up as dark nudges, such as urgency cues (“Only 2 left!”) that push consumers toward unsuitable choices, reflected in high cooling off cancellations shortly after purchase.
These patterns aren’t simply UX quirks. They are behavioural signals that parts of the journey may be misaligned with Consumer Duty expectations.
Evidence in Practice: Decoding the Metrics
Understanding where harm may emerge in a user journey often begins with simple behavioural signals. Metrics such as reading time vs. scroll depth reveal whether customers meaningfully engage with key information. Similarly, basket abandonment at payment indicates moments where unexpected fees or late‑stage cost disclosures prompt users to drop off.
Other indicators point to friction that distorts decision‑making. The parity ratio can reveal disproportionate effort that may hinder Consumer Support. And the reversal rate often signals that urgency cues or other dark patterns may have pushed users toward unsuitable products.
These metrics don’t provide the full diagnostic picture, but they offer early behavioural clues about where journeys may be creating unintended barriers or risks.
The Behavioural Toolkit: Hook-Fix-Proof
The BehaviourAI Lab offers a structured approach to help financial services firms identify and mitigate sludge before it becomes a regulatory issue. The Hook-Fix-Proof framework integrates behavioural diagnostic, behavioural design, and behavioural validation to improve user journeys.
Hook focuses on identifying the behavioural dynamics that create sludge – the friction points, hidden barriers and decision pathways that shape how users actually behave. This stage surfaces the subtle patterns that traditional UX reviews often miss.
Fix applies choice architecture principles to redesign those pathways, removing unnecessary friction and reducing sludge so that decisions become clearer, smoother, and more aligned with users’ goals. The emphasis is on enabling better choices, not nudging toward predetermined ones.
Proof brings empirical validation, using behavioural measurements to demonstrate whether the redesigned journey truly improves outcomes. This stage provides the outcome based evidence that Consumer Duty now expects – showing measurable behavioural change, not just good intentions.
Is your product journey hiding a Sludge Red Flag?
At BehaviourAI Lab, we help financial services firms diagnose, redesign, and validate their journeys using behavioural science and metrics that evidence Consumer Duty outcomes.
Don’t wait for the regulator to spot the friction. Book a Sludge Diagnostic and get ahead of the risk.