
Creating fairer financial futures: A focus on the fintechs
Innovation starts with people. That’s our belief at the Financial Regulation Innovation Lab (FRIL), and that’s why we bring together pioneering fintech entrepreneurs with industry and academia to address challenges facing financial services – both now and for the future.
At FRIL’s latest Innovation Call, fintech entrepreneurs took on one of the most significant regulatory shifts in the sector, pitching ideas that could change how millions of people access financial support and move us closer to fairer financial futures.
But what really drives these fintech founders, and what happens behind the scenes for them at an Innovation Call?
We spoke to two of the founders who took to the stage to find out more.
First of all, let’s meet Crawford Taylor, a co-founder of Afternoon, a data and AI operating model for financial advisors
Crawford, you’ve just come off the stage, but before we hear about that, please tell us, what exactly is a ‘data and AI operating model for financial advisors’?
“Sure, it means that we collect the data financial advisers need to support their clients, enrich it, and then use AI to automate their workflows. That significantly reduces the time it takes for advisers to deliver advice, so they can focus more on their clients.”
And why does this area matter to you?
“Before this, I worked as a consultant advising trustees and companies on defined benefit pension schemes, helping secure the future for people who already had a pension so they’d receive what they were due at retirement. This feels like a natural extension of that, helping more people manage their money better and be financially better off.”
You’ve just pitched at our Innovation Call, how did that go?
“I think it went well. With 19 other companies pitching to a panel of around 10 large corporates, including organisations like M&G, NatWest, and Sopra Steria, it’s a great opportunity to explore potential partnerships.”
As a fintech founder, what is your big ambition?
“There’s around £18 billion spent on financial services technology every year, and it’s only going to grow, yet there’s still a huge advice gap, where many people can’t access or afford support. So much time is lost joining the dots, from opening accounts to moving money. Our ambition is to automate that entire process, so advisers have everything at their fingertips and clients can go from advice to action – opening accounts and transferring funds – in seconds.”
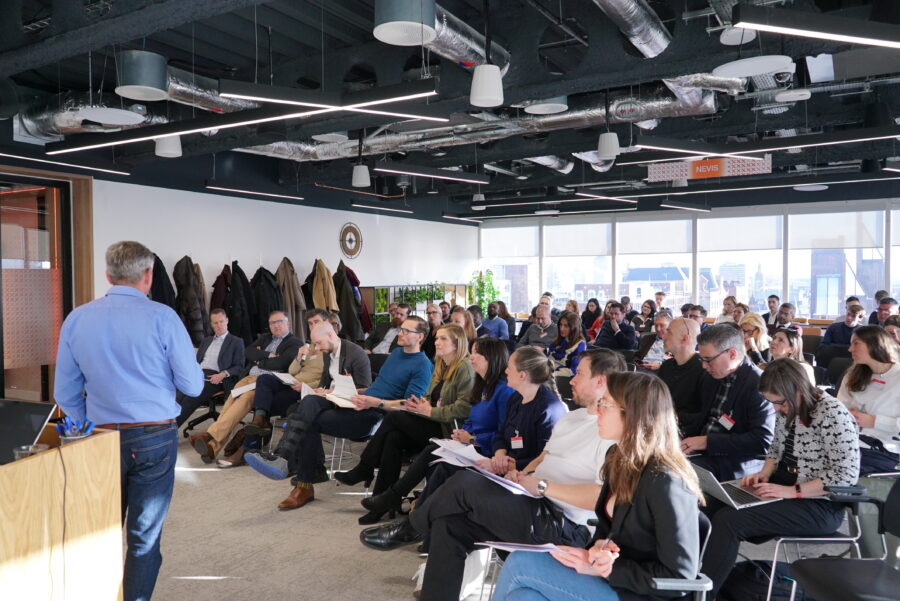
Thanks Crawford, and final question, what has being involved in the Innovation Call meant for you?
“It’s been energising. The Innovation Call was exceptionally well designed; it respected how stretched early-stage teams are, while still pushing to sharpen our thinking and ambition. The combination of regulator insight, industry partners, expertise from Growth Builders and practical support created real momentum for us. Huge thanks to Fintech Scotland and everyone involved.”
And now let’s hear from another fintech founder, please meet… Dia Banerji, founder of Cherpa.ai, an AI money coach that delivers hyper-personalised financial education.
Dia, you’ve just done your pitch – how did it go?
“I was first up, which always adds a bit of pressure, but it felt good. The presentation went well. Most importantly, I was able to clearly tell the story of why Cherpa.ai exists.“
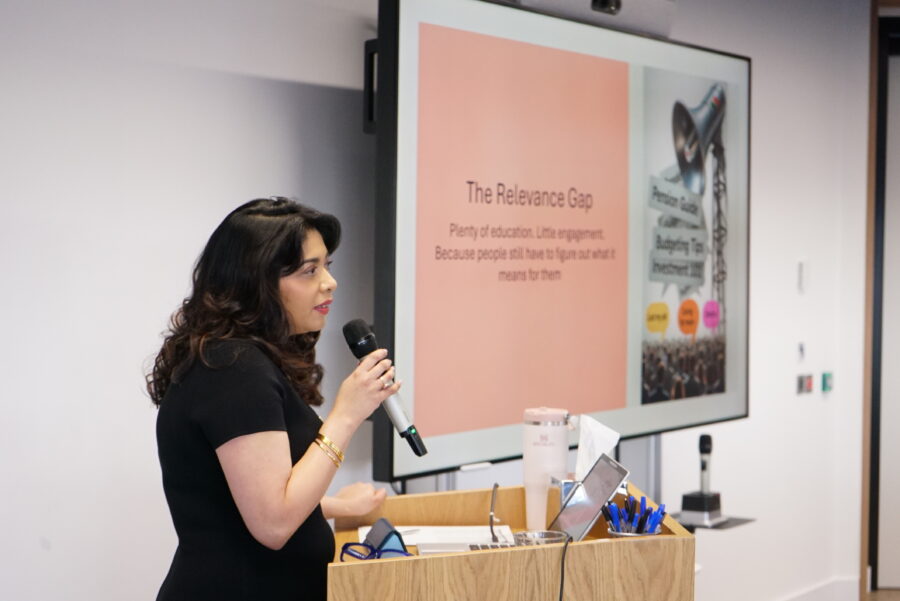
And on that note, Dia, why does Cherpa.ai exist?
“It is very close to my heart. So many people feel a real sense of shame when they don’t understand money, and that keeps them from asking questions. I recently ran a survey about money confidence, one person told us their biggest wish was simply to feel less ashamed about talking about money – and that really stayed with me. Cherpa is here to change that and help people connect with their money and navigate life with confidence. Because every life moment is a money moment.”
Why does this call matter to you?
“This call matters a lot to Cherpa & me personally. More than 90% of people in the UK can’t access financial advice, and there’s a big step before advice that’s really about awareness and education. People often see ‘investment’ as something for someone else, and financial education is still very low, which leaves people disconnected from their money. That’s why this call feels important, not just for the UK but for the world.”
And are there any particular aspects that have struck you over the last few weeks?
“I’ve been really happy to be part of this cohort. The run-up has been amazing, with sponsors coming in, sharing their problem statements, and giving us time to learn from them and from the other fintechs. It’s been great to feel part of a real community and to play a small part in helping Scotland thrive.”
What are your hopes for the result?
“I’m really excited to be part of this cohort and would love to work more closely with some of the sponsors. Beyond that, it’s about being part of a wider fintech community, learning from others, and helping Scotland, and ultimately people everywhere, build more confidence and connection with their money.”
So what next for the fintechs who took part?
With the winners now announced, the successful teams will receive grants of up to £50,000 to develop, scale and implement their ideas over the coming months.
But the journey doesn’t end there. Beyond the winners, many of these ideas are likely to spark further interest, partnerships and pilots in the months ahead.
If you’d like to find out more about the work of FRIL, please contact us at FRIL@fintechscotland.com.
About FRIL
Financial Regulation Innovation Lab awards £50,000 each to four fintechs to accelerate consumer wealth support
The Financial Regulation Innovation Lab (FRIL) today announced the four fintechs selected to receive grants through its latest Future of Wealth Innovation Call, delivered by FinTech Scotland in partnership with SuperTech WM.
The six‑week programme concluded on 15 January with a Showcase Day, where 21 fintechs presented solutions to the challenge: helping consumers make informed financial decisions and access more tailored wealth support, while keeping pace with evolving regulation.
Throughout the programme, and against the backdrop of the joint HM Treasury-Financial Conduct Authority (FCA) Advice Guidance Boundary Review (AGBR) which seeks to help close the UK’s advice gap by clarifying how firms can provide more meaningful support under the Consumer Duty, participants took part in workshops and deep dive sessions to develop, refine and tailor their propositions to real world industry needs and potential pilots with partners. The FCA was involved throughout and provided both valuable clarity and guidance.
The Innovation Call was delivered with the support of 10 strategic partners: PwC, Barclays, Lloyds Banking Group, Sopra Steria Financial Services, NatWest Group, M&G, BNP Paribas Personal Finance. , Dudley Building Society, Wesleyan and Standard Life; alongside academic partners at the University of Strathclyde and the University of Glasgow, and Growth Builders, which supported delivery.
Following the Showcase Day, four fintechs were selected to receive £50,000 each to further develop their solutions. Over the grant period, the awardees will continue to collaborate with industry and academic partners to test, validate and accelerate their innovations towards adoption and scale.
The winners are:
Finspector is an AI-powered compliance platform that automates the review and monitoring of financial promotions across text, images, video, and social media. It helps regulated firms reduce risk, evidence compliance, and scale marketing activity with confidence across jurisdictions.
Planda is a behavioural AI platform that helps financial services firms move beyond outdated segmentation to deliver hyper-personalised customer engagement. By connecting data across enterprise workflows, Planda builds dynamic customer segments that evolve in real-time, enabling institutions to personalise at scale and deepen relationships.
Amplified Global uses AI and Machine Learning to help firms assess, simplify, and demonstrate consumer understanding at scale, ensuring they meet compliance obligations with confidence. Its technology analyses and enhances intelligibility, helping organisations turn complexity into clarity. Through a guided digital journey, it makes content more engaging, measurable, and human – redefining how people connect with information.
Afternoon’s the new data + AI first operating model for advice firms. Data collection is automated with a focus on completeness and quality. AI modules automate work, allowing a doubling of clients with the same team and with less risk from meeting to report in under 2 minutes.
Aleks Tomczyk, Chief Executive, FinTech Scotland, commented:
“The Advice Guidance Boundary Review is pivotal to widening access to meaningful financial support across the UK. Too few people are saving adequately for retirement, and historically advice has skewed towards higher earners. Government, regulators and industry are aligned on helping the wider population make better‑informed financial decisions. By funding these four winning projects and opening real‑world pilots with partners, we’re accelerating practical solutions that improve consumer decision‑making and access to support, while helping firms operate confidently within the advice–guidance boundary.”
Kate Murray, Strategic Projects Lead, Scottish Widows & Lloyds Banking Group, said:
“We want to fill the advice gap that currently exists in Britain and ultimately, enable people to have a much more prosperous financial future. The Innovation Calls present such a massive opportunity. We at Lloyds Banking Group are changing the way we do change and innovate to go faster. Bringing in outside thinking, technology, and just a completely different perspective can help us achieve that.”
Hilary Smyth Allen, Chief Executive, SuperTech WM, added:
“Partnership matters because that’s how you really get things done with impact. Through the partnership with FRIL, we’ve been able to work across a broader spectrum of the ecosystem. Consumers come in all shapes and sizes, and so does the industry that services them. Innovation for us means we are maximising outcomes for those consumers.”
Crawford Taylor, CEO & co-founder, Afternoon Finance, stated:
“The advice gap is real, and firms are under growing pressure to support more people, with better outcomes, under tighter regulation. Afternoon exists to make that possible, using data and AI to remove friction, reduce risk and radically improve how advice is delivered.
This funding allows us to continue to accelerate our mission: helping advice firms support more clients, more effectively, without compromising quality, compliance or trust. Being selected as one of just four winners from over twenty fintechs is a huge validation of the approach we’re taking.”
About FRIL
Creating fairer financial futures: A spotlight on FRIL research
Technology-enabled advice, Regulation and the Advice Gap: 10 minute Insight from FRIL Research. 10 Questions with Chuks Otioma, Research Associate, Adam Smith Business School
As financial services explore new ways to close the advice gap, technology enabled advice and guidance models are increasingly part of the conversation – but what do they really mean for consumers, firms and regulation?
As part of the Financial Regulation Innovation Lab (FRIL), researchers from the University of Glasgow and University of Strathclyde are working alongside industry, fintechs and regulators to examine how innovation can be deployed responsibly in financial services.
In this conversation, Chuks Otioma, Research Associate, reflects on his research into these digitally- enabled advice models: what they are, why they matter, and how they sit within the Advice Guidance Boundary Review.
1. Chuks, let’s start with you first of all – what drew you to this field of research?
Before moving into academia, I worked in industry, in telecommunications. During my PhD, I looked at the links between digital capabilities, innovation and economic performance, and the role of entrepreneurs and innovators in leveraging digital advances; work that now informs my research into AI in financial services. I was particularly interested in how firms reorganise themselves, their processes, structures and activities in order to draw value from digital technologies.
At that stage, my work wasn’t focused on financial services specifically. It was broader, looking at firms across sectors and how they approach digital transformation. What I’m doing now is a natural progression of that work, but with a much sharper focus on financial services and the challenges firms face in deploying technologies like AI.
2. OK, let’s explore your research Chuks. First of all can you explain to us what “technology-enabled advice and guidance models” actually are?
At a basic level, the term refers to digitally enabled advice. It can be relatively simple, or more advanced, using AI to construct and refine portfolios.
What’s important is the way technology can help streamline advice around individual needs. But this also raises important considerations. You have to think carefully about the data being used, the potential for data breaches, and whether consumers genuinely understand the advice they’re receiving.
There are also different operating models. Some are largely consumer-led, with minimal human interaction. Others are more professional-led, where investment or wealth managers use automated tools to manage portfolios on behalf of clients. Each model raises different questions around responsibility and duty of care.
3. The Advice Guidance Boundary Review aims to ensure that financial help is clearer, fairer and available to far more people. How do these technology-enabled models play a part here?
Some forms of digital advice function as guidance, pointing consumers towards information or helping them explore options. Others go further, making recommendations or even decisions on a client’s behalf, which brings them firmly into the realm of regulated advice.
That distinction matters, particularly as systems become more advanced. The more decision-making is delegated to automated systems, the more important strong compliance, governance and accountability become.
4. Can these models really help address the financial advice gap?
There is evidence that automated advice has already improved access and inclusion, particularly among younger people and those who might not otherwise engage with traditional investment services.
Because these systems can draw on rich data and integrate information from multiple sources, they have real potential to support people who currently lack access to advice.
What’s especially interesting is the way some platforms are beginning to connect users to independent financial advisers, recognising that investment decisions don’t exist in isolation. Financial wellbeing also involves literacy, planning and understanding long-term goals.
“These systems have real potential to support people who currently lack access to financial advice.”
5. What risks need to be managed as technology-enabled advice and guidance becomes more common?
In our research, we look at several dimensions. There’s the operating model, and how responsibility is shared between consumers, professionals and platforms. There’s financial risk, including market volatility, trend-chasing and over-concentration.
We also examine data practices, including how platforms are designed, who has access to data, and how data is shared across third parties and jurisdictions. In many cases, the developer of the system is not the same as the organisation managing it, which raises important governance questions.
“When advice becomes more automated, firms need to be clear about who is responsible when things go wrong.”
6. What has surprised you most in your research?
One of the most striking findings is the level of consumer misunderstanding. Products are often designed on the assumption that firms understand their users, but in practice there can be significant misalignment between innovation and user understanding.
This isn’t necessarily about consumers lacking capability. It’s often about how products are designed, communicated and framed. That’s a critical lesson for firms designing these products.
7. What big questions does this raise for firms and for the industry?
One of the big questions is around responsibility and accountability, particularly as more decision-making is delegated to automated systems. When advice becomes more automated, firms need to be clear about who is responsible when things go wrong.
Beyond that, these developments also raise important questions about how firms organise themselves. Automated advice reshapes how services are delivered, which has implications for workforce skills and training. Technical teams increasingly need some understanding of finance, while those working in finance or customer support need a basic understanding of how AI-based systems work.
There are also strategic questions around how these systems are developed and deployed. Firms need to decide whether to build solutions in-house or rely on third-party providers, and how external systems integrate with existing or legacy technologies. These choices affect how services are scaled and managed over time.
Taken together, these are organisational challenges as much as they are technological ones, and they shape how firms deliver automated advice in practice.
8. With all this in mind, what future are you trying to help shape through this research?
For me, the most important thing is societal relevance. I’m interested in research that informs policy-making and speaks directly to real-world challenges.
FRIL is quite unique in that sense. The challenges we work on are industry-led. You have problem owners defining the issues they face, fintechs developing solutions, and researchers contributing evidence and insight that can help shape both practice and regulation. It’s impact-oriented research, and that’s very fulfilling.
Ultimately, the future I want to contribute to is one where research doesn’t sit in isolation, but actively helps address the problems faced by industry, policymakers and society more broadly.
9. Can you share some examples of wider real-world challenges you’ve been working on?
One example is our work looking at consumer complaints within financial services. By analysing the types of complaints that are escalated to the Financial Ombudsman Service, and how providers respond to them, we can better understand where things go wrong.
If we understand these friction points, there’s an opportunity to co-develop financial products differently, reducing the likelihood of harm or escalation in the first place.
In our work on automated advice, we’ve also explored how providers can embed responsible practices into their models. That includes linking clients to green or sustainable investment opportunities, and aligning portfolios not just with financial returns, but with broader social and environmental goals.
“Automated advice reshapes how services are delivered, with implications for workforce skills, training and how firms organise themselves.”
10. Finally, what feels special about doing this research here, in Scotland, and within the FRIL ecosystem?
What stands out for me is the research culture and the ecosystem we’re working within. The University of Glasgow, and the Adam Smith Business School, have a strong international research culture, and we work very closely with colleagues at the University of Strathclyde and with industry partners.
Beyond the universities, there’s something distinctive about how this work comes together in practice. Through FRIL, you have financial services providers, fintech developers, regulators and researchers working together on a daily basis. It’s what we often describe in theory as an “ecosystem”, but here it’s very real.
That makes it a unique environment for doing this kind of research, not in isolation, but embedded in the real challenges facing industry and society.
Explaining the terminology
- Technology-enabled advice: A digital tool that uses information about a person to help guide or automate investment decisions based on their individual needs.
- The Advice Guidance Boundary Review. Just what does it all mean?
- Advice: A regulated service where a financial adviser looks at your full financial situation and gives you a personalised recommendation.
- Guidance: Support that points you in the right direction based on limited information you share, without telling you exactly what to do.
- Boundary: The line that separates advice from guidance, defining how much information is needed and what a firm can or can’t recommend.
- Review: The FCA’s process of consulting industry and consumers, and government to create clear new rules that will shape how these services work in future.
What next?
Interested in the research generated by FRIL? Then check out our White Papers across a range of subjects.
For more detail on this topic, see Chuk’s white paper.
If you’re interested in the work of FRIL more generally and would like to contact a member of the team email FRIL@fintechscotland.com.
About FRIL
Creating Fairer Financial Futures – AGBR Innovation Showcase Day
On 15 January 2026 in Glasgow, more than 100 people gathered for a high-stakes showcase.
The purpose of the gathering?
To address one of the most important regulatory shifts in financial services today. A shift which could reshape how millions of people access financial support and create fairer financial futures for all.
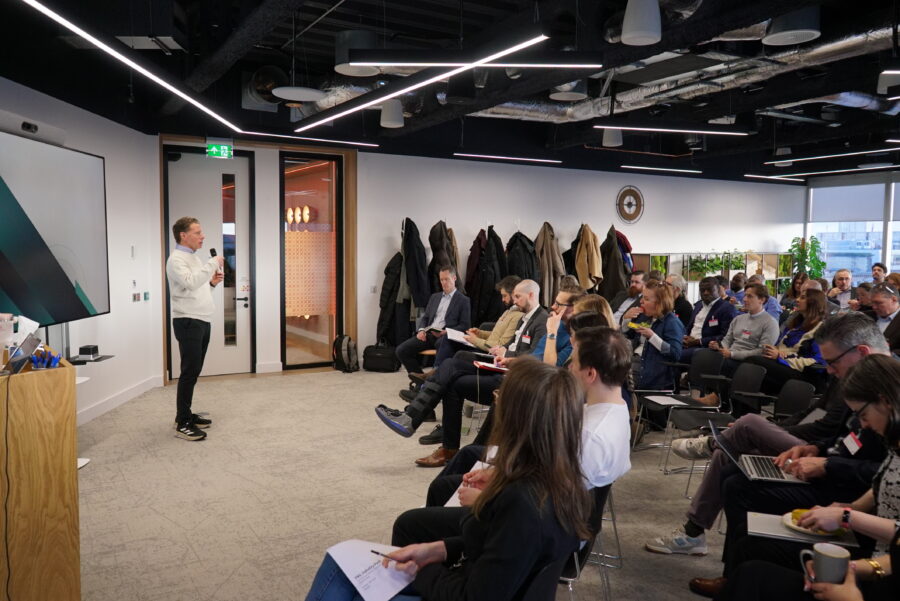
The event was the final showcase day of an Innovation Call – a pioneering initiative led by the Financial Regulation Innovation Lab (FRIL) at the heart of FinTech Scotland.
But, what is an Innovation Call, what happens on showcase day and what is achieved?
Well, join us as we take you behind the scenes of the day and speak to some of the people involved.
Let’s start with Clare Reid, Strategic Innovation Director at FRIL.
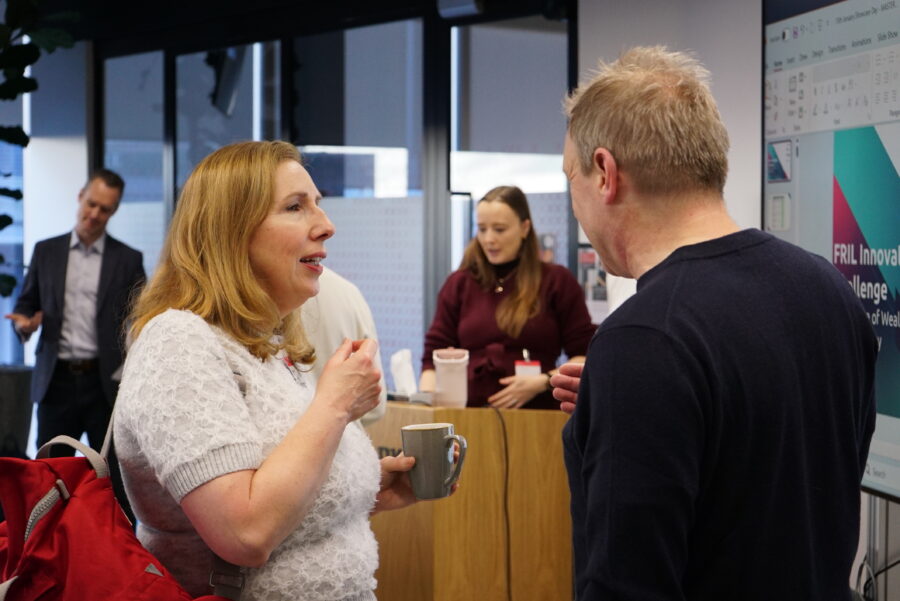
Clare, explain to us what to expect on a Showcase Day of an Innovation Call?
“Nerves certainly run high on showcase day of an Innovation Call! It’s the culmination of months of work for Fintech entrepreneurs as they pitch their solutions to an audience of potential Financial Services partners. And the stakes are high – there is an award of £50,000 to successful fintechs and the opportunity to take forward some potential game changing solutions and partnerships with those partners.“
What was the challenge or opportunity today’s call addressed?
“This call focused on the FCA’s Advice Guidance Boundary Review – which is addressing a very human issue about how to make financial help clearer, fairer and available to far more people.”
“The call is all about finding new ways to help consumers make informed financial decisions, delivering more accessible and tailored support while staying within evolving regulatory expectations.”
Who was involved?
“The call brings together fintech entrepreneurs, financials services and academia, who are all tackling some of the biggest challenges in financial services today.”
Let’s hear from one of the Fintech founders pitching today to hear their side of the story. Dia Banerji, founder of Cherpa.ai:
Dia, you’ve just done your pitch – how did it go?
“I was first up, which always adds a bit of pressure, but it felt good. The presentation went well. Most importantly, I was able to clearly tell the story of why Cherpa.ai exists.”
What was your pitch addressing?
“Cherpa.ai is an AI money coach that delivers hyper-personalised financial education. The pitch focused on the huge gap before financial advice – helping people build awareness, understanding, and confidence about their money, so they’re better prepared to make decisions.”
What are your hopes for the result?
“I’m really excited to be part of this cohort and would love to work more closely with some of the sponsors. Beyond that, it’s about being part of a wider fintech community, learning from others, and helping Scotland, and ultimately people everywhere, build more confidence and connection with their money”
And on that note, let’s hear from Kate Murray who works for Scottish Widows as part of Lloyds Banking Group.
What has struck you about the pitches that you’ve heard today?
“What’s really struck me is the breadth of innovation on show – from fintechs tackling very niche, complex problems to those covering the entire end-to-end customer journey. It’s impressive what they’ve delivered in such a short time, and the quality of the user interfaces has really stood out to me. They’re slick, well thought-through, and genuinely exciting to imagine working with as we design our future journeys.”
What does AGBR mean for your firm, and why does this call matter?
“For us, AGBR is about helping more people secure their financial futures, in a way that aligns with our wider purpose of helping Britain prosper. There’s a real advice gap in the industry, and a big void in the middle where people don’t know what to do next — how to save, how to prepare for retirement, or how to make better decisions. We see innovation and new solutions as a way to bridge that gap, giving people the clarity and confidence to take the next step towards a more prosperous financial future.”
“The Innovation Call matters because we’re always reviewing how we change, innovate, and go faster. And sometimes, being part of a big organisation slows us down. Bringing in outside thinking, new technology, and completely different perspectives helps us bridge that and move quicker.”
And let’s finish with Christine Sinclair, Programme Director for FRIL at the University of Strathclyde.
Christine, that was quite a day…anything else that might surprise us about an Innovation Call?
“It doesn’t stop here. There are many layers to an Innovation Call. While the successful fintechs will go on to partner with a financial services firm and grow their businesses, the research by the academics involved in the call is captured in White Papers to support industry learning.“
“The insights also shape current and developing skills programmes hosted by the University of Strathclyde and the University of Glasgow. These are aimed at helping people develop the skills they need to adopt new technologies responsibly, whether that’s AI, data, digital transformation or ESG reporting.”
Sounds interesting? You can hear more about those courses in this interview with Christine.
So what next for the fintechs who took part?
Now, the wait begins! Next week the judges will decide which teams will be awarded grants of up to £50,000 to develop, scale and implement their ideas.
But the journey doesn’t end there. Beyond the winners, many of these ideas are likely to spark further interest, partnerships and pilots in the months ahead.
We’ll keep you posted.
In the meantime, if you’d like to find out more about the work of the Financial Regulation Innovation Lab, please contact us at FRIL@fintechscotland.com.
About FRIL
FinTech Scotland marks its eighth anniversary reinforcing its position as one of Europe’s leading fintech clusters
Marking its eighth anniversary, FinTech Scotland reports that the nation’s fintech cluster has more than doubled in size in the past five years – from just over 120 firms in 2020 to more than 260 – confirming Scotland’s position as one of Europe’s most dynamic and collaborative fintech clusters.
This growth has been driven by higher levels of investment, deeper partnerships across industry, academia and the public sector, and more businesses scaling up and trading internationally.
Innovation in practice has also taken a major step forward, with the 10-year FinTech Research and Innovation Roadmap now embedded and over 40% of recommended actions under way. Central to this has been the 2025 award-winning Financial Regulation Innovation Lab (FRIL), which plays a key role in creating the right conditions for collaboration and product development. A recent example is the partnership between Amiqus and Virgin Money: through the FRIL programme, Amiqus moved from an initial pilot to live production with Virgin Money, using AI to transform business banking onboarding – demonstrating the capability and scalability of its platform.
In 2025, the cluster also launched two major new initiatives: the Centre of Excellence in Distributed Ledger Technology, focusing on digital assets, payments and tokenisation, with digital trust at its core, and the Finance and Health Lab a pilot cross-sector research and innovation programme dedicated to improving financial wellbeing, resilience and long-term financial health in Scotland.
Looking ahead to 2026, FinTech Scotland will focus on translating innovation into economic and social value, in line with UK industrial policy priorities, and enabling all participating in the cluster to thrive.
Aleks Tomczyk, Chief Executive of FinTech Scotland, said:
“The doubling of Scotland’s fintech density is a clear signal that our collaborative and cluster-based approach is working. The Research and Innovation Roadmap provided a national framework to accelerate purposeful innovation, and it’s been inspiring to see how fintech entrepreneurs, financial institutions, and universities have got behind that shared vision.
As I begin 2026 as FinTech Scotland’s new Chief Executive, I look forward to leading our plans to support the next stages of cluster growth and thereby accelerate successful business growth and innovation in financial technology.”
Jane Martin, Managing Director of Innovation and Investment at Scottish Enterprise, added:
“A major strength for Scotland is its connected fintech cluster, an inclusive network of entrepreneurs, researchers, and industry leaders working together to solve real world challenges. This growth shows that Scotland can have a global impact by focusing on purposeful and collaborative innovation.”
Callum Murray, CEO of leading fintech firm Amiqus, said:
“FinTech Scotland has provided practical ongoing support to Amiqus and many other fintech scale ups across the country for many years. Our involvement in their FRIL innovation programme dramatically accelerated relationships with large scale banks, built trust in our capability to deliver at scale and directly led to us securing a new ongoing client partnership. We look forward to the collaborative opportunities working with the Fintech Scotland team over the years ahead.”
Why Upskilling can’t wait: Building Smarter Skills for a Smarter Financial Future
Q&A With Christine Sinclair
Programme Director, Financial Regulation Innovation Lab (FRIL), University of Strathclyde
Financial services is undergoing one of the most significant periods of change in decades. Technology is advancing at pace, new regulations are emerging, and organisations of every size are wrestling with the skills needed to keep up. The Financial Regulation Innovation Lab (FRIL) was created as a catalyst to help the sector respond, to support better outcomes for consumers, strengthen the industry, and enable fintech entrepreneurs to innovate with confidence.
Central to this mission is a progressive skills development programme delivered in partnership with the University of Strathclyde and the University of Glasgow. Together, they’re building a portfolio of Microcredentials (which gain academic credits), short courses and executive education that help people across financial services understand, adopt and apply new technologies responsibly and effectively.
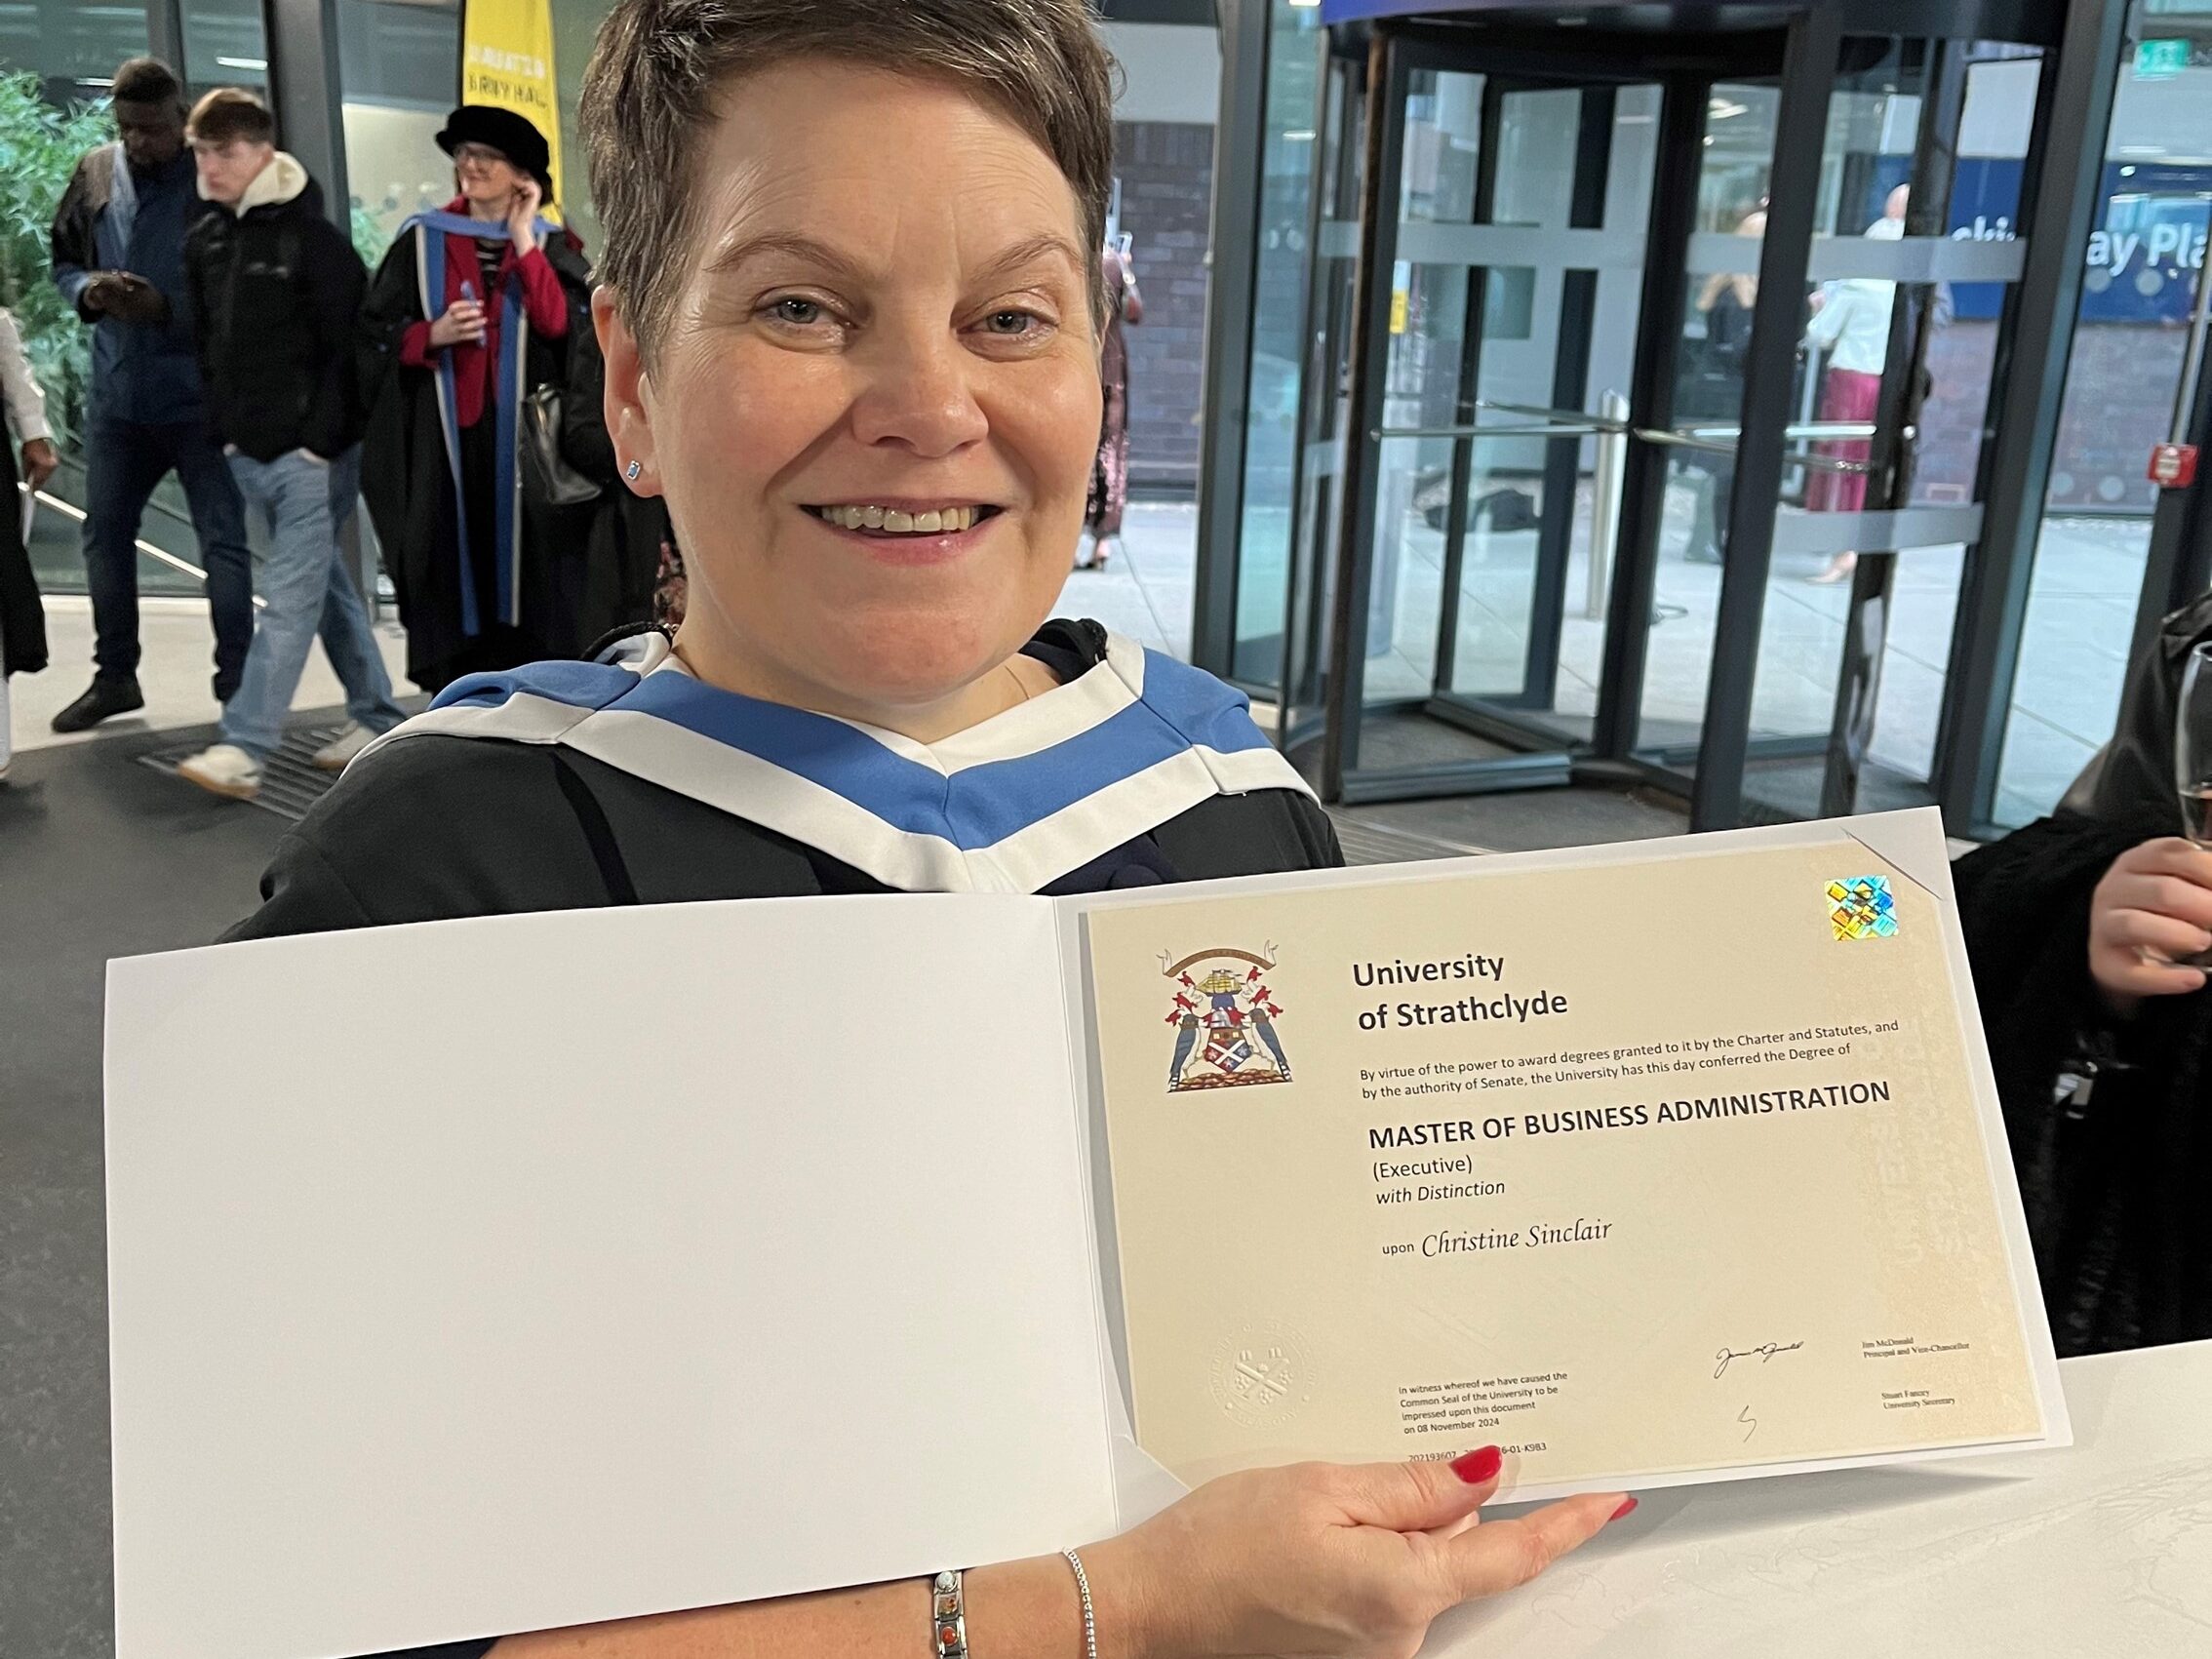
Christine Sinclair, Programme Director, FRIL, University of Strathclyde
Here, Christine Sinclair, Programme Director for FRIL, explains why this work matters, and why now is the time to invest in the future skills of the sector.
Q 1 – Hello Christine, let’s start with the big questions first… what challenge are you addressing here, and why does this matter?
A 1- When you look across financial services, the message is the same everywhere: the pace of technological change is relentless, and people and industry need to keep up. The biggest example right now is generative AI. There’s a real desire to understand it, but also a lot of uncertainty.
When you look at the evidence around AI adoption, the barriers are strikingly consistent. Many organisations hold back because they don’t have the skills or confidence to implement it safely. They don’t fully understand the risks, or they’re concerned about data management and governance. A lot of this is driven by the hype cycle, which can be overwhelming.
So the challenge we’re addressing is simple but vital: helping people develop the skills they need to adopt new technologies responsibly, whether that’s AI, data, digital transformation or ESG reporting. And what we’re doing is demand-led, we’re not creating courses and hoping people want them. We’re listening closely to what financial services and fintechs tell us they need.
Interestingly, the needs differ. Fintechs tend to be highly technical but often need more support with leadership, negotiation and change management. Larger financial institutions have deep organisational knowledge, but they often need help with the technical understanding. So it’s about supporting both sides, and helping both work together…
…and it’s all really important because with the speed of change, the biggest risk is to do nothing.
Q 2 – Who are the courses for?
A 2 – They’re for anyone in financial services, from credit unions to fintechs and large institutions to board-level executives.
A lot of participants join because they want to refresh their own skills. Others are sent by employers who know they need to build capability quickly. And we’re seeing more early-career professionals who want to understand the fundamentals of digital transformation or AI as they move into new roles.
What’s important is that the courses meet people where they are. You don’t need a technical background. You just need curiosity and a willingness to learn.
As a result of the success of the programmes developed for financial services, we’ve also welcomed people from energy and health sectors where the challenges are very similar.
Q 3 – What’s unique about this particular skills offering?
A 3 – The comprehensiveness. There are plenty of short “how to prompt engineer” or “what is GenAI” sessions out there, but they tend to cover only one slice of the picture. FRIL’s courses build from fundamentals all the way through to practical application in financial services.
For example, our AI microcredentials are designed to allow learners to understand and engage with AI in a structured and progressive manner. Focussing on core concepts and techniques, such as machine learning and large language models, but also, cover risk, governance and data science, and communication skills, whilst including real industry use cases which demonstrate practical application. For executives, we even include topics such as decision-making through AI driving business insights in the boardroom, AI Governance and compliance, as well as AI in Enterprise Risk Management and developing strategies to implement and scale GenAI.
Everything is designed to be flexible and accessible. You can learn in your own time, supported by lecturers who track your engagement and are available when you need help. It’s comprehensive without being overwhelming.
Q 4 – What kind of courses are currently being offered?
A 5 – We’ve developed microcredentials in Digital Transformation, ESG for Executives, and a full AI literacy suite, from beginner to advanced, plus an executive-level course. And there are programmes in AI & RegTech, and ESG Leadership.
We originally planned to deliver two microcredentials. We’ve delivered ten due to demand. Seven at Strathclyde, two at Glasgow, and one short course through the UK Government’s Help to Grow programme at Strathclyde. Our microcredentials are accredited and can stack towards a postgraduate qualification, so learners build credits over time.
For those who don’t wish to earn credits, we are now looking at awarding digital badges so learners can showcase their acquired skills on LinkedIn or their CV.
Q 5 – What format do the courses take?
A 5 – In general, course delivery is blended. Each week, participants complete short online lectures, which are no more than 15 minutes each. This, along with reading and other practical activities helps them apply what they’ve learned and typically brings the total up to around two to three hours per week.
We run online inductions, drop-in webinars and a final in-person consolidation session on campus. That’s where the learning community really comes together. Everyone arrives with the same foundation and can share what’s worked in their own organisations.
Our blended delivery provides a safe space to learn at your own pace and without judgement.
Q 6 – Can you share a story of someone who’s been on a course, and the impact it’s had?
A 6 – One participant told us he’d never been to college or university. He came straight into work and never had the opportunity to study formally. He was the first person in his family to ever take a university course, and it was our Digital Transformation programme.
Something clicked for him. After completing the course, he asked what else he could do. He’s now enrolled on a graduate apprenticeship degree. Another participant has gone on to apply for an MBA. So these short courses aren’t just about skills, they can genuinely spark lifelong learning.
Short courses are powerful…they can change the course of someone’s career.
Q 7 – How does FRIL create the ‘engine’ that drives these skills programmes?
A 7 – Our skills work is tightly linked to the Research and Innovation strands of FRIL. The research teams produce white papers, and we analyse common themes. We attend FRIL’s Innovation Calls, listening to pitches from fintechs proposing solutions to challenges highlighted by industry partners. That’s where you hear the real issues, things like: AI, data, legacy systems, regulatory change.
We also have a skills subgroup with finance industry representatives who act as a sounding board and help us to shape course priorities. Everything is demand-led, grounded in industry conversations, networking and skills gap analysis. We’re supporting a sector that contributes hugely to Scotland’s economy, and we want to get this right.
We’re not just creating courses, we’re listening to what the sector is telling us it needs.
Q 8 – How can what we’re doing here influence learnings across other sectors?
A 8 – While the focus here is financial services, the content isn’t always sector-specific, which means we can swap out case studies to fit different industries. We’re already seeing learners from energy and health joining our courses. Because the pace of change is constant everywhere, the need for digital and AI literacy applies just as much outside financial services.
And the short video-based model means we can keep content fresh. If something changes in AI, which it does daily, we can re-record a section quickly.
Q 9 – While this might be our final question today, this really is just the beginning. What might we expect to come?
A 9 Visibility is a big focus. We’re launching the FRIL Skills Academy, which brings everything together including upskilling, reskilling, executive education, and early-career engagement. It will guide people through learning pathways based on their needs, offer microcredentials, and connect with the student FinTech societies across Strathclyde and Glasgow. There will also be the opportunity to engage with either University to gain support for projects, knowledge transfer partnerships and PhD@Work.
Longer term, we want to work more closely with colleges to support talent pipelines, widen access and create opportunities for people who wouldn’t normally enter higher education. We’re also exploring mentoring programmes, internships guest lectures and masterclasses.
This is about us all embracing the future together. When you engage with the universities through FRIL you’re part of a learning community for the long term.
What next?
If you’d like to find out more about FRIL’s skills programmes, please visit:
- Financial Regulation Innovation Lab (FRIL) – Skills development.
- 10‑credit Online Microcredentials from the University of Glasgow.
The FRIL Skills Academy will be launched at the end of January 2026.
About FRIL
New Year, New Skills: 10‑credit Online Microcredentials from the University of Glasgow
Whether you’re looking to enhance your skills or develop your team, short online courses are a fast, flexible way to upskill and advance your career. The University of Glasgow is offering 10‑credit online microcredentials to help you build in‑demand capabilities quickly, with start dates in January and February 2026. Explore the options below.
Project Management
Start-Date: 26 January 2026
Project management is an essential business tool that is being adopted worldwide. It is also a growing and highly sought-after profession, with the Project Management Institute estimating it to have grown by $6.61 trillion by the end of 2020. In this microcredential course, you will gain a deep understanding of practical project management skills using real-world case studies. You will examine the entire project lifecycle, from feasibility to closure, and explore important topics such as managing people, setting priorities, working to tight deadlines, developing schedules and managing risks.
Intro to Business Analytics
Start-Date: 26 January 2026
The Introduction to Business Analytics: Empowering Decision-Making Through Data course is designed to introduce learners to the concepts, techniques, and methods used to analyse an organisation’s operational performance and enable them to make informed business decisions using business analytics skills. The course will discuss the different sources of data and information necessary for analysis, and how to turn an understanding of business analytics into a competitive advantage. At the end of this course, learners will understand the challenges in sourcing data in today’s internet enabled world, what we can/cannot expect the data/information to tell us, and how we can analyse what we have to the best effect. Learners will also be introduced to the data visualization techniques to maximise the impact of data on decision-making, presentation, stakeholder engagement and stakeholder buy-in.
Business Financial Management
Start-Date: 26 January 2026
This course examines the role of accounting and finance in organisational decision‑making, control and performance management. It offers a broad overview of the function and introduces practical skills for interpreting and using financial information and reports to support these activities.
AI & RegTech in Financial Compliance
Start-Date: February 2026 (TBC)
This course provides a practical approach to understanding and applying Artificial Intelligence (AI) and Regulatory Technology (RegTech) in financial compliance and risk management. It introduces the fundamentals of AI capabilities, the evolution of RegTech, and the regulatory and governance frameworks that shape compliance across banking, fintechs, and the wider financial ecosystem.
ESG (Environmental, Social and Governance) Leadership
Start-Date: February 2026 (TBC)
This course aims to introduce recent graduates and early career professionals in the financial services and financial technology sectors to the areas of ESG policy and compliance, data and analysis requirements, and organisational and strategic opportunities. By focussing on ESG leadership, the course aims to equip learners with the practical knowledge, skills and capabilities to evaluate the strategic positioning of their organisation and to develop an ESG plan for their organisation.
Discount codes
As a valued member of the FinTech Scotland community, and with support from the Financial Regulation Innovation Lab (FRIL), you can use the following discount codes:
- AI & RegTech course: use code ‘FRIL’ at checkout. Standard price £499; FinTech Scotland members pay £349 with this code.
- ESG Leadership microcredential: use code ‘ESGFriends’ at checkout. Standard price £599; FinTech Scotland members pay £399 with this code.
The Delivery and Impact of the FinTech Scotland Cluster in 2025
This report highlights the progress made across the FinTech Scotland Cluster in 2025, a year marked by continued growth and increasing global influence. The cluster has welcomed new firms, attracted higher levels of investment, and seen more businesses scale confidently and trade internationally. Scotland’s fintech SME community has matured significantly, supported by deeper partnerships across industry, academia, and the public sector — reflecting a shared commitment to collaboration as a driver of meaningful progress.
Innovation in practice has also taken a major step forward. The 10-year FinTech Research and Innovation Roadmap is now firmly embedded, with over 40% of recommended actions underway. Central to this has been the award-winning Financial Regulation Innovation Lab, which expanded its scale and earned national recognition for its collaborative, industry-led approach. In 2025, the cluster also launched its second priority innovation environment, The Centre of Excellence in Distributed Ledger Technology, focusing on digital assets, payments, and tokenisation, with digital trust at its core.
These successes reflect the collective effort and commitment across the ecosystem to drive responsible innovation and sustainable economic growth. They provide a powerful platform for the next phase. Thank you to all who have contributed — 2026 promises new opportunities, new collaborations, and continued progress for Scotland’s fintech community.
Together, these environments are enabling pioneering work and helping firms explore and commercialise technologies shaping the future of financial services. National and international engagement has matched this momentum. From strong representation at Money20/20 Europe to productive activity and engagement across North America, Canada, Hong Kong, and wider Asia, Scotland’s international presence has grown, supporting an increasing number of fintech SMEs entering global markets.
Nicola Anderson, Chief Executive at FinTech Scotland, said:
“These successes reflect the collective effort and commitment across the ecosystem to drive responsible innovation and sustainable economic growth. They provide a powerful platform for the next phase. Thank you to all who have contributed—2026 promises new opportunities, new collaborations, and continued progress for Scotland’s fintech community.”
Aleks Tomczyk, Chief Executive at FinTech Scotland, said:
“As I step into the role of Chief Executive in January, I do so with genuine excitement for what lies ahead. The foundations built over the past seven years including in 2025 create a strong foundation for the next phase of growth. Scotland’s fintech community is rich with talent, ambition, creativity, and a collaborative spirit that is widely admired – including internationally. I am energised by the opportunity to contribute further to this vibrant cluster, including its innovators, current and future strategic partners, and supporters in the ecosystem. Together, we will build on the momentum already achieved and shape a successful future in which Scotland continues to lead, influence, and inspire across the rapidly evolving fintech landscape.”
Financial Regulation Innovation Lab (FRIL) Responsible Innovation Case Study: Ask Silver
FRIL: Stopping Scams Before The Payment Goes Through
At FRIL, practical innovation protects people. The Optimising Consumer Outcomes Innovation Call brought together fintechs, regulators, academics and banks to tackle real issues that affect millions of people across the UK.
Ask Silver, co‑founded and led by Alex Somervell, uses AI to stop scams before people lose money. The team’s passion, sparked by personal experience of financial harm, lies in protecting people from financial and emotional harm caused by scammers. Winning one of five funded FRIL innovation awards helped Ask Silver to hire earlier, accelerate product development and launch the Metro Bank Scam Checker sooner – delivering protection to customers sooner than planned.
“Engaging with FRIL gave us access to industry leaders from NatWest to Barclays to Tesco Bank. That insight into their challenges meant we could tailor what we built and get feedback as we built, rather than in isolation.” — says Alex, Co-founder & CEO, Ask Silver.
The Challenge : Protecting People from Scams
Scams and fraud are a growing national problem that harm people’s finances, confidence and wellbeing.
Fraud and scams are among the fastest-growing threats in financial services. In the UK alone, consumers lost £12.4 billion last year, 41% of over 50s in the UK have been scammed in the last five years and fraud accounts for over 40% of all crime.
The FCA’s Consumer Duty raises the standard for firms to protect customers, prevent foreseeable harm and deliver fair value. Many firms find meeting these expectations difficult because of legacy systems and manual processes. Stopping scams quickly – ideally before a payment is made – is a clear, measurable way to protect customers and meet regulatory standards across the UK.
For consumers this means clearer information, fairer treatment and stronger protection so
fewer people lose life savings or suffer emotional harm.
| For Industry | For Consumers |
|---|---|
| Consumer Duty isn’t just regulation, it’s about putting people first. It ensures financial firms act in customers’ best interests, helping prevent harm, exploitation, and financial crime before it happens and ensuring every interaction leads to fair, positive outcomes. | It means being treated with fairness and respect – with products they can trust, clearer information, and stronger safeguards against financial harm or scams. |
FRIL’s Formula for Change
FRIL’s Optimising Consumer Duty Innovation Call set seven practical challenges about improving consumer outcomes using technology and data. By pairing early‑stage fintechs with banks, regulators and academics, FRIL created a fast feedback loop for testing real solutions. Funding support plus direct access to decision‑makers allowed innovators to iterate quickly and scale solutions that benefit us all.
FRIL’s approach shows what’s possible when innovation and regulation work hand in hand. It proves that technology can help financial services not only do better, but be better: fairer, smarter, and more inclusive.
The Case Study :Ask Silver
Ask Silver gives people a fast, easy way to check messages, emails or links for scams. Users send content and receive an instant, human‑centred judgement and guidance so they can decide what to do next.
Ask Silver’s foundation is deeply personal to its founder:
“My dad was scammed, he lost almost £150,000 – most of his life savings. He was vulnerable for a number of reasons. Then three friends in their early 30s, all in tech, were scammed too, losing tens of thousands each. It shows that scams are a problem that affect everyone.” — Alex, Co-founder & CEO, Ask Silver.
Ask Silver’s core product is a scam-checker AI. A user sends a message, email, or website link. The system analyses it and responds with guidance. Ask Silver is delivering real impact so far in stopping scams before payments are made:
- Over 20,000 scam submissions analysed.
- Incidents reported to the National Cyber Security Centre and authorities.
- Many users avoided financial loss and learned how to spot scams.
- Broad media coverage that raised national awareness across BBC, ITV, Telegraph and
- Daily Mail
“Lots of people use it when they’re unsure. They do a quick check with us, get that instant second opinion, and it often leads them to do further research themselves to validate what we’ve said.” — explains Alex.
Ask Silver is live on WhatsApp and planning a roll‑out to web, app and video analysis so more people across the UK can access help in the way they prefer.
Ask Silver stats
| Sector | FinTech/Fraud Prevention |
| Employees | 6 |
| Location | London |
Impact of FRIL: Delivering safer digital finance
FRIL enabled Ask Silver to turn early support and industry links into national impact.
“We won £50,000. That was huge for us at the time as we’d only invested about £100,000 to get this far. That funding allowed us to hire two developers earlier, pushing development forward months sooner than we otherwise could have.” — says Alex.
How FRIL support translated into impact for the UK:
- How FRIL support translated into impact for the UK:
- 2 x developers hired ahead of schedule
- Building tools ahead of schedule (e.g. a Facebook Marketplace scanner)
- Expediting security and feature development
- Gaining validation that supported subsequent fundraising
- Being able to get Ask Silver out there to support more customers, more quickly
“We moved quicker than we would have otherwise. We built features earlier, hired earlier, and engaged with people in banks who we’d have struggled to meet.” — explains Alex.
For industry partners this meant that they could also pro-actively help customers:
“The goal is to ultimately stop scams. We want to be the most consumer- and human-focused anti-scam, anti-fraud product and company available on WhatsApp, web, and app, analysing not just text but video.” — adds Alex.
With FRIL’s connections and credibility, Ask Silver moved faster and gained proof points that helped scale their approach, making protection available to more people across the UK.
“If FRIL hadn’t been there, we’d have delayed hiring, faced less investment and taken longer to get that additional proof point and validation.” — says Alex
Outcomes – Turning Ambition into Action
As a result of the few months of collaboration with FRIL, Ask Silver achieved significant milestones.
- £50,000 FRIL grant secured
- New partnerships formed with major banking institutions
- 2 developer hires accelerated
- Product development accelerated, bringing protection to more people sooner
Case study conclusion
Practical regulation plus focused innovation protects people across the UK. Ask Silver shows how a small, human‑centred AI product can have a national reach: preventing financial loss, educating the public and supporting banks to meet higher consumer protection standards. When regulators, industry and innovators collaborate, technology becomes technology is not just a tool, but a source of safety – and a force for good.
Apply to our Responsible AI innovation call
Download the Ask Silver case study.
New fintech programme aims to help Scotland’s ageing population financially prepare for later life
FinTech Scotland is aiming to help address the growing link between people’s financial situation and their health in later life with the launch of a new initiative that will accelerate innovation through the development of new research, technologies, and services.
The Finance and Health Lab will bring together financial services firms, fintechs, academia, government, health specialists and policy leaders to enhance understanding of the drivers of later life financial vulnerability and to co-design solutions that could improve the financial wellbeing and resilience of people across Scotland. The programme is being enabled by funding from the Scottish Government and delivered in collaboration with the University of Edinburgh and Edinburgh Innovations, its commercialisation service, leveraging their innovation and research networks.
By fostering collaboration amongst partner organisations, the lab will support the ideation of new ventures, prototypes, and pilot projects, strengthening Scotland’s innovation pipeline and competitiveness in the global fintech market. It will also generate research that will shape future service models, product development, and policy that support good financial and health outcomes.
Participating organisations will collaborate on solving a number of challenge areas, with end outcomes potentially including making digital financial services more accessible and supportive for older people, creating personalised tools that help individuals plan for health events in later life, and strengthening financial confidence and decision-making.
The four-month programme will include a National Conference on innovation in finance and health and calls for projects targeting high-priority issues related to later life and financial wellbeing. In addition, participants will have opportunities to showcase new prototypes, understand data, undertake research, produce policy papers, and exchange knowledge through a series of webinars, roundtables, and other platforms.
A range of studies have drawn a direct link between household wealth and the likelihood of poor health in older age. For example, according to the Institute for Fiscal Studies (IFS)(2023–24), 54% of women aged 55–64 in the lowest third of the UK’s wealth distribution reported at least one mobility issue, compared to just 20% in the wealthiest third.
The UK has a longstanding retirement savings gap. Office for National Statistics figures suggest the average pension wealth in the UK for people between the ages of 65 and 74 stands at just under £146,000, equivalent to just over 4.5 years of ‘comfortable’ retirement income by the Pensions and Lifetime Savings Associations’ standards.
Aleks Tomczyk, Chief Executive at FinTech Scotland, said:
“The retirement savings gap is a longstanding challenge in Scotland and across the UK – and it is only going to grow in importance as more people live longer and, therefore, need more money to fund themselves in later life. The Finance and Health Lab will bring together the best minds from across different sectors to find different types of solutions – whether that is policy, research, or technology – and set out a way forward for ensuring people can have a good retirement, minimising the adverse impact that poor health or limited finances can have.”
Dr Andrea Taylor, chief executive officer at Edinburgh Innovations, added:
“Scotland is the ideal test bed for an initiative like the Finance and Health Lab, with a strong fintech ecosystem, globally recognised universities, and a thriving financial services sector. The solutions that emerge from the programme could make a significant difference to people’s lives and further cement our position as a world leader in collaboration and innovation between the public, private, and education sectors.”
A spokesperson for the Scottish Government said:
“Scottish Government committed £5 million this financial year to support the growth of our key innovation clusters as drivers of economic development in areas with huge value potential, including fintech and life sciences. This project, as an important element of a broader suite of cluster development projects, will strengthen cross-cluster collaboration and contribute to the enhancement of innovation and economic growth of these key clusters.”
Read more about the Finance and Health Lab.