
Ethical finance extending the reach
The Scottish Government become signatory (21/22nd September) to UN Principles of Responsible Banking joining a third of the global banking system ($47 trillion worth of assets)
It is impressive that the United Nations has secured so many signatories to the Principles of Ethical Banking.
My plea is that Scotland provides a special “Scottish” addendum and extends the principle of ethical finance to include positive action for the unbanked, near prime financial and credit excluded population in Scotland
In October Global Ethical Finance Initiative acted as pacesetter bringing together UN Multi-faith global power roundtable and a conference dedicated to ethical finance with a global reach.
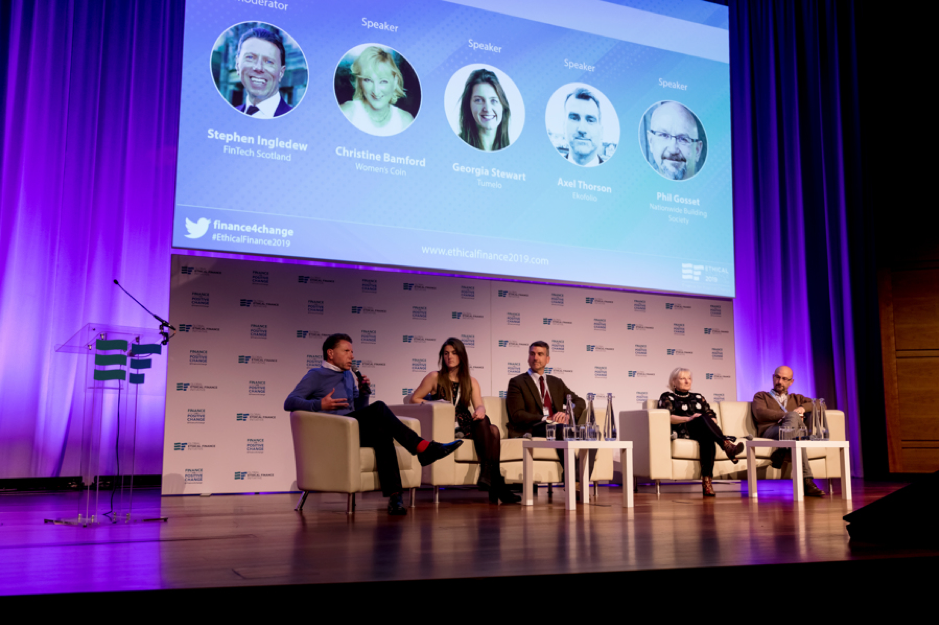
It is encouraging to see leadership from the Church of England and Islamic Bank collaborating to spread and scale faith centred ethical standards in banking Scotland has a long been recognised as a champion of ethical finance. Gremlin Bank (bank for the poor) founded by Mohamed Yunis, more recently Castle Bank Co-operative in Edinburgh support for low-income families and MoneyMatiX community approach to teaching children and families to manage money (and debt) are just a few examples
It is against a backdrop of a long historical tradition in democratic banking serving the poor and rich alike that the vision emerged of a Scottish Investment bank. The vision is nearing reality as the Scottish Investment Bank bill proceeds through parliamentary processes. Central to the bill is a remit to include equality impact assessment ”“ focusing on ethical investment for inclusive growth. Linking the establishment of the Bank to the Equalities Act (2010) is inspired. Ensuring the needs of people who share one or more of the protected characteristics are met is exactly what is needed to provide inclusive growth.
I would ask that we open the debate under the auspices of Fintech Scotland to extend the provision of the Scottish Investment Bank to include fintech mobile innovation as a means of extending the reach to those who are unbanked or “near prime” (not able to access credit due to minor infringement of credit ratings)
I travel with hope in my heart that Scotland will be the first country to aim for zero unbanked. Adopting SDG’s as key drivers of Scottish policy and acknowledging that wellness sits at the heart of an economically vibrant country is pretty good stuff.
As Founder/CEO of Women’s Coin (digital currency of social value) I believe that adoption of ethical financing at Corporate and SME level extending the remit to include digital innovation, tokenisation, and local currencies will accelerate the spread and scale of adoption of SDG’s (UN Strategic Development Goals).
There has never been a more critical time for ethical financing and ethical leadership across all sectors Public, Voluntary, Charitable, Corporates and SME’s
Scotland can really set the pace, the vision and has the know how to create an inclusive society that fosters wellness as the key to economic vitality
Blog written by (Prof) Christine Bamford, Founder/CEO of Women’s Coin
#MorePowertoher #fintechscotland @finance4change @modulr
womenscoin.com
voluntier.co.uk
globalethicalfinance.org
Will the growth in fintech innovation be the solution to tackling one of society’s big issues? Financial exclusion
Homeless, no address, unemployed and no bank account ”“ the future is bleak
2 Million without a bank account. Between 10-14 million “near prime” adults have no access to credit, despite minor blemishes on credit history or can only access credit at high APR 29.9-39.9%
There is an urgent need to open access to financial services for those without an identity and are homeless. or on low-pay income. It isn’t just the homeless but families managing on low incomes where one bill too many pushes them into debt crisis ”¦. into the hands of loan sharks or high APR pay day loans and a continuing spiral of debt. If wellness sits at the heart of Scottish Government policies and values ”“ then we need to recognise the impact of debt, low income, lack of access to credit and insurance as key impact measures on mental wellbeing
Fintech Scotland range of innovative solutions, mobile payment systems, education, blockchain, crypto-currencies, wallets, tokenisation of voluntary work open the opportunity to create an equal and more inclusive society. Mobile friendly approach to Identity secured through biometrics, face recognition, top up payment cards/mobile payments are now able to provide evidence of credit worthiness. This is a modern pathway to a bank account, credit worthiness, access to insurance, credit and a verifiable credit rating.
March 2018 The Mexican Congress approved Fintech Law that aimed to regulate electronic payments, crypto currencies, crowdfunding and open banking. The fintech Law promotes innovation in the financial services industry, stimulates the growth of new business models and reduces entry barriers for Fintech firms. Fintech Law can significantly improve Financial inclusion. Fintech Scotland has taken a non-regulatory approach to supporting financial technology innovation. But the impact possibilities are with us now to work with traditional financial service to provide a integrated solution to financial exclusion. Scotland is on the brink of providing a “world-class” solution to inclusive growth through financial digital solutions creating the link between wellness and economic vitality
Blog written by (Prof) Christine Bamford, Founder/CEO Women’s Coin
Acknowledgement to PWC blog and report
www.womenscoin.com #MorePowertoHer @ChrisBamford12
Crypto currency ATM’s appearing in more Scottish cities
Photo by David McBee from Pexels
Crypto currency ATM’s now in Dundee and Aberdeen
2 Scottish cities, Dundee and Aberdeen, have installed their first ever Bitcoin ATMs.
Alphavend UK, Scotland’s leading Digital Currency ATM operator, has just announced that it had installed Bitcoin ATM machines in Dundee (Nethergate) and Aberdeen (Bridge Street).
Citizens can now buy Bitcoin, without having to make long journeys to cities such as Glasgow or Edinburgh and in a way that’s easier than easier than before by simply exchanging cash for the famous cryptocoins.
Alphavend has planned to instal more machines in the UK and is growing rapidly to keep pace with the growing interest and demand which has never been higher.
The high demand can be explained by Bitcoin being chosen more and more as a cost-effective way of sending money around the world.
The challenges of scaling up and winning bigger business ”“ and how Proactis can help
Winning new business is difficult. Often it’s most difficult for new and emerging companies to challenge the established order, especially if they’re doing things in a different way. As businesses expand and develop, they begin to examine different avenues, moving away from ad-hoc smaller pieces of work to looking at more formal access routes to substantial contracts.
Here we arrive at the wonderful world of bidding, proposals and tendering (you’ll see these terms being used interchangeably, but don’t worry they all mean the same). As potential contract sizes get larger, the demands placed on prospective bidders become ever more arduous and detailed, formal submissions are required for public and private sector buyers alike.
As you might expect, larger companies have more resources to dedicate to business development and specifically to bidding for work. A recent survey of bid professionals showed just 20% worked in organisations of less than 100 employees and only 12% were the sole responsible resource in the organisation*.
Unfortunately for smaller organisations, research has repeatedly shown a direct correlation between the level of resource employed in preparing proposals and success rates. The good news for developing organisations is that there are some relatively easy steps to take to improve proposals. A recent industry study shows that nearly half of all procurement professionals believe suppliers are letting themselves down with their proposals and that they are of poor quality. With the general standard being low, smart thinking and some effort can make a big difference.
If you are at the stage where you are or soon will be submitting proposals as part of your business development strategy then we would like to support you. As a commitment to helping exciting fellow Scottish businesses within the Fintech community, we are offering a day of expert bid support to a limited number of organisations completely free of charge.
This support could be analysis of current bid strategy, support with a live bid or a review of a past proposal.
To discuss your free expert support, contact Andrew Watson, Bid Consultancy and Training Manager at Proactis Tenders Limited – Andrew.Watson@proactis.com.
Proactis Tenders Limited is one of the UK’s leading procurement companies. Its team of specialists has extensive knowledge and considerable experience in providing a range of eProcurement systems and services to buyers in the public sector. It also offers a range of services to private companies from all sectors throughout Europe who are seeking new business opportunities.
*APMP UK Compensation Report 2019
It’s worse than that”¦ Jim
Anthony Rafferty, Managing Director, Origo says recent research into integration between systems in financial adviser firms’ back-office systems reveals a worrying disconnect eating into time, resource and profits of businesses
Origo recently commissioned in-depth research into the integration between systems in the back-offices of financial advice firms, and how this affected the efficiencies and profitability of those firms.
The research was carried out independently by the lang cat, a specialist financial services consultancy based in Edinburgh, and combined hours spent in financial advice firms around the UK mapping processes and analysing how they use the systems they have in place, as well as conducting online research with another 116 financial advice firms.
The conclusion is best summed up by Mark Polson, the MD of the lang cat, who was heavily involved in the research. He says: “We knew things weren’t great before we set out to conduct this research. But even so, we were struck by the impact of these inefficiencies on adviser back offices. Even where integrations do exist, firms aren’t trusting them or using them ”“ with good reason in some cases.”
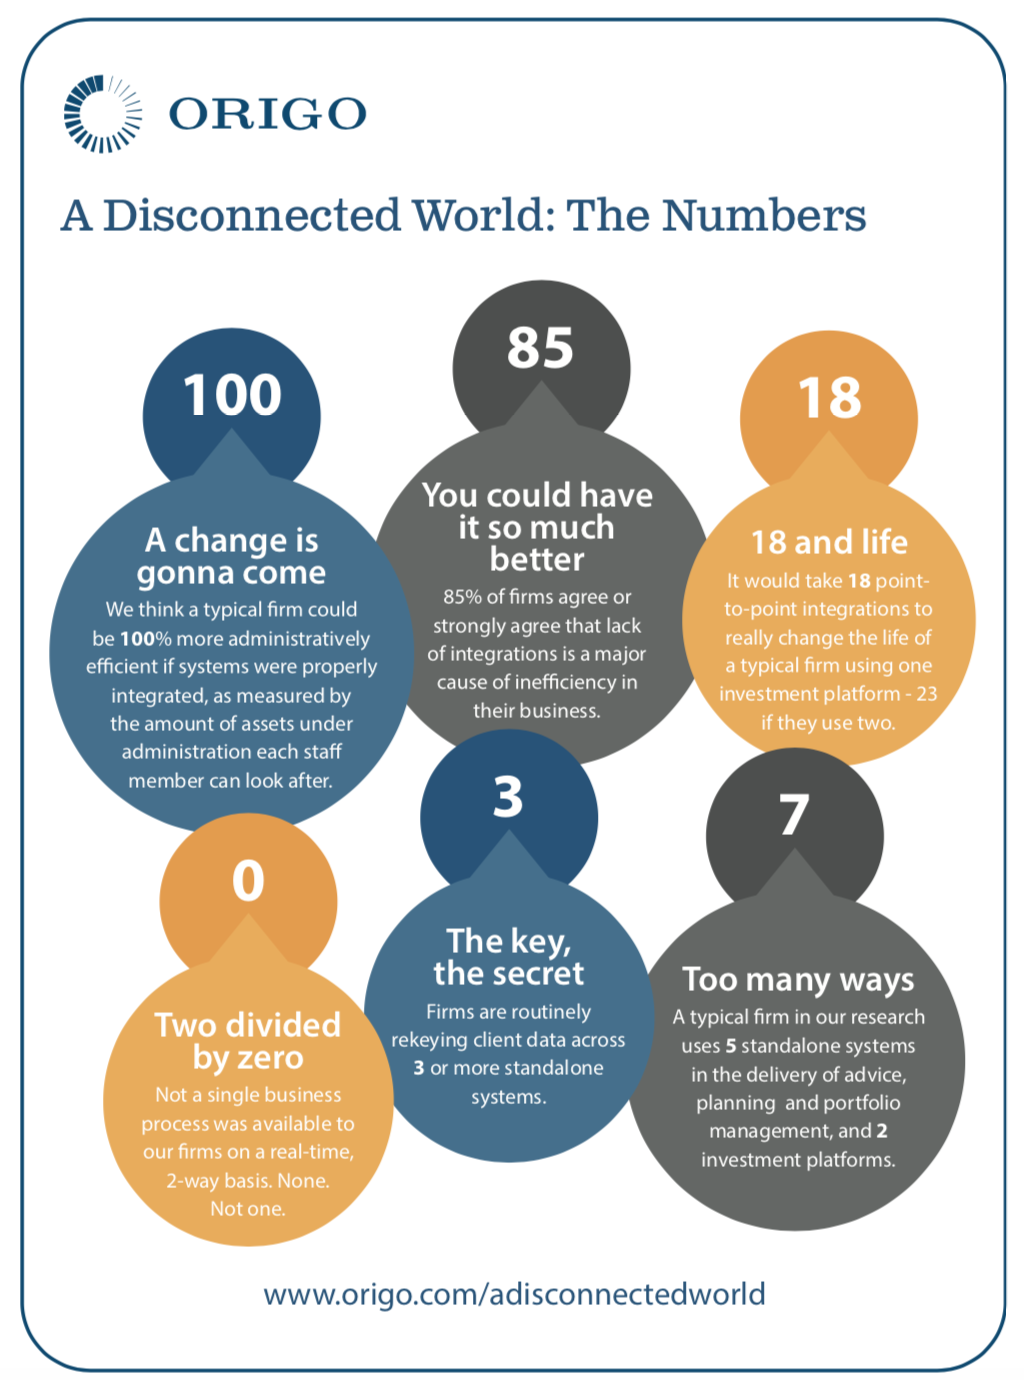
From closely studying firms’ processes, the research estimates that in a typical financial advice business, staff could be up to 100% more efficient, dealing with twice the assets under administration they currently manage, if the systems they used were properly integrated with one another. In other words, staff could potentially be dealing with up to twice the number of fee paying clients than they are at the moment.
That is both a shocking state of affairs and also one of opportunity ”“ not least for financial advice firms.
To explain what we found: Firms involved in the study on average used five standalone systems in the process of giving advice, building investment and savings portfolios and managing clients; seven when platforms (transaction and administration services) were added; 10 with the addition of more general systems like accounting and office software.
It showed that due to a lack of integration between systems, and trust in those systems, firms are having to plough time and money into otherwise unnecessary manual input and reconciliation. In a typical new business journey, for example, client details were being keyed into systems at least three times!
Key facts from the research can be found on the accompanying infographic.
Currently ”“ and to be fair, despite sterling work by some of the players in the market ”“ advice firms do not benefit from a level of integration that is of real use to them. Integrations are typically point-to-point, with one provider integrating with another for specific purposes, for example for portfolio valuations.
They are also driven by business case, with platforms, CRMs and other system providers naturally prioritising integrations that will bring in higher levels of returns.
On a practical level and worryingly, even where integrations exist, adviser firms said that the lack of consistent and quality data meant they distrusted the output the systems are delivering, the result of which was that they had reverted to inefficient, costly and potentially risk inducing manual processes, because it was a process over which they have more control.
Typically there are 23 point-to-point integrations required within a firm using two investment and savings platforms, without factoring in any systems for protection and mortgage services and general office systems. On a point-to-point basis, that level of integration is never going to happen.
But there is a solution. We identified that if there was a centralised hub, into which platforms, CRMs and adviser software systems and tools could integrate once and then connect to every other player in the market who was also connected to the hub, and which also dealt with making and maintaining the connections, the benefit to the industry could be huge ”“ in particular to the financial adviser firms.
Using a centralised hub would mean any provider new or established could connect with any other provider on the hub, for services pertinent to their operations, no matter the volume of business.
In this way, a centralised integration capability would significantly improve the market’s connectivity, helping advice firms to improve their efficiencies, their profitability and enabling them to deliver faster and better service to their clients, whilst potentially boosting business across the board.
Hence, for the past couple of years we have been building the Origo Integration Hub to help provide that solution.
From a business perspective, for systems and services providers, this hub-and-spoke approach to integration does away with the need for case-by-case decisions and resource restraints incumbent of the point-to-point integration method. Linking to a hub incurs one set of integration costs instead of many, and significantly reduces resource and IT costs, which platforms and system suppliers can better apply elsewhere in their business.
Importantly, it provides the opportunity for all software and service companies, including smaller companies and new entrants, to easily connect with new trading partners if they wish. Also, it enables adviser firms to use the software or service that best suits their business set-up.
Currently, the Integration Hub has 19 companies including some of the big names in investment and savings signed to it, with others in the pipeline.
From a top down perspective it seems illogical that in the 21st century systems do not talk to one another in an efficient manner. However, this is a legacy issue which Origo with its remit to help improve the efficiencies and cost effectiveness of the industry and deliver better outcomes for consumers, is in a position to help resolve.
Read more about Origo here
Fortnightly FinTech Fuse ”“ Awesome FinTech Atmosphere!!
An awesome August atmosphere has been pervasive across Scotland and the fintech innovation activity, in its many guises, has contributed to this over recent weeks.
Since returning from a few days in the beautiful Mediterranean sun, there has been no respite in the breadth and depth of fintech initiatives which are creating this can do entrepreneurship.
The fintech community gathering at one of the new innovation hubs, The Green Room in Edinburgh, where a good number of us came together last Thursday is a great example.
Entrepreneur Atmosphere
The gathering was a mix of fintech entrepreneurs from across Scotland along with some seasoned investors, coming together to try a few glasses of summer wine.
Delighted that Alistair Forbes from Mercia and Ron Robson from Tavistock Group could join us and a huge thank you to Dag Lee and Sarah Ronald for being terrific hosts at one of Scotland’s newest fintech epicentres’.
We look forward to repeating the gathering during September’s fintech festival, watch this space.
The week before there was another wonderful atmosphere at the Virgin Start Up event in Glasgow which attracted entrepreneurs from far and wide across the country.
Terrific to share the platform with the inspiring Phil Grady of Castlight Financial and Loral Quinn of Sustainably, who brilliantly shared their experiences with entrepreneurs embarking on the innovation journey.
A massive thank you to Andy Fishburn, Alice Mulrooney and the Virgin Start Up team for their leadership as well as Stephen Pearson from Virgin Money for making all this happen.
We are looking to repeat a similar event with David Duffy, Stephen and the CYBG Virgin Money team on 12thSeptember in Edinburgh with the Scotland’s fintech community.
There are many other exciting activities being planned to build the entrepreneurial atmosphere, such as by James Varga, the awesome leader of The ID Co, in embracing the open banking opportunities.
Great to meet up with James a couple of weeks ago to discuss how we support the collaboration with fintech entrepreneurs across the ecosystem.
Similarly, terrific to meet up with Stuart Lunn and Darren Cairns from the market leading firm Lending Crowd and put the world to rights over a few glasses back in the Green Room in Edinburgh.
Thank you Stuart and Darren for your ongoing valuable insights and feedback, looking forward to building on this last eighteen months of Fintech Scotland into 2020 with you.
The awesome atmosphere is not confined to the evenings and it was great to meet up with long standing colleague and one of the very original fintech leaders (for over 30 year) Ian Mckenna for an early morning breakfast.
We were joined by new chief executive Billy Burnside of Criterion Tec, who we are delighted to welcome into the FinTech Scotland community as we lay down the tracks’ for a new data driven innovation future.
In between the Edinburgh fringe festival activity, it was terrific to meet up with Raymond O’Hare last week to share some of these developments and discuss collaboration opportunities.
Very excited about welcoming the Raymond and the Exception team to the FinTech Scotland community in the coming months.
The entrepreneurial atmosphere is also being fueled by a global energy and it is really exciting to meet with successful entrepreneurs bringing their firms to Scotland
Really enjoyed catching up with Gopal Hariharan of Black Arrow in Glasgow and very excited about this fintech enterprise being set up in Scotland
Then it was also fabulous to meet up with Paul Kiernan to hear about the fast developing plans for the innovative Decision Point enterprise in Scotland.
Looking forward to connecting Gopal and Paul into the community and ecosystem across Scotland and building the collaboration opportunities
Collaboration Atmosphere
This last few weeks I have been really enthused about the flourishing collaboration atmosphere and the opportunities to bring together the fintech community with innovative large enterprises.
For example, great to progress the development of opportunities with Sam Bedford, Gary McLellan and the CYBG Virgin Money team as they further extend their market leading innovation initiatives
Similarly, excited to be working with Ali Law, Julian Reichert, Ricky McKinney and the rest of the team at Royal London as they revolutionize long term savings sector.
Terrific also to engage with the Barclays team, Danielle Sheerin, Sonal Lakhani, Stuart Brown and Alex Ball to explore collaboration initiatives, including the Tech Stars programme during the FinTech Festival.
Delighted to be taking forward the collaboration with Aberdeen Standard Investments and working with Mario Cugini, David Scott, Geoff Aberdein and Ruari Grant to explore fintech collaboration in the asset management sector.
The retail banking sector has already demonstrated the value of closer fintech collaboration and my meetings with the inspiring Kristen Bennie of RBS highlight numerous good examples of this.
Sharing the examples of collaboration across the broader financial sector provides enormous opportunity to build the fintech innovation cluster in Scotland.
In this respect, the last few weeks has seen constructive conversation with Asif Abdullah, Cyndi Shettle and Martin Little of Franklin Templeton from the investment sector and David Skinn from the insurance sector.
It was also valuable to catch up with Tara Foley of Bank of Scotland to consider how we work more closely to progress specific initiatives on consumer engagement working with the fintech community.
On this note, thrilled to see the Chemistry’ Fintech Accelerator go live last week working with strategic partner Sopra Steria and the Edinburgh Innovations team of University of Edinburgh.
Terrific leadership by Kerry Nicolaides and Mingaile Vaisnoraite, exciting to be working with banks and fintech firms on this.
Brilliant to also talk through with Mags Moore of Sopra Steria on how we can develop the fintech collaboration across Government with similar initiatives to improve citizen and consumer outcomes
The engagement of consumers in fintech is a growing development and I was delighted to join Dave Shaw and the Tesco Bank team in sharing how they are taking a human design centred approach to customer engagement.
Fantastic to see the work with Chris Speed and team of University of Edinburgh come alive, all very much in line with the collaboration co-design atmosphere, and in a super festival setting at the University.
Another example of collaboration that serves social purpose is the great work lead by Nicola with the launch of the fintech customer panel announced today. This initiative will bring the innovation from the fintech firms together with consumer representative bodies to tackle societal and economical issues. You can read more about it here.
Festival Atmosphere
Talking of festivals, we have been overwhelmed with the support for the FinTech Festival in September, amazing engagement from so many people for the three weeks of activities.
Huge thanks to the wonderful Rory Archibald of Visit Scotland and Karen Craib of Scottish Enterprise who have worked tirelessly with Mickael to bring it all alive.
It was brilliant to meet up with Hazel Gibbens of Tech Nation recently to share plans for the Festival, I’m hoping Hazel will be joining me on the stage for a few events to highlight the support for innovative enterprises across Scotland.
It was super to talk about the growing festival atmosphere across the fintech community at my recent catch up with Huw Martin and Joseph Apted of Head Resourcing recently, very much appreciate their ongoing valuable support for fintech leaders.
Similarly, in meeting up with Graeme Jones of SFE to talk through the plans for the next cross industry and Government meeting, FiSAB, which will take place in the middle of the Festival programme.
It is very apt that the first festival showcase event will take place in Glasgow at the University of Strathclyde with the FinTech Future conference.
University of Strathclyde has led the way in both fintech knowledge and skills development on the global stage and I am hugely excited about the broader development of the fintech cluster as part of the Glasgow Innovation District
Fantastic to be working with Eleanor Shaw, Martin Hughes, Mick McHugh, Emma Stephen and the team at the University as we progress the strategic opportunities
Very much looking forward to taking forward the fintech engagement initiatives being led by Daniel Broby, Devraj Basu, George Wright and John Quigley amongst others.
Fintech and broader tech skills are crucial to the further success and progress of the cluster and economy, in this respect it has been a privilege to be working with the awesome teams at Skills Development Scotland and IBM.
A couple of weeks ago it was an excellent workshop session on developing the skills for young people across Scotland with the motivational Damien Yates, Neville Prentice and SDS team along with the inspiring Gary Kildare, Charlotte Lysohir, Nicky Cooper, Dominic Nolan, Mairi Cairney, Bill Hughes of IBM.
Many thanks to the magnificent Michael Young and Georgia Boyle and the MBN Solutions team for being wonderful hosts for the meet up with the senior IBM team from all sides of the Atlantic the day before.
Once again, the MBN Solutions team are hosting a range of terrific fintech meet ups as part of the festival and their valuable ongoing leadership makes such a positive difference across the community.
Running Atmosphere
The Kirkcaldy half marathon a couple of Sundays ago was probably the best running race atmosphere I’ve experienced from a local community ever, just amazing!
The Kingdom of Fife community turned out in huge numbers for a very special race and it was a privilege to savour the magnificent support throughout the 13.1 miles.
Thank you so much Kirkcaldy, I’m still buzzing from the race even now and I think the buzz will carry on to the Fife Fintech Festival event on 17thSeptember.
The half marathon was part of my training leading up to the Loch Ness Marathon in October and proceeded another half marathon the week before at Bathgate and a rural midweek eight mile race in the Fife countryside around Ceres.
Next up is the Kilmacolm half marathon as part of a 23 mile training run next Sunday followed by the Scottish Half marathon in east Lothian, all before the trip to Inverness for the marathon in early October.The next few weeks will be the real test on whether I can get back to my marathon racing best although the atmosphere from the forthcoming fintech festival in September should propel me one way or another!! Until next time!
Autorek and the Automation Revolution
AutoRek have just announced that they had partnered with Worldwide Business Research (WBR) to generate an industry report. The report will be focusing the state of automation and data management within the financial services sector.
The survey includes feedback from 100 individuals within the operations, IT, business change, finance and data management business functions. They were asked how automation will affect the financial services industry in the next 5-10 years.
Key findings include:
- The majority of those interviewed are implementing blockchain, semantic data management, machine learning and automation
- Respondents think that AI is likely to impact product development and innovation the most.
- 46% of respondents are looking for new technologies to assist data governance.
Investing in the Automation Revolution’ will launch at Sibos London between 23rd”“ 26thSeptember.
Scotland’s fintechs can unlock the power of open banking
There are over one hundred fintech companies thriving in Scotland’s fintech community with a range of new start-ups, existing firms developing their fintech offers and tech-driven firms re-locating north of the border. The launch of open banking last year has played a key role in fuelling the growth of this sector and the UK as a whole is now recognised as a world leader in open banking innovation.
So far, much progress in open banking has been made in the small business environment where innovative products and services are already in the marketplace such as tools for monitoring cash flow and accessing finance. An important contribution to this innovation was the first Open Up Challenge in 2017 and 2018 ”“ spearheaded by the Competition and Markets Authority (CMA) and run independently by Nesta Challenges. The Challenge was part of the CMA’s package of measures introduced to stimulate competition in the financial sector and help small businesses save time and money, find better services, reduce stress and discover the intelligence in their financial data. Winners included fast-growing fintech brands such as Swoop, Funding Options and Coconut whose products are frequently used by freelancers and small businesses across Scotland. However, as important as it is, the small business space is just the start of the open banking revolution.
When we consider the consumer market, while there are products that are already in use it’s fair to say that take-up has not yet been widespread – especially in light of research showing UK consumers stand to gain £12bn a year from open banking-enabled services[i]. Awareness of open banking is still low, with new research from Nesta Challenges showing that 55% of people in Scotland have not heard of it.
On the other hand, 46% of Scottish people say that they want to feel more in control of their finances and 33% want personalised information and guidance to help them manage their finances. For people in Scotland the two biggest benefits of using an open banking enabled product are seen to be: saving money and finding better deals. These findings present big opportunities for those fintech companies and start-ups in Scotland developing open banking-enabled innovations for consumers.
That’s why Nesta Challenges, in partnership with Open Banking Ltd, has launched the Open Up Challenge 2020 – a £1.5m prize fund to encourage fintech innovators to create solutions that will help people to make more of their money.
With Open Up 2020 we want to attract breakthrough innovations designed to support hundreds of thousands of people ”“ particularly the most vulnerable. We’re looking for fintech innovators that can unlock open banking’s potential to change the way that the UK manages its money ”“ especially for the 15.2 million who regularly run out of money each month.
Open banking represents a genuinely new way of empowering people with their data ”“ it is a key milestone on the journey to a digital economy, and the Open Up Challenge has an important part to play in encouraging people to make their data work for them. Open Up 2020 will not only help people better manage their money and take control of their data, but it will also support Scotland’s growing and thriving fintech sector by fast-tracking innovative new products and services. Applications for Open Up 2020 are open until October 2nd2019 and guidance on how to apply can be found at https://openup.challenges.org/apply/. In addition, the Open Up 2020 team will be holding office hours at Codebase, Edinburgh on Thursday 12thSeptember ”“ book your slot hereto benefit from tailored application support from the Open Up Entrepreneur-in-Residence Sarah Tierney.
[i]Consumer Priorities for Open Banking 2019
5 tips for transitioning from the finance sector to FinTech
Looking to move into the Fintech sector but not sure how relevant your background in finance is? Put simply, it is. Here, Chris Stappard, the Managing Director at Edward Reed Recruitmentshares his top tips for transitioning into this new industry.
FinTech is redefining the landscape, giving us all new innovative ways of managing our money. But, it’s not just the customers of these companies that are benefitting, but also the job market. While traditional financial institutions are automating their processes and using artificial intelligence to become more efficient, the FinTech sector is thriving and creating more job opportunities.
For many people, this means that they’re unsure of their future within traditional finance companies and instead are considering making the switch to FinTech. But, with this sector focussing on technology, how do you know if you’re a suitable candidate for roles in FinTech? Here, I will be sharing some of my top tips to help you seamlessly transition between finance and FinTech.
Identify your transferable skills
Though it may seem like new technology is changing the way we approach finance, don’t let this put you off from applying for FinTech jobs. There are plenty of useful skills you’ll already have picked up from your current job that will be key for success in this new field. For example, being able to efficiently crunch numbers and get your head around complex data to make a business decision is particularly valuable in FinTech.
Similarly, being equipped with regulatory knowledge about the financial industry, and more importantly what GDPR is and why it’s important, will also be expected by any FinTech company you apply to. Not only does this ensure you’re protecting their customer base, but also the company’s reputation.
Decide which roles are most suitable for you
While you’ll already have taken the time to note down your transferable skills, you’ll also need to think about your strengths and weaknesses. This can include looking at your hard skills, like language, numeracy and your ability to communicate, which are key to any job, as well as more finance-based skills. FinTech roles are very varied and can specialise in anything from financial analysis to accounting and risk management, so knowing which sub-sector your skillset corresponds with best will be crucial.
You’ll also need to think about where you should apply. The speed at which the sector is expanding means that there are plenty of companies you could get involved with, however, be aware that not all of them are likely to last. A start-up FinTech firm can present plenty of opportunities for you but are more likely to fail than established companies.
If you’re looking for more job security, it’s worth knowing that plenty of traditional financial institutions are also looking to remain competitive by improving their FinTech focus. Just remember that there is never guaranteed success, even for the biggest of financial firms.
Go the extra mile with technology training
While some skills from a financial background will be enough to help you get your foot in the door, it’s always worth knowing as much as you can about the sector you’re moving into. You don’t necessarily need expert-level knowledge, but, having a simple understanding of core aspects will pay off.
There are plenty of training providers that offer courses in data and business analytics, so, if you’ve identified these as your weaker points, you can work on them. Not only will it impress future employers in interviews, but it’ll also show your willingness to learn about the industry and make it easier to adapt to any new role.
Network with like-minded people
Networking is one of the most powerful tools for boosting your career, so it’ll pay to look up interesting FinTech-related events that you can attend. At these, you can make inroads with new connections, who may be able to help you now or in the future. You might even be able to use these events to find somebody to mentor you through the job search and application process. If you get too carried away chatting to get essential contact details, don’t be afraid to reach out through LinkedIn.
It’ll also be worth reaching out to old finance friends and colleagues to catch up with where they’re at. Who knows, maybe they’ll own their own FinTech start-up now or know a company with a vacancy that sounds perfect for you!
Perfect your personal sales pitch
It’s not always a given that the person interviewing you for your potential FinTech role will have as much experience or knowledge as you do about finance. And, while it’s a must to be able to talk about these things with confidence, interviewers will also be looking for someone who has shown initiative and enthusiasm about joining the business.
Taking a look at the job description and thinking of an example for each of the necessary skills can ensure you tick all of the boxes in the interview. Plus, suggesting any ideas you think they could incorporate into their business model or services could make you stand out ”” just don’t give away all of your great ideas at once!
Your background in finance can put you in good stead for a career in FinTech. Follow my top five tips to set yourself apart from other candidates and use your existing skills to impress the interviewer for future roles.
Interview with Revolut – Challenger bank set to disrupt business banking
We spoke with James Gibson, Senior Product Owner at Revolut to speak about how the company is looking at disrupting the business banking sector.
We hear a lot about disruption in banking but that’s very often for consumers, do you expect the same happening to Business Banking?
Consumer experience has always been at the centre of disruption and as long as there are innovations or improvements that can be made to that in any industry – they will continue to be disrupted. Business banking is no different. Rubbish exchange rates, hidden fees and lengthy on-boarding times are issues we’ve already been able to solve and now we’re working on delivering innovative solutions to our business customers.
How would you rate the state of business banking at the moment in terms of experience and offering?
Products and services can always be better. What we can comment on is the surge of start-ups in the space – that just means there’s so much work to be done. Everyone is working to solve fundamental problems and deliver the basic solutions but soon we’ll see start-ups experiment with niche features and thats what will be exciting to watch.
How do you hope to change this at Revolut?
We’ve already impacted thousands of businesses across Europe by helping them with massive savings on exchange rates and avoiding any hidden or confusing fees. We’re now looking at building a one stop shop so that businesses can do almost everything in one place. For example, expense management with even more accounting tools to add to Xero and FreeAgent and even looking into launching acquiring in the near future.
Are there other examples around the world of companies who got it right according to you?
There are a lot of start-ups around the world disrupting industries and changing the way businesses and consumers think about product experiences. Companies like Uber, AirBnB, Apple have customer experience at the core of what they do and that’s a philosophy that we share as well. Of course, it is difficult to pin-point any companies that are doing everything perfectly which is great because it shows that even these established companies recognise the importance of continued progression and disrupting their own processes.
What does the future look like for business banking?
Bright and with lots of Revolut cards! Our vision remains similar to the quest we embarked on 4 years ago: ease of use for clients, automated processes where possible, fair and transparent pricing and technological developments that directly impact the finances of any business in any industry. We’ve done well on all of these points so far but we have much more to do!
What’s the next functionality you’re exciting about pushing to the market?
We’re super excited about the work that we’re doing around acquiring and we’re hopefully going to make some major announcements in the next year. We also listen closely to the feedback of our existing 100k+ businesses clients and it’s clear that UI and even more control over company spending are key topics so we will have some exciting updates on this area soon!