
Opening Data Responsibly
Kent Mackenzie leads Deloitte’s Risk Analytics practice and has spent over 12 years in a range of financial services roles. With a passion for FinTech, data and advanced analytics, Kent has worked with local, national and international clients to develop tech and data solutions to manage financial crime, regulatory compliance, credit risk, and collections & recoveries.
“Data, quite frankly, should be considered as the lifeblood of any form of innovation and technological development,” says Mackenzie. “It’s very pertinent in our industry, financial services, that all products and advice for consumers require a hefty analysis of data; either on a personal level based on likes, preferences, hopes, dreams and desires, or with an overlay on those products of the broader population’s needs.”
In Mackenzie’s mind, having open access to data is what really helps innovation advance quickly, specifically in financial services, because it helps provide specific information on the types of products and services that can be offered. “If we can democratise data in this space, we can open up financial services to a variety of communities that perhaps haven’t in the past had the privilege of a financial product or service,” he explains. “It can help us to educate those that perhaps need a bit more help in understanding financial products.”
Before we get to this point, however, we need to rectify the opposing forces between the desire and ambition from organisations, regulators and innovators, to democratise data and create an open playing field, versus an anxiety around data privacy, respect of data and regulatory access to data. Mackenzie maintains that while we recognise the need to provide access, we need to do so respectfully and within the confines of respecting privacy, data integrity and bias. Over the past five years, he believes regulators within the UK have been doing a great job of opening up safe sandboxes, and credits the open data movements that have created anonymised data that is meaningful and can be accessed safely. He underscores that all this needs to be done in a non-competitive manner. “There’s a higher calling here to create these types of safe spaces to play,” says Mackenzie.
He believes the next incarnation of open data is eventually about providing a complete life-view of how one’s finances may be structured and how people could be guided and remain financially literate along their journey. This chain of events will prompt major innovations within the traditional financial services sphere. For example, real estate businesses can provide a number of add-on services around things such as affordability, insurance and tax standing.
The most important guiding principle of open finance, Mackenzie maintains, is the huge opportunity to level the playing field. “Fundamentally, financial services are a basic human right, and there are some staggering facts whereby large parts of the population do not have access to that basic human right,” he emphasises. “Also, I think that the ability to blend finance into our everyday lives is really exciting. It will create a really good opportunity to have financial services writ large.”
Unlocking Trust: Digital Wallets for Identity Verification and Asset Transfer
As part of Scotland FinTech Festival, the “Crypto FinTech Seminar” will outline some key areas of knowledge and innovation related to the usage of cryptography, blockchain, zero trust and quantum computers. We took some time to chat to Professor Bill Buchanan, who will be co-presenting the seminar along with Dr Mwarwan Abubakar, about the current trends and evolution of the digital assets space.
The fact that we still use our scribbled signatures and hard-copy contracts as a core method of proving our identity within high-value and high-risk transactions still amazes Bill Buchanan, Professor of Applied Cryptography at Edinburgh Napier University. Especially as these acts are often performed through the use of mainly untrusted communication systems such as electronic mail. “We still live very much with a paper-based approach to the ownership and the transfer of assets, and often see them poorly managed,” explains Buchanan. “Digital wallets can help solve this.”
Going forward, it is likely there will be a rise in the use of digital wallets, which can be used to transfer assets and – importantly – define ownership. A private key in a digital wallet can not only prove our identities, but also link to our ownership of assets, store our important digitally signed identity documents (such as our driving licence), and provide a way for us to digitally sign things. Improved methods of providing our identity will also likely include biometrics, hard tokens or our location information. At the core of this is public key encryption, which digitally transfers assets without the need for any network connection, and is a central component to moving into a more trusted digital world.
Nonetheless, a cautious equilibrium needs to be maintained between the rights of privacy and the requirements of compliance, such as with money laundering checks and fraud detection. While there are methods used in cryptocurrency that support a full anonymisation of asset transfers, it is unlikely that these would be allowed within a regulatory framework. “There are ways, though, to strike a balance between these things and instil strong levels of trust in transactions by using trusted financial organisations,” proffered Buchanan. “It is thus likely that we will see the rise of proxy entities (agents legally authorised to act on behalf of another party), who will shield the identities of those who are transferring assets, yet the transactions can still be fully checked.”
Going forward, regulation will be fundamental for providing trust, and licences will be needed to perform fully-auditable transactions. Overall, the key aim of the infrastructure behind digital assets must be for citizens to have a stronger integration with public services to move to a properly integrated digital world. “Unfortunately, without a strong identity infrastructure, we will struggle to scale our world into a more trusted one,” concluded Buchanan. “The EU, for example, now wants to roll out an e-ID digital identity for every European citizen, which will allow for closer economic and societal links across EU countries. This will support the freedom of movement across Europe and provide closer economic integration across borders.”
Embedded Payments: Paving the way for the future of business
Payments have always been the leading area of innovation for fintech companies in Scotland utilising open banking and embedded payments making it faster and more convenient to pay and transfer money both locally and globally. That is why Payments & Transactions was designated as one of the four key strategic priority themes of FinTech Scotland’s FinTech Research & Innovation Roadmap 2021-31.
Nick Adams, Director and Payments Experience Specialist at Modulr, spoke with us about how embedded account-to-account payments are enhancing the ability to seamlessly integrate payments into everyday experiences, enabling customers and businesses to make purchases without the need to input bank details, credit card or debit card information. Modulr is leading this category of B2B embedded payments and is registered as an Electronic Money Institution (EMI), enabling businesses to create accounts, control and access, receive and make payments, update systems and customers via webhooks – all on-demand through software.
“When people think about digital payments for businesses and the economy via ecommerce or other platforms they tend to think of card payment players like Checkout.com, Stripe, Braintree (part of PayPal) and then PayPal itself,” explains Adams. “Embedded payments is fundamentally different as it enables businesses to fully embed and control real-time money movements in and out of their businesses through software. The brands I mentioned, among many others, are third-party managed service providers that sit outside their clients’ business. They are focused on the checkout experience, but there’s a whole other area of business payments that has not been brought into the 21stcentury.”
By bringing embedded payments into their platforms, companies can offer their customers custom experiences that align much more to today’s consumer expectations, who want immediate notifications and frictionless payments like Uber and Amazon. Those businesses also want certainty in their Treasury functions on how much money they actually have at any point in time – a real-time view of their cash position. “Modulr enables hundreds of enterprise customers and thousands of SMEs to process and reconcile large volumes of payments automatically and in real-time rather than using antiquated batch processes,” describes Adams. “It’s providing access to real-time payments for all sizes of every business, from enterprises through to SMEs, to simply plug in through the same API and get the same control and visibility. This instils trust in both buyers and sellers, because they can actually see what’s happening in a transaction, instantaneously.”
From a personal perspective, Adams now considers himself a “payments guy” who, having worked for large global payments businesses, has now transferred to a Scottish fintech scale-up. His advice for those thinking of making a similar move:
- Don’t feel you have to be global from day one; payments is a globally fragmented industry and focusing on a country or region with harmonised payments regulation and processes makes sense. We’ve seen too many global-ambition payments startups fail due to over-stretch
- Promote the exciting opportunities of working in fintech to the talent derived from Scotland’s more traditional financial services businesses
- Be flexible with your teams, but spend as much time as you can together physically in the same space to create energy and move much more quickly.
Adams concludes, “What excited me about moving from a big corporate, to an early-stage scale-up was the ferocious speed and need to pivot constantly. It’s a very invigorating environment. Generally speaking, the people that are in it, I think are having great fun. I’d recommend this to anyone.”
How To Capitalise On The Crypto Boom? This New NFT-Funded Eco-Glamping Resort
If there was ever a time to Look seriously at digital currency, it’s now. Today’s crypto market is worth $1.21 trillion,* and Bitcoin has experienced an 85%** surge since this time last year. Meanwhile, NFTs are bringing the potential of profitability to the masses. Well, now “new wave thrill-seekers” can use NFT’s to gain exclusive access to a one-of-a-kind eco-glamping site featuring an Augmented Reality (AR) gaming experience just 20 minutes from Edinburgh.
Those who are interested in NFTs, but fancy something a little different from their investment, should discover Mythtopia – a unique travel experience only available to NFT holders.
Mythtopia combines ecotourism with an AR gaming experience centred around Celtic mythology in stunning Scottish woodland. Guests can stay in one of the 150 low-carbon impact geometric domes and take part in Mythtopia Legends,’ an augmented reality video game following the tales of Celtic folklore.
By owning a Myths NFT (Myths), investors can stay up to three nights per year at Mythtopia Resort alongside friends and family (up to 4 people per dome). Or, they can stake their NFTs and earn extra cash from their allocated nights.
Founder of Mythtopia, Oliver Pyle-Santini, said: “Our NFT’s enable us to build this amazing resort of Mythtopia! The AR game Legends’ is a unique activity, but totally optional. Come and enjoy a lovely weekend away by diving into our Celtic world; finding hidden treasures and adventuring in mythical quests. We intend on making the resort completely carbon neutral. Using carbon credits through OXEGEN (OXE) tokens will (I hope) help people to go greener, faster.”
The recent boom in crypto can often lead to an opportunity for NFTs. This isn’t the only reason to invest in Myths. Today, individuals are increasingly motivated to lower their carbon footprint and make more sustainable choices. According to a study*** conducted by Earth Day 2023, 78% of the public believe in the importance of individual action to fight climate change, and over a third (38%) say that a financial incentive would help them make more environmentally-friendly decisions.
In addition to the Myths, Mythtopia offers their own crypto currency called OXEGEN (OXE). Becoming an OXEGEN (OXE) token holder, investors can join Mythtopia’s mission of planting 120,000 trees and re-wilding the natural environment. The liquidity of the OXEGEN (OXE) cryptocurrency token will come from the carbon credits of these planted trees. Ideal for eco-conscious investors.
The Myths NFT launch will fund the necessary capital to build carbon-negative dwellings on the eco-glamping site, which will be entirely powered by solar and geothermal energy. Not only this, guests can also get involved in activities that help them re-explore nature, such as lake swimming, star gazing, yoga, and even planting trees themselves.
The first mint date is set to take place in Autumn 2023. The funds raised will be used to build the unique and first-of-its-kind Mythtopia resort, which will open nine months later (Spring 2024).
To learn more about how you can invest in Myths NFT’s and OXE tokens and become part of the Mythtopia story, visit the website here.
Bringing Tech Into Education is the Key to Fintech’s Future
The rapid growth of the fintech industry in the UK has positioned the country as a global leader in financial technology. However, a significant challenge looms on the horizon: the educational gap in fintech and the broader digital skills gap in Scotland. A staggering 77% of students in the UK have never considered a career in the fintech industry, according to a 2023 survey from Quotezone.co.uk. 36% of these students explain that this is due to a lack of education and awareness about the fintech sector.
Without addressing this gap, Scotland’s future growth could be hindered . The key to ensuring Scotland’s continued success in fintech, therefore, lies in providing tech resources and tech training in education, equipping students with the necessary skills to thrive in this dynamic field. Let’s take a closer look below.
The digital skills gap and its impact on fintech
Besides a lack of education and awareness about the fintech sector, students face challenges such as a lack of relevant experience and pressure to gain such experience during their higher education journey. This educational gap is not unique to fintech but extends to the broader digital skills gap, where up to three-quarters of IT employers report difficulty in finding workers with the right skill sets.
As fintech relies heavily on technology and innovation, a shortage of skilled professionals could hinder the development of new products, services, and technologies. Furthermore, it may hinder the industry’s ability to keep up with rapidly evolving technological trends, ultimately affecting its competitiveness on the global stage.
Bridging the gap through tech in education
To ensure that students are adequately prepared for a future in fintech and other technology-driven industries, it is imperative to bridge the digital skills gap through education. One effective way to achieve this is by integrating tech resources and training into educational curricula. Emphasising coding and programming skills from an early age can spark interest in technology-related careers. Additionally, providing students in higher education with exposure to emerging technology, such as artificial intelligence or data analytics, can inspire innovation and creativity.
One shining example of how tech resources in education can lead to promising fintech careers is the partnership between Edinburgh Napier University (ENU), known for its innovation in computer science and cybersecurity, and FinTech Scotland. Through this partnership, students gain access to the latest academic insights, industry knowledge, and real-life problem-solving experiences.
Tech resources can include access to modern computer labs, software, and digital learning platforms or tools that promote better learning experiences. Note-sharing platform Studocu.com is an online portal that allows students to study more efficiently using lecture notes and study materials from various universities ”” including the aforementioned Edinburgh Napier University ”” providing resources that can possibly help them transition into fintech careers later on. Beyond fintech-specific skills, such tech training can also equip students with general digital literacy. This enables students to navigate technology efficiently, access online resources, and communicate effectively in a digital environment.
As students near graduation, the implementation of graduate apprenticeships can help students gain practical work experience that will later help them contribute to the workplace before the end of their first year. The Graduate Apprenticeship in Software Engineering at the University of Glasgow additionally reflects in more diverse graduates, with female trailblazers encouraging more young women in the UK to take up software engineering.
As we look to the future, bringing tech into education is the key to securing a prosperous future for fintech and Scotland’s position as a global fintech leader. To stay updated on the latest fintech news, check the rest of our work at FinTechScotland.com.
Image credit: Pexels by Liza Summer
Source: https://www.pexels.com/photo/crop-ethnic-trader-with-smartphone-and-laptop-on-bench-indoors-6347720/
Growing the fintech sector in the UK through collaboration
By Simon Pickering, Head of Insurance and Pensions, Finance Isle of Man.
Look to any league table on FinTech and it will tell you that London is firmly ranked in the top 3 globally, alongside North American competitors of San Francisco and New York. What this won’t reveal however, is that the British Isles has a burgeoning FinTech sector from Edinburgh to Douglas, the Capital of the Isle of Man.
Last year, Finance Isle of Man, the Government agency for the financial services industry on the Island, was delighted to sign its first partnership agreement with FinTech Scotland. This collaboration is a source of strength for the Isles and intended to promote and develop FinTech and InsurTech capabilities across the Irish sea, as well as boost economic and business co-operation and investment.
The partnership has already seen our two organisations working closely together to stimulate education, recruitment and employment opportunities, as well as provide businesses with opportunities to attend events and seminars, trade missions, conferences and Expos, including the globally renowned Scotland FinTech Festival.
We were delighted to welcome Stephen Ingledew, the Chair of FinTech Scotland to the Isle of Man this June to see first-hand how we are attracting global innovators at the Island’s first FinTech Innovation Challenge Demo Day event. This program, launched at the end of 2022 invited businesses from around the world to showcase their solutions to core challenges identified across the Isle of Man business community. 14 finalists, from Singapore to Switzerland, India to the US, were chosen to work closely with the Isle of Man Government and local financial institutions to refine their solutions. These are addressing a range of emerging issues from blockchain and cryptography protections, to AI-based business forecasting.
This is just one example of how we are establishing expertise in digital finance, and this builds on the success of the Island’s first InsurTech Acceleration Program, which last year supported pioneering InsurTech scale-ups to pitch their innovations to the business community. The program, which culminated in a sold-out pitching event in Douglas, marked a major milestone for plans to establish an InsurTech hub on the Island.
The potential for the family of British Isles, from Scotland to the Isle of Man, to collaborate and drive leadership in digital finance is significant and the past year has only seen our two jurisdictions grow in strength together.
I look forward to building on and growing this partnership over the coming months, not least returning to the Fintech Festival in Edinburgh this Autumn where I hope to have the chance to meet and reconnect with many of you.
London may sit highly in the global rankings for digital finance ”“ but this success story is undoubtedly also one of the British Isles.
Expansion of auticon ”“ social enterprise helping FinTechs add autistic talent to their teams
The social enterprise tech consultancy auticon which has a base in Edinburgh, has entered into an agreement to unite with Unicus, a similar organisation operating mainly in the Nordics which also seeks to improve the lives of autistic adults through employment. The historic deal establishes a global model for an autistic-majority social enterprise and ESG company, addressing the inequalities in employment for neurodivergent adults. The two combined companies will become the largest autistic-majority organisation in the world with 81% (465) of its 575 employees on the autism spectrum and will operate in 14 countries, including Norway, Sweden, Finland, Netherlands, Poland, Germany, the United Kingdom, North America, Australia, New Zealand, Italy, Switzerland, and France.
Unicus Founder and CEO Lars Johansson-Kjellerød commented: “By our marriage, we create the world’s largest autistic-majority corporation. With the focus on neurodiversity, we will continue to create unique results for our customers and an increased quality of life for our employees. The joint companies have the same DNA and vision to create a more inclusive world, and when we combine Unicus and auticon’s long experience, that is, in my opinion, the best prerequisites to successfully foster change and innovation and to create the leading social company focusing on neurodiversity. I am looking forward to the journey ahead!” 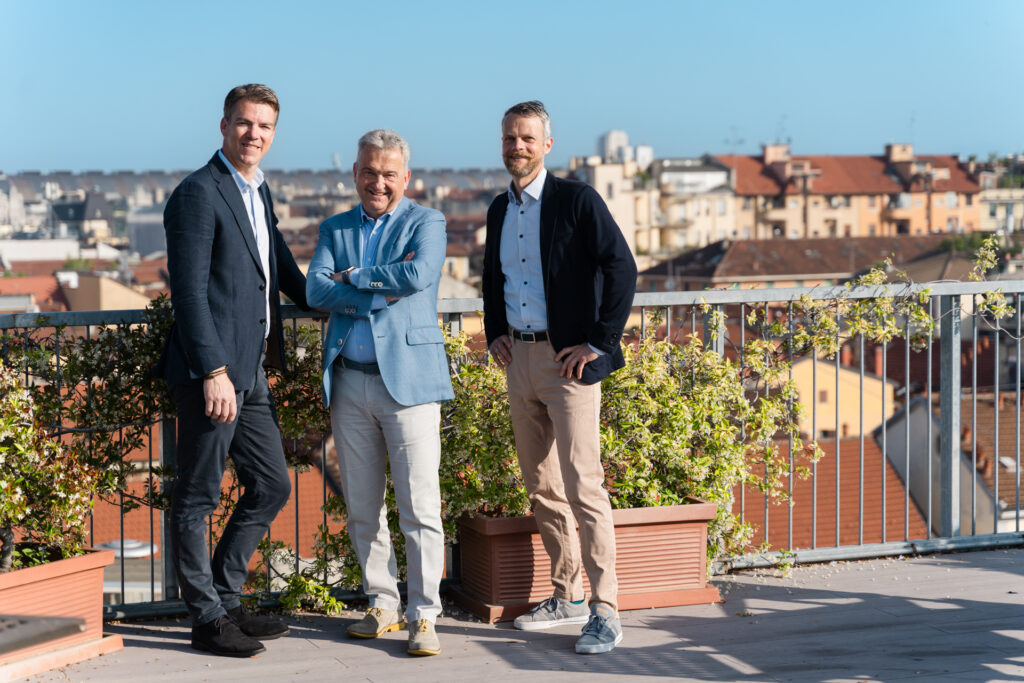
Unicus CEO Lars Johansson-Kjellerød, auticon Group CEO Kurt Schöffer and CFO Markus Weber are photographed in 2023 in Italy where the Management Board met to define details of the deal
Auticon is an award-winning social innovation company and offers organisations a unique way to bring tech and data expertise plus neurodivergent thinking into their teams. They integrate their autistic consultants into client organizations on a project-basis, performing as software developers, data analysts, QA engineers, and more. Clients experience the benefits of working with autistic professionals first-hand, opening minds and achieving excellent results through diversity of thought and creative thinking.
auticon’s clients in Scotland include a number of Financial Services organisations. David Hodgson, Engineering Lead for Engage Me Lab at Lloyds Banking Group said “Over the last year we’ve been working with auticon. Their support and training has helped us understand neurodiversity and opened positive conversations. auticon colleagues have brought strengths to our team both in delivery and contributing to our culture”.
auticon empowers the clients they work with through actionable neurodiversity training and advisory services. They are the first international neuroinclusion services provider offering lived experience, training, advice, technology solutions and experienced coaching to support organisations in their commitment to being neuroinclusive. They have over a decade of experience of attracting, recruiting, hiring, onboarding and retaining neurodivergent talent and want to help their clients deliver business and impact goals, just like they have, by having a diverse organisation that is successfully neuroinclusive.
“We don’t just jump straight in with off the shelf solutions. It is vital we understand your business and the people working with you. We know very well that one neurodivergent person is different from the next neurodivergent person, and it’s the same for businesses. We take a thorough 360 approach so that everything we do is tailored, collaborative and doesn’t create a silo of neuroinclusion. Instead, we help you to become a fully integrated neuroinclusive employer with practices that complement existing strategies, not create more work.” Emma Walker ”“ Regional Director Scotland
auticon was established in Germany in 2011 by a father looking to create more opportunities for his own autistic son as he realised that autistic people are too often unemployed or underemployed. It is estimated that only 29% of autistic adults are in employment (Office for National Statistics, UK, 2022) yet many possess cognitive strengths that make them particularly well-suited for careers in science, technology, engineering, and mathematics (STEM). Despite this, they are faced with barriers such as an exclusionary recruitment process, poor autism awareness, and employers feeling unprepared to offer support. This is what auticon and Unicus continue to tackle. The auticon London office opened in 2016, followed by the establishment of the Edinburgh team in 2019. Both offices operate rolling recruitment and are always keen to hear from autistic people with strong tech and data skills. Both offices are also always delighted to explore options for collaboration with new clients.
Find out more at Home – auticon United Kingdom or contact Emma Walker ”“ Regional Director Scotland on Emma.Walker@auticon.co.uk
Addressing stress in the tech industry
As we approach the summer season and holidays, it’s a good time to reflect on managing the work like balance.
Burnout is a significant concern in the tech industry, given its fast-paced and demanding nature; the constant pressure to meet deadlines and deliver results, to stay updated with the latest trends, acquire new skills, and outperform peers. Tight project timelines, high expectations, and a culture that values productivity all can lead to chronic stress and anxiety. Fear of falling behind or losing job security further exacerbates stress levels.
Post covid, working patterns have changed, more of us are continuing to work more at home, blurring the work-home, work-life distinction. Whilst this way of working has benefit from increased flexibility, the lack of boundaries can lead to increased stress, with remote work arrangements, global collaborations, and the expectation of always being accessible, adding to the difficulties in finding the time to disconnect and recharge.
We need to reconsider the work-life balance. Work ”“ life balance sounds like it is either/ or ”“ we work or we have a life ”“ we have no life at work. We are not one self at work and another self at home, we need a holistic approach, one integrated self at home and work. Work needs to be more life friendly, so feel comfortable taking breaks, recognise that we work better when we are relaxed and refreshed. Keeping continual pressure to perform will exhaust us.
The tech industry can be a double whammy with long hours of intense workloads leaving little time for relaxation and self-care and the sedentary nature of tech roles, with prolonged periods of sitting, limited physical activity, and poor ergonomic practices makes it harder to look after our physical health contributing to health issues such as musculoskeletal problems, obesity, and cardiovascular conditions.
So what can you do about it? Take advantage of flexible work arrangements, any wellness programmes or stress management resources. Make time for you. Recognise when you need a break and make and take time. Talk to colleagues about ways to better organise workloads, communication strategies to maximise your time. Pay particular attention to your home life, research shows that burnout is much more likely to occur if work and home are stressful. If this is the case ”“ do something about it now. Be proactive. Reach out to others to help you, it does not have to be a deep emotional heart to heart, just connecting with someone at work or socially, having a chat, doing something you like, can be restorative. Get outside, do something physical helps you see things differently and find other ways of doing things.
At the heart of our wellness is the ability to have autonomy, that is agency over ourselves, be in charge of ourselves, relatedness, that is connecting with others, and competency, that is recognising our skills. These all contribute to our purpose and meaning. This doesn’t have to be a huge life mission but can be a sense of what’s important to us today. Small acts of kindness, a smile, a compliment, all help build our connectedness to others and make us feel good too. And don’t forget to be kind to yourself as well. Lastly pay attention to your sleep, good sleep protects mental health ”“ but that’s another blog!
Dr Sheila Ross, health psychologist, co-founder Feeling good app ”“ proven audio programmes derived from sports training for recovering mental fitness and resilience. contact sheila@positiverewards.co.uk for more information about how your organisation could benefit from free app access. www.feelinggood.app
Photo by Oladimeji Ajegbile: https://www.pexels.com/photo/man-working-using-a-laptop-2696299/
Over 50% of employers and professionals embrace AI
New research conducted by FinTech Scotland’s strategic partner Hays reveals that a significant majority of both employers (57%) and workers (56%) in Scotland hold a positive view of AI in the workplace, advocating its adoption rather than fearing it.
The study gathered responses from over 8,800 professionals and employers across the UK, including nearly 450 participants from Scotland. Interestingly, 34% of employers remain undecided about the benefits of AI, while only 9% perceive it as a source of fear.
Currently, only 20% of employers report using AI tools, although certain fields, such as marketing, demonstrate higher adoption rates, with 37% of professionals affirming their use of AI tools in their current roles. The utilisation of AI is also notable in technology (30%), architecture (23%), and sales (17%). The primary reason for the limited implementation of AI tools is a lack of awareness or understanding regarding their advantages.
Keith Mason, the Director of Hays Scotland, explains that while the research highlights a predominantly positive attitude toward AI in the workplace, the adoption and usage of AI tools remain low as organisations across all sectors strive to comprehend how AI can benefit their operations. Currently, only 34% of employers invest in staff training to enhance their AI tool and technology skills, with a fraction of this group utilising tools like ChatGPT.
The significant advantages of integrating AI in organisations include cost savings, process efficiencies, and improved productivity. However, Mason emphasises the importance of a balanced approach that focuses on job transformation rather than replacing human workers.
Hays has observed the growth of AI-related recruitment in Scotland, but concerns regarding regulation and ethical use persist. Workers can reap the benefits of AI by transitioning into more engaging and meaningful roles, but this requires employers to invest in adequate upskilling and reskilling initiatives.
Mason highlights the worrisome gap between the rapid progress of AI technology and the lack of appropriate skills within the workforce to harness its full potential. Professionals have a substantial opportunity to upskill themselves and understand the impact of AI on their respective fields, enabling them to leverage AI tools for career advancement. The research strongly suggests that embracing AI and providing relevant training not only bridges the digital skills gap but also positions businesses as innovative and desirable in the evolving job market.
Mason illustrates an example of how AI can enhance recruitment processes, particularly at the initial pre-screening stage for matching candidates with job requirements, especially in high-volume recruitment scenarios like call centers. However, AI cannot replace the human element required to assess cultural fit, individual strengths, weaknesses, and character traits, which are crucial factors that add value to a business. The integration of AI must be balanced with human capabilities.
The study also reveals that the majority of employers (65%) plan to allow staff to use AI tools but will monitor their usage. Five percent of employers have already banned the use of AI tools, and 12% intend to ban tools like ChatGPT. Less than 20% of workers claim to have used an AI tool such as ChatGPT in their current roles, although this figure rises to 37% for professionals aged between 20 and 29.
Photo by ThisIsEngineering: https://www.pexels.com/photo/code-projected-over-woman-3861969/
Exits aren’t just IPOs & Roads Shows”¦
Article written by Mason Doick, Head of Corporate at Scottish fintech InfinitX
A successful exit plan for your business needs to start early and be built with the support of the team you have around you. And given current market dynamics it’s never been more important to invest the necessary time to fully consider the options available. At its core, there has been no real change here ”“ you’re either looking at a trade sale on a whole or partial basis, or otherwise it’s a case of releasing equity in the firm, affording founders and early stage investors in the business the opportunity to continue sharing in what will hopefully be the ongoing profitability.
One fundamental shift that has been observed however is companies staying private for longer. Traditional IPOs aren’t off the table – even if we have seen a real slowdown in deal flow over the last 12 months as monetary policy normalised and macro-economic headwinds have been building ”“ but the burden associated with seeking a full market listing only ever seems to increase. IPOs have always been a challenging and time consuming process, with a slew of hefty costs from various parties also needing to be accounted for. And bear in mind that becoming a public company is just the beginning, with significant ongoing obligations to maintain a listing – and placate investors ”“ also needing to be taken into account. Whilst the longer term benefits of an IPO remain clear, the increasingly complex and costly approach here is by definition necessitating a longer runway ”“ something that has the potential to starve the business of much needed capital to fuel growth.
With the IPO burden growing on an annual basis, against this backdrop we’re noticing a growing number of entities who previously may have looked at a listing deciding that the approach now looks uneconomical and the prospective return on investment is no longer alluring. But what are the alternatives if an IPO is too costly and a trade sale sees founders lose all economic interest in the business they cultivated? That’s where platforms like JP Jenkins are able to offer a third way, enabling cap tables to be reorganised, fresh investment to be made into the business in exchange for equity and then for a valuation ”“ and an ability to buy and sell stock – to be available on an ongoing basis. Issuers from many sectors are already benefitting from these services, including technology-play WeShop and the fintech incubator Quantum Financial. For many, this intermediate step has the potential to create a solid foundation when it comes to making the step to a full public market listing.
It’s difficult to ignore the headlines which all too often seem to be declaring the death of the UK as a capital raising venue. But according to UK Finance, the nation’s capital market remains one of the strongest in the world, with highlights including the fact so £14.7 billion of equity was raised in 2021 for UK companies. And the appetite for investing in privately held companies continues apace too. Using the proxy of the government’s EIS scheme, 2022 saw a record £2.3 billion invested under the program, some 40% up from the 2021 figure.
So the key takeaway here is that whilst underlying market conditions may be looking less than optimal and there’s no shortage of people willing to talk down “UK plc”, the investment market remains vibrant and businesses with solid growth prospects have little to fear when it comes to seeking fresh capital. Financial innovation means that there’s more choice than ever and allowing founders to retain an economic interest is arguably a worthy trade off if it paves the way for a better return in the longer term.