
Inclusion, fintech and future talent
Inclusion drives fintech innovation
This has been an action-packed time for everyone involved in the FinTech Scotland Cluster. With COVID-19 continuing to have an impact on our lives both at work and at home the energy across the cluster continues to inspire us.
In particular there has been an even stronger focus on inclusion. Since I’ve known it, this topic has always been front of mind for all involved in the FinTech Scotland Cluster. The work over the recent weeks has continued to demonstrate the drive to build an inclusive environment that enables diversity to win, innovative environments to advance future opportunities for all and build business success.
Inclusion driving future talent
We’re continuing to learn about the full range of organisations across Scotland that are working in practical ways to build skills, experience and communities to help people from different backgrounds explore opportunities in FinTech and Tech. It’s always a pleasure to learn about the practical approaches being taken to support and enable inclusion.
Code your Future is strengthening its focus in Scotland. It works with people who have had limited access to education, offering practical tech training to anyone that’s experience problems in getting meaningful work. There are ten graduates on course to graduate in November, who will be looking for opportunities. Previous graduates are working at BBC Scotland and STV, and code your future has plans to support another class of 30 students next year.
We’ve also been working directly with the team Inlcusion Scotland over the past few weeks as we look to expand the FinTech Scotland team through an internship. Inclusion Scotland work to ensure the full inclusion of disabled people into all aspects of Scottish society can be achieved. All of us a FinTech Scotland very much looking forward to adding to the team.
Inclusion drives business development
It’s been great to see the hard work from the team Lloyds Banking Group pay off so successfully as they launched the Launch innovation lab. The innovation themes of digital services and ESG are another example of the conscious focus being given to the topic of inclusion. Congratulations to Inbest and Legado who are both participating in the programme.
Obashi also shared an exciting development this week as it joins the World Economic Forum’s innovators community. An inclusive first for this forum, for Obashi and for Scotland. Obashi’s work is another great example of inclusion driving business development, moving from the oil industry to share its experiences of dataflow frameworks to bring clarity to new sector.
Inclusion drives financial inclusion
Over the last few weeks we have continued to see the efforts of many across the FinTech Scotland Cluster continue their unwavering focus on financial inclusion.
Amiqus continues its work with proxy address and launched a new trial to test the proposition. It works to provide those in danger of losing their home and subsequently their address with a proxy address and the innovation has the potential to ensure people continue to get access to vital services including access to the benefits they need.
FinTech focus on financial inclusion has also been supporting the UK’s Money and Pension Service (MAPS) who has recently launched a UK Financial Wellbeing Strategy. Thank you to, Nude Visible Capital Soar Directid FastPAYE and Money Dashboard for sharing your views. We know there will be more on this over 2021 and that COVID-19 has brought the topic of financial inclusion into sharper view.
Pinsent Masons recent research on Creating a Culture of Support in Financial Services has focused on the topic of Money and Mental health. It draws on a range of perspectives from a wide and diverse group of industry participants and explores a range of initiatives being built to offer inclusive support for those that want it.
And on a final related note, this week has been Talk Money week, another initiative to encourage people to engage in money and to get us all talking about it. Experience shows that money continues to be a taboo subject and research has highlighted that often people find the subject to daunting and complex. FinTech’s such as Sonik pocket and Moneymatix are working to help children engage with money and financial decisions at an early age. A bit like those why’ questions our children are so good at asking, innovations like this might go some way to helping us all talk about money.
Hoping you all stay safe and well.
Nicola
FinTech and Translation Industries; Interesting Bedfellows
When one looks at the business challenges and technological advancements, shared by both FinTech and Translation Industries, alike, quite a few interesting synergies emerge, including:
- Both being enablers of global online client interactions
- Both enjoying unlimited client reach
- Both disrupting traditional workflows, via technological advancement
- Shared concerns regarding data security
Enablers
FinTech is one of the most rapidly expanding sectors in the world, revolutionising personal & business finance, via online banking and applications. FinTech has changed the finance game, forever, and has rendered traditional banking methods, extinct.
Whether it is, the exchange of foreign currency, the ability to trade in cryptocurrency, the ease of access to the world of investment, or making payments via mobile, the sheer scale of opportunity is remarkable.
The translation industry, of course, performs the translation & localisation of banking apps, websites, and communications that all enable global trade. New advances & developments in translation technology, have played their part in changing the entire client experience. This could be through automated translation as opposed to human translations, secure portals for the transfer of client files, API technology to connect client and supplier systems, or Online Editor facilities.
Unlimited Client and Workforce Reach
Online workflows & operations mean that, in both industries, there are no geographical barriers to having a global workforce or client base. Translation & localisation also ensure no limitations in the launching of new products to international audiences.
Accredited translation agencies have invested and incorporated the latest technologies within their workflows. Their skillset in managing complex localisation projects, ensures that the FinTech industry can quickly & effectively market their services globally.
Although FinTech communications can be handled seamlessly, accreditation is an altogether different story. One principal issue that FinTech faces when expanding, is navigating the relevant local regulation. With codices differing between, and even within, countries, the legal side of FinTech growth is far from simple.
Technology: Disrupting Traditional Ways of Working
FinTech and Translation companies can successfully operate without necessarily needing brick & mortar facilities. Of course, there are both advantages & disadvantages to fully-online-based organisations; for those with global operations, however, the advantages are manifold. For example, lower operational costs allow SMEs and Start-Ups to invest in personnel and the business itself, rather than being burdened with the heavy cost of facilities.
Although, being location-independent does present its own set of challenges. The puzzles of how to best: manage, motivate, or support staff effectively, for instance.
Data Security
Data security is essential in all industries and sectors; this is especially acute with respect to financial transactions and the security of client translation documents. Unfortunately, we are all too frequently confronted with news of ransomware cyber-attacks, against companies such as North Hydro and Travelex. That said, this threat is perennial to all industries and companies.
Most translation agencies enable clients to order & transfer files online, via a secure Client Portal’. For the most technologically advanced translation companies, the client files are not issued directly to external translators, as was done in the past.
This new workflow facilitates the translation of files directly within the online translation platform, accessed via the unique & secure portal. Maximum security for client IP, is thus, guaranteed.
A Conclusion
As little as five years ago, it was unimaginable to foresee such a rapid shift to mobile apps & online-only operations; it is fascinating to contemplate where we will be in five years’ time.
These technological developments are not only advancing services & capabilities within the industries themselves, but also other, more indirect, business benefits. These include: a global unlimited client base; online-only operations; physical office facilities becoming no longer necessary; or flexible working options.
All of this significantly lowers the barriers to entry for entrepreneurs in all industries internationally. It will be enthralling to see this continued evolution, and what lies ahead for all of us.
This blog was written by Fiona Feldermann McCrae, Managing Partner, at McFelder Translations.
McFelder Translations, an ISO accredited powerhouse with almost two decades of technical experience, is your passport to building a global brand.
If you’d like to find out more about localising your FinTech communications, email: fiona@mcfelder.com.
Website
LinkedIn
Twitter
Instagram
Image created using Canva
Making FinTech more diverse and representative
Rise, Barclays’ FinTech ecosystem, is spearheading diversity and inclusion in the sector. This wide-ranging topic is the subject of the latest edition of Rise FinTech Insights, a regular publication from the bank.
This blog was written by Clare Whitehead, FinTech Platform Lead, Rise London
Building a more diverse future for FinTech
Working towards a more equitable future starts with addressing the wealth gap created by unequal access to resources by underepresented communities. Bridging the gap starts in the very early years from focusing on STEM eduction to the later years by providing FinTech resources for the baby boomer population.
The next generation is very evidently making great strides in FinTech when you watch Stemettes in action. Dr Anne-Marie Imafidon MBE and her remarkable organisation allows girls and young women to get creative with technology and see the opportunities available to them in joining one of the fastest-growing (but still male dominated) UK sectors.Pre-lockdown, Stemettes, their siblings and their parents would regularly take over our Rise London building to work on Future of FinTech’ hackathons. Based on the energy and enthusiasm of that crowd, we should be seeing more women in our sector in the years to come.
Rise community leading the way
We call the Rise ecosystem the #HomeofFinTech because it fosters such great technology and talent. The latter includes several diverse pioneers, and they deserve a shout-out. To name just three from our sites around the world:
- Kevin Barrow is a Black founder in our community and CEO of Mark Labs, a London-based FinTech company that shows how money can be used as an instrument for creating positive social and environmental change at scale.
- Nadia Sood is the female founder and CEO of CreditEnable, a Mumbai-based credit insights and technology company that applies proprietary data analytics, and AI to build solutions to the world’s biggest financial challenges.
- David Beatty is a co-founder of Gaingels, a New York-based company focusing on co-investing with leading venture funds in companies that embrace LGBT leadership.
Building and maintaining a diverse and inclusive environment are at the heart of Barclays’ values: Respect, Integrity, Service, Excellence and Stewardship. The global corporate and investment bank is a better, stronger and more successful organisation as a result of it.
As Jes Staley, Group Chief Executive Officer, Barclays said recently: “We are deeply committed to empowering the next generation of leaders, providing access to enterprise, employability and financial skills.”
A call to action
Personal empowerment is perhaps the main driving force in any diversity initiative, and these leaders demonstrate how effective it can be. Empowerment of a different kind can come when underrepresented communities come together to effect change in a system ”“ like the Latinx community in banking. Ramona Ortega, Founder of My Money My Future, argues the case with a FinTech call to action to create a more diverse FinTech sector. Speaking for that community, she calls on us to:
- Help more FinTech founders of colour get funded. Get to know them and open up your network to them.
- Partner, support or even acquire small diverse companies and, as a result, add value by reaching new markets (because existing products doesn’t fit the market for people of colour).
- Give Black and Latinx folks a seat at the table. If you’re launching a diversity campaign or coalition, make sure to have them involved.
And, if you’re a FinTech VC, take the time to research the opportunity and make a pledge to fund a Black or Latinx founder.
In case you were wondering, supporting the Black and Latinx community in these ways makes great business sense because the future will be even more diverse than it is now, with 2020 being the year when more than half of all Americans under seventeen years old are from a minority background[1] and with Latinos making up 35% of Gen Z[2].
AI ”“ the part diversity plays
Does technology have a part to play in making FinTech more diverse and representative of our societies? It certainly does. A great example is how we can use technology to design out bias in the many AI algorithms at the heart of so much data analysis and business decision-making. The way that financial decisions the algos make can be intrinsically unfair, and this bias is now seen as the biggest risk in data-driven technology[3]. Bias can creep in at any point in the development process, but technology and regulation both play a part in mitigating it. But a number of tools can measure bias and the trustworthiness of algorithms. Some are open source, some commercial. Furthermore, there are considerable efforts across academia to enhance these tools and provide improved algorithmic transparency and explainability’.
However, technology alone is not enough. As Ana Perales, AI Horizontal and Conception X Lead at Barclays Ventures, explains in the Rise FinTech Insights report, other factors are key to minimising bias. These include design and regulation. Designing ethics into algorithms requires, among other things, the very teams (of data scientists and developers) that create the code to be diverse. Additionally, developing a culture of frequent testing to collect data in an unbiased and systematic way should be part of any design.
Tracking changes to government regulation is key. Regulatory consultations and frameworks for AI highlight the close link between fairness and bias, on the one hand, and transparency and explainability on the other. For example, the European Commission, the Monetary Authority of Singapore, the Financial Conduct Authority and the Information Commissioner’s Office have all issued guidance that includes principles of fairness, bias, explainability and accountability. Check out Rise FinTech Insights for examples of how bias can creep into AI and of startups that specialise in analysing and reducing bias.
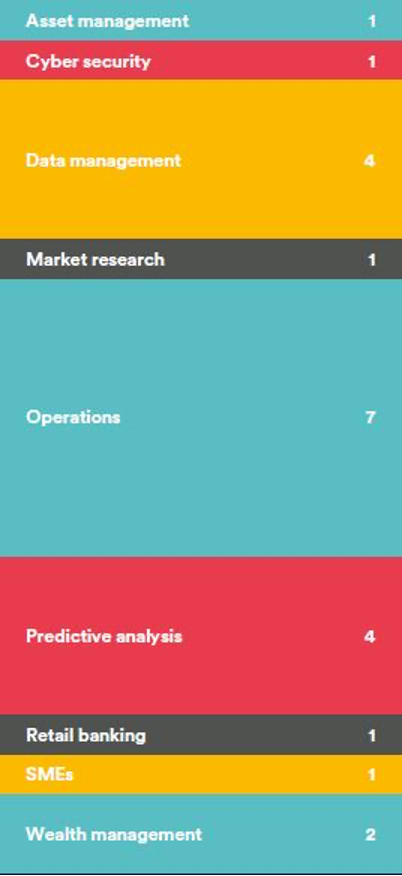
The distribution of AI companies across the Rise ecosystem
Download all editions of Rise FinTech Insights here.
[1] https://tribecamarketinggroup.com/tribecatrending/get-to-know-hispanic-generation-z/
[1] Report: AI Barometer by the Centre of Data Ethics and Innovation
Europe’s Fintech Startup Environment – And How The Current Crisis Drives Its Further Development
Europe is great in many ways, and a favorable environment for many economic sectors to flourish – and the fintech startup industry is definitely among them. While the Silicone Valley is booming, and Atlanta is following as a close second, the regional players, such as Estonia, are emerging to challenge the world’s most prominent fintech hubs.
European fintech environment today: an overview
One can easily see the benefits available to the fintech entrepreneurs that choose to base their companies in Europe. Among the most prominent ones is the European regulatory environment, which is both start-ups oriented and tailored in a way that fits the specifics of each of the states in the region and the European market as a whole.
Having said that, we should also note that there are a number of challenges that are preventing Europe from making a strong standing among those with the most attractive start-up environments in the world.
Firstly, unlike the US start-ups, ones based in Europe need to rethink their line of development. While the former is more focused on market penetration and a marketing boom that will make them widely known, the European start-ups need to secure the revenue first, before thinking of what the next step should be like.
And, secondly, despite London and Berlin – the current fintech startup hubs of Europe – entrepreneurs based elsewhere can sometimes struggle to have access to funding opportunities. The lucky few manage to get initial funding outside the region – in the USA or Asia, however, once that is secured, the start-up is also likely to abandon Europe for a more favorable environment.
Despite the challenges listed above, Europe remains to be the birthplace of the fintech unicorns, such as the Swedish payment system Klarna, the UK’s bank for entrepreneurs OakNorth, N26, and the Revolut, that we will examine in a bit more detail later.
Amidst the outbreak of the COVID-19 pandemic, the European fintech sector is likely to flourish even further. With the digitalization of most of the products and services, the demand for fintech solutions is growing – and European start-ups are all too happy to cater to it. The main sectors that the regions’ fintech entrepreneurs are targeting are blockchain, banking, and financial trading, and we will discuss them in more detail below.
Blockchain – The Newest Solutions To The New Trends
Ever since the blockchain solutions were first introduced, their popularity did not cease to stop growing. The current estimate is that the world blockchain spending will increase to more than 15 billion in 2023.
However, with such a rapid expansion, it became apparent that some sort of regulatory mechanism is imperative to ensuring the safety of all the parties involved. But how does one control something so strongly based on anonymity?
The solution was once offered by Ethereum (which, coincidentally, was co-founded by a programmer of Eastern European descent – Vitaliy Buterin). Smart contracts that the company came up with are now widely used to document the details of transactions, and can even be used as a legal confirmation in court disputes. The technology is especially popular with the individual lenders in Europe, as they act as an additional layer of security for both the lender and the borrower alike.
Financial Trading ”” Innovation With Benefits For All
Financial trading is one of the rare few of the markets that was always glad to welcome new technological solutions and incorporate that into the traditional way of functioning. It is, therefore, unsurprising that European start-ups are often trying to tailor their services in a way that best caters to the needs of this market niche.
A good example of that would be the UK-based fintech company Revolut. In an attempt to both expand their customer base and penetrate the financial trading market, Revolut came up with an idea of integrating their services with the brokerage offering, and it worked out very well for them both. Revolut did expand their client base and made themselves even more recognizable, trading service providers obtained an efficient payment system to offer, and the traders benefited from a mechanism that significantly reduced the hassle involved with depositing or withdrawing funds.
After proving to be both efficient and profitable, the integration of services with financial trading was soon picked up by the European fintech start-ups and continues to be done so today. There are only a few downsides to this development, and the most prominent among them is the lack of accessibility to the full services that either a trading company or the Revolut (and other fintech companies of a similar nature) has to provide. The client of a fintech service provider would still have to join a trading company separately, and, similarly, the trader will have to get in touch with the fintech to get access to the full variety of their services.
Other than that, functional integration goes a long way to show that there is definitely potential for the Europe-based fintech start-ups to come up with breakthrough technologies and reclaim the title of being listed among the world’s top largest technological hubs.
Banking – A Means Of Achieving The Ultimate Goal
Although the banking segment is strong in Europe, there is one struggle that it is yet to win – namely, the desire to achieve 100% of the inhabitants of the region being banked. While the numbers are sufficiently high in Western Europe, the situation is very different in the Eastern part of the region.
With that in mind, European fintech start-ups have stepped in to try to solve the issue of unbanked citizens. Russian Tinkoff online banking, recently valued at over 5 billion USD, is a shining example of how financial technology can offer a working solution. Tinkoff is completely digitized, and, in that, reduces the hassle of having to physically visit one’s bank to virtually non-existent. With such convenience combined with the efficiency and trustworthiness of the service provider, Russia saw a significant increase in the coverage of the previously unbanked population.
The opportunities for fintech start-ups in Europe are widely known and actively used, and on top of the prominent regional fintech centers, such as Berlin and London, Europe is currently seeing a rise of the new players, such as Estonia, Bulgaria, and Lithuania. The niches to occupy are plentiful, and the outbreak of COVID-19 is generally favoring technological advancement, however, there are still a number of aspects of the industry that need to be refined – with the lack of accessible funding among the most obvious ones.
If the current crisis and the fintech boom associated with it will lead to those challenges being successfully resolved, Europe can easily become a strong competitor to the United States and Asia in the development of modern fintech solutions.
Photo by Jonas Leupe on Unsplash
Ambition Can Attract the Right Talent
A few months ago, Mark Logan produced his long-awaited, government-commissioned report on the Scottish tech ecosystem, of which FinTech is now a key component.”¯
There were many positives. We have established a thriving, well-connected community. However, Mark was quite clear; things need to change.”¯
We need to think bigger; we need to push boundaries and reach further than many think is possible, capitalising on the global opportunities that will take us beyond the tipping point.
One of the pillars at the heart of Mark’s vision for a larger, more robust Scottish Tech ecosystem was, of course, people.”¯
But how do we attract this critical talent?”¯
Growing our own talent, working with schools and universities to prepare future captains of industry is vital. Making sure the technical skills taught are combined with commercial acumen is critical. However, this is a generation away.”¯
To realise some more immediate returns and to capitalise on the global opportunities, tech companies in Scotland need to attract the sort of investment required to be an international player and employ the talent with the experience and knowledge to succeed.
Embrace Your Ambition
With COVID19 banishing most traces of presenteeism and reassuring business leaders that it is possible to operate remote teams without impacting on productivity, this has opened up access to a far more significant, global labour market.”¯
However, while the talent exists, encouraging them to join your team instead of sticking with the FinTech operating out of London isn’t easy.”¯ ”¯ ”¯ ”¯ ”¯”¯
What was clear from listening to Shane Kehoe, Co-Founder at SVK Crypto, who was a keynote speaker at EIE20, is the acknowledgement from London that there is an incredibly exciting scene here in Scotland. However, for whatever reason, the investment and to a certain degree the talent isn’t making its way north at quite the speed we would hope.”¯
Something both Shane said at EIE20, and Hector Mason, Investor at Episode 1, mentioned when we interviewed him for the TalentSpark podcast last year, was that the level of ambition shown by the companies in London and America is exceptionally high.”¯”¯
Our inbuilt Scottish apprehension prevents many from showing the global ambition we harbour, and from taking the risks that perhaps our counterparts in Silicon Valley, and to a certain degree those down in London, take for granted.”¯
These founders are shooting for the star’s fuelled by mind-blowing ambition, and many eventually fail. However, the lessons they learned along the way, will be invaluable to an emerging FinTech and the experience will help attract more significant levels of investment.”¯
This faster turnaround of experienced talent was, in fact, one of the potential solutions suggested by Mark Logan in his report.
Define Your Market
Another key aspect of attracting the right talent for your business is defining your ‘why’.”¯
Whether you are trying to attract the COO from a FinTech that has just exited to a global institution, or you have your sights set on securing the services of the most inspiring CTO, you need to sell a vision of a business that does more than it says on the tin.”¯”¯
This concept became abundantly clear when we worked with one of Scotland’s most exciting new FinTechs‘, Nude.”¯
Lots of company leaders and advisors talk about creating the right culture, but Nude have worked hard to define their culture and make it a key component of their hiring process.”¯”¯
Nude has now raised £5.7m, and their most recent raise was to help them deliver on the government-backed Lifetime ISA (LISA), created to help first-time buyers get onto the property ladder.”¯ ”¯
However, there was a time pressure on getting the LISA product to market, and it required the recruitment of up to ten staff. It was an exciting project for our team to get stuck into but daunting none the less.”¯
Nude’s Why
Their one goal is to:”¯
“Help you reach life’s most important life goals, starting with buying a home”.”¯
So, the ‘why’ was clear, and after meeting with Stephen Doherty, COO, it was apparent their culture was laser-focused on customer-focused delivery.”¯
Having this made the process that we went through very clear. It helped us define the type of person we were recruiting for making shortlisting far more effective. The vision and values also helped sell the opportunity to an already engaged audience which meant the candidates we put forward had a higher chance of success, reducing the time to hire considerably.”¯ ”¯
So, while defining the vision and culture of the company certainly helped us, it created a very attractive proposition in an incredibly competitive marketplace.”¯
Diversity and Inclusion
Living and breathing an inclusive culture from the very top is not only the right thing to do, but it makes financial sense too.”¯
While no one should have to be convinced of the benefits of a more diverse mindset throughout your business, based on the potential financial upside, it does seem to be rolled out as part of the argument.”¯
Jacqueline De Rojas, Chair of Tech UK, has highlighted the imbalance of female representation in the tech sector, and the potential impact this can have on everyday lives.”¯
The retention rate of Black, Asian and Minority Ethnic is far shorter than that of their white counterparts. This could be in part down to the, on average 13% lower salaries compared with their white workmates.”¯
However, it is almost certainly also the result of a lack of buy-in from senior-level executives to embody change, making the role of Chief Diversity Officer (CDO) incredibly frustrating.”¯
It is incumbent on senior leaders, founders and CEO’s to take ownership of the diversity throughout their organisation. They need to embody the culture and take action to stamp out any perceived bias. Only when the policy is taken seriously at the top level will change genuinely take place, and companies will see the financial benefits of having a diverse workforce.”¯
So, if the many fantastic companies that make the FinTech sector here in Scotland are to achieve the growth they all grave, they need to be brave and embrace their real ambitions. They need to define their vision and culture and embody a diverse and inclusive hiring approach.”¯”¯
Author
- Peter Dunn
- Associate Director (Tech and Digital)
- Eden Scott
- 07795 553 835
Why FinTech Brands Use Content Marketing
The FinTech industry is one of the fastest-growing sectors in the world. By the year 2022, the global financial sector is expected to be worth over US$26.5 trillion with a compound annual growth rate of 6%.
FinTech brands are now increasingly looking to include content marketing as a key pillar of their marketing and growth strategy.
We spoke to FinTech giants Klarna and Modulr as well as their content marketing partner, Copy House to find out more about the role content marketing plays in their strategy to increase brand awareness and engage audiences.
What is Content Marketing?
Content marketing is a strategic marketing approach that focuses on creating and distributing valuable and consistent content to attract and retain customers from a clearly defined target audience. On average, content marketing pulls in 3x as many leads and costs 62% less than traditional marketing. A well-written piece of content also continues to drive traffic to your site long after you publish it.
Marketing Challenges For FinTech Brands
When it comes to marketing FinTech, most brands face challenges around trust and education.
Traditionally, finance marketing has been aimed solely at IFA’s and the content typically used complicated and jargon-heavy language, which shut out smaller businesses and left customers confused about how financial services work.
FinTechs brands often look to challenge this status quo by creating a more accessible world, which naturally means they also have to educate their audiences in the process.
Klarna’s Senior Marketing Manager, Elias Pitsavos, explains:
“Many traditional financial institutions are afraid of Open Banking because it challenges established business processes and poses the threat of their customers abandoning them. There are also many small companies that we need to reach that don’t know about Open Banking. So we need to find a way to educate them about the service and its value.”
How Content Marketing Conquers These Challenges
“Content marketing is all about building trust and educating people. If your website looks and sounds good people are more likely to trust you. Content helps you give them quality insights without them having to ask for it.”
Kathryn Strachan, MD at Copy House
Content marketing also helps FinTechs to:
Increase Brand Awareness
Being a relatively new player in the field of finance, FinTechs are competing against household names like RBS and HSBC when trying to acquire new clients. Content marketing is an excellent way to increase brand awareness and educate people about their solution.
Klarna’s Elias Pitsavos explains: “
Klarna already has an established brand name when it comes to our core business and our payments solutions. We want to increase brand awareness in the Open Banking world and establish Klarna as a thought-leader in the field. Content marketing helps us do that.”
Build Trust & Credibility
Rightly so, people are nervous about who they trust with their money, so to gain new clients, FinTechs must let people know who they are and what they offer.
Content marketing helps FinTech brands build trust and prove their credibility before someone even speaks to their company. Businesses can then use content marketing to scale those relationships and reach a wider audience, regardless of team size or budget.
Modulr’s Chief Marketing Officer, Edwin Abl, informs:
“As we are a scaling business, we need to get people to understand our brand and our services. Content marketing helps us build credibility and prove that we’re a viable alternative to traditional banking. It’s a key pillar in our strategy to achieve that.”
Exercise Thought-Leadership
“We educate our audience through content marketing. Since traditional marketing methods like events aren’t available to the same extent because of COVID, content plays an even more vital role in getting our message out there.”
Elias Pitavos, Klarna.
By sharing useful information in a blog article or on social media, FinTech brands can demonstrate their expertise in the field and kickstart conversations.
Modulr’s Edwin Abl, adds:
“Content marketing helps us communicate what we stand for and how helpful we can be from an education standpoint. It’s not just about marketing, but teaching the audience about changes in the industry and informing people of what’s going on. We use content marketing to build our community.”
Whether you’re an established FinTech brand or a startup, content marketing is critical to creating a successful marketing strategy. Other marketing methods come and go, but people have always, and will always want content.
By putting energy into creating high-quality, SEO optimised content ”“ or outsourcing your content creation to a content marketing agency ”“ is a long-term investment, but will bring great results. So start investing now.
Note: Copy House is a content marketing agency specialising in FinTech content and provides content marketing support for Modulr and Klarna. By crafting SEO-optimised, educational content, Copy House helps these FinTech giants increase brand awareness, build trust and educate their audiences. Find out more about Copy House byscheduling a call or visiting their website.
Photo by Kaboompics .com from Pexels
Card issuing and management: staying relevant facing ever faster changing customer expectations
How card issuers are rethinking their business models and technical architecture
Our payments landscape is changing rapidly, and traditional card issuers need to keep up with new competitors that meet customer expectations. Especially now, during times of lockdowns and working from home, customers are expecting digital services that are seamlessly integrated into their every-day lives. This means that Issuers have to rethink both their business models as well as their technical infrastructure to keep up with competitors and customer expectations.
Convenient, fast and reliable
First of all, how popular are card-based payments nowadays? As research shows, this payment method will play a major role in the near future. By 2022, it is estimated that 47 percent of global e-commerce payments will be made using eWallets, while 28 percent will be made using credit and debit cards. At the point of sale (POS), it is expected that 52 percent of all global POS payments are made using either a credit or debit card, with eWallets (28 percent) assuming the third place. These numbers have to do with the fact that consumers find card-based payments convenient, fast, familiar, reliable and secure. A little further in the future, we are likely to see the general replacement of tangible plastic cards by alternative means of payment like mobile payment apps and virtual cards. However, the payment itself will remain card-based and will, thus, to a large extent rely on the established infrastructure of schemes like Visa, MasterCard and local schemes.
Crowded Landscape
This is the reason that the card issuing landscape is getting increasingly crowded as new players spot opportunities to tap into the unresolved growth potential of the card payments industry. Over the years, many traditional banks have delivered card payments services on a license to operate’ basis, meaning that they have typically issued basic products like debit, credit and prepaid cards and have not shown any interest in differentiating themselves through these products. Neobanks seem to be utilising the full potential of cards and card payment services by making them the focal point of additional services. This places the cardholder at the center of the payment experience. Think about services and features like real-time information on transactions, convenient onboarding processes and product control (for example spending limits and geo-blocking).
Challenges
As a result, traditional card issuers are feeling the pressure of increased competition. It urges them to transform their card processing platforms to remain competitive, but there are a number of internal and external challenges that need to be overcome. Think of diversifying channels and the demand for a consistent experience or the creation of new technologies that are disrupting financial services and the arrival of regulations like Open Banking, PSD2 and GDPR. Other than that, players are forced to focus on efficiently processing massive volumes to make the business case viable. In the meantime, internal challenges play a key role as well. Traditional players are, for example, struggling with their legacy systems and their ability to leverage the vast amount of data points produced by transactions. Besides that, players need to protect sensitive data and actual monetary transactions against fraud. And there is also the struggle of managing the increasing number of compliance procedures.
The Solution: Open Innovation
While there are many interesting solutions from Fintechs and other third parties available that address some of these challenges or simply offer a superior frontend experience, they are often hard to integrate into existing legacy applications and some processing partners do neither offer a modular platform nor the commercial flexibility required to quickly test and integrate third party solutions. At Worldline, we are convinced that the best results come out of open innovation. That is why we are hosting the annual Worldline e-Payments Challenge where we bring together our clients and fintechs to create innovative use cases together with our experts. Our modular, real time processing platform allows for simple integration of these solutions based on a large and powerful set of APIs.
Are you looking for creative ways to address the challenges Issuers are facing today? Get in touch with our experts to learn how Worldline can support you. Contact Us: worldlinecommunications@worldline.com
Fintech Recruitment: Top Tips From the Professionals
It’s no secret that great fintech candidates are rare. It’s a growing industry that’s becoming cooler all the time. Face to face and phone interactions are decreasing (let’s not lie, we’re all experts at talking to chatbots now!), so the highly skilled roles needed to facilitate these changes are becoming pretty in-demand.
Add an increase in the need for cyber security and financial insurance and you’ve got a talent gap. But, if you’re reading this, you probably already know that…
In Scotland, we boast some of the best fintech businesses in the world; as the BBC reported in January 2020, the number of Scottish fintech firms grew 60% in 2019. That’s obviously slowed in 2020, but the outlook remains strong.
So, in this competitive market, how can your fintech recruitment strategy make your business survive and thrive? I’ve put together the top tips I’ve learnt working in tech and fintech recruitment that should help.
Refine your EVP
Highly skilled people in fintech can command high salaries. So, you need to differentiate your business to make it stand out. You need to give people a reason, more than money, to work for you.
And no, we’re not talking pool tables and free coffee.
The pandemic has increased the demand for flexibility and that means working from home, moveable hours, and part time working.
People also want to know that they’ll be looked after as your employee. Do you provide private healthcare? Counselling? Gym memberships? Clearly communicate what you do to improve quality of life in your careers page, your marketing, and any external sites.
Then think about your company culture, particularly important when most of us are working from home. Show how you’re inclusive, how you welcome new employees, and show this to potential candidates.
If you don’t provide the things above, why not? They’re what will make you stand out from the competition.
Widen your talent pool
Fintech in Scotland is still a relatively small industry. If you really want to discover great talent you might want to look outside either the fintech pool or your locality.
Thankfully, with great advancements in tech (especially recently) it’s much easier to work remotely and most are finding it a positive experience.
By widening your search, you get a bigger talent pool and more diverse candidates. A May 2020 McKinsey report said that “companies in the top quartile for gender diversity on executive teams were 25 percent more likely to have above-average profitability than companies in the fourth quartile.”
How candidates view their careers is changing too. We used to work in the same role for most of our lives, but now, people are continually changing roles, reskilling, and upskilling. Now, this ethos means it’s easier to hire people who can be trained to do specific roles, rather than only looking for those already in them.
Someone who works in customer service might be a great fit for sales, and we’ve seen designers move to development roles easily.
Get methodical about hiring
In a market with talent gaps, it’s easy to make the wrong hire. In the long-term, this can cost you a lot ”“ both financially and in your company culture. If you have a robust hiring method though, you won’t make these mistakes.
At Solutions Driven, my team and I use RPI ”“ Recruitment Process Intelligence ”“ to make the right hire, first time, every time. We use RPI with everyone from big banks hiring CEOs and startups hiring sales execs. And it always works.
Through RPI, we use various methods to find and secure the best talent. The two fundamental ones are the 6s and the 6F processes.
The 6S process is how we find and secure candidates:
We hold an initial Scoping meeting to identify the hiring needs
We create a Scorecard that matches the businesses’ criteria
We source candidates via the latest technology and human intelligence,
We Select them against the scorecard, interviews and psychometric testing
We Secure them via our 6F Process (more on that in a sec)
We Satisfy both the candidate and our clients by measuring the results and regular check-ins.
For the 6F process, we ensure that candidates and companies are matched on six key areas ”“ Fit, Freedom, Family, Fulfilment, Fortune, and Future ”“ so that your potential hire becomes a long-term, happy employee who helps propel your business forward.
Exciting passive talent
Your ideal hires are probably already in roles. Thanks, talent gap! So, when talking to fintech companies, we’ve found a big problem they have is activating passive talent who are already happy in their roles.
Many don’t even want to entertain an initial conversation.
The first thing you can do is one we’ve already discussed – improve your EVP and how you market it. In this industry, top talent wants to work with companies that are going somewhere or doing something exciting. It’s important that your brand is known for being forward-thinking and allowing people to work on great projects and progress.
It can be hard to activate passive talent by yourself. It takes indepth technology, experience, and a lot of time. So sometimes, it’s best to get the professionals in.
If you’re really serious about getting the best people to join your company, a good recruitment company, who knows your industry and knows how to attract great people will be far more cost effective in the long-run than doing it yourself.
Blog written by Nicki Paterson. Nicki is Global Head of Business Growth at Solutions Driven, a Glasgow company that has specialised in business-critical recruitment for over 20 years. Working on a flat-fee basis and 12 month guarantees, Solutions Driven’s focus is getting the right people for the right roles, first time, every time.
If you’d like to find out more about how you can recruit effectively in the fintech market, get in touch with Nicki at npaterson@solutionsdriven.com.
Small business resilience and the evolution of ecommerce
The continuing shuttering of small businesses on high streets across the country is being accompanied by an unseen birth of new, exciting digital-only small businesses.
Periods of economic downturn typically result in a decline in new business registrations and at the beginning of the pandemic, it looked like UK SMBs were set to follow in this trend. For instance, statistics released by the ONS revealed that business creations slowed during April and May.
Despite this, Companies House figures reveal an overall increase in the number of new company incorporations in Q2 when compared to the previous year. This is indicative of a plethora of new business ventures inspired by our changing way of life.
Many of these emerging businesses are digital-first by necessity of the global lockdown they were born out of. Take for instance an independent hardware store which was already struggling prior to the pandemic. They may now find themselves in a position of renewed success, selling specific gardening tools via Shopify and Instagram marketing. While they may not have a strong credit history they do have a vast data footprint, owing to the numerous systems they rely on to run their business. Each data source, from their accounting package to their POS or ecommerce system provides a valuable yet siloed view of performance.
The shifting value exchange
However, the modern SMB expects systems and services to work together seamlessly and appears more willing to share their data in an open and automated fashion in order to ensure this. For instance, in September of this year, it was reported that the use of open banking had doubled in just nine months – an increase of one million users since January.
This increased appetite for interconnectivity between financial systems has opened the door to a much more collaborative, bespoke and diverse service between small businesses and their financial service providers. This is evidenced by the growing convergence of the POS, ecommerce and lending industries. Square Capital, Shopify Capital and Worldpay Working Capital are just some examples of funding facilities utilising transactional data to determine creditworthiness and offering finance at the point of need for small businesses.
Moving forward, customers who are willing to share their financial data digitally via accounting, ecommerce & POS package authorisation or open banking will likely benefit from a better service and more affordable products. For instance, lenders will be able to offer more favourable rates due to their enhanced ability to calculate risk and the notable reduction in the cost of serving these customers. The end result will be a shifting value exchange for small businesses whereby the benefits of sharing their data will become even more tangible than ever before.
The rise of ecommerce
The conditions of the global lockdown required existing businesses to pivot in order to remain viable. As a result, the period between April and July saw 85,000 UK businesses launch online stores or join online marketplaces. Many of these SMBs thrived during the pandemic as their adoption of ecommerce solutions coincided with a rapid increase in online sales, accelerating e-commerce growth by five years.
With the pandemic shifting the primary channel of trade online, gaining access to ecommerce and point of sale data is now crucial for financial service providers. The mutual benefits of doing so are multifaceted. For instance, commerce data can be used by lenders in particular to improve underwriting processes and credit decisioning. Small businesses will therefore benefit from a faster and fairer service which goes beyond traditional methods of credit scoring to consider their performance from multiple data sources in real-time.
This cultural shift towards enhanced digitisation and the growing importance of ecommerce will likely have a lasting impact on the way we think about the financial health of small businesses. In order to take advantage of this opportunity, financial service providers will need to replace siloed data with a connected ecosystem of unified financial data sources.
This article was written by Pete Lord, CEO and Co-Founder at Codat. Codat lets banks and fintechs plug into their small businesses and the software they use, giving them seamless access to real time customer data. Codat is building an ecosystem of connected datasets that handle the heavy lifting of integrations, leaving providers free to focus on improving their offerings for small businesses.
Photo by BedBible