
4 Ways Content Marketing Benefits FinTechs
Did you know that 91% of B2B brands use content marketing to reach their customers?
With over 4 billion people using the Internet daily, it’s not surprising that so many brands are turning to content marketing.
Content marketing helps all companies boost brand awareness, connect with new customers and retain existing ones.
Fintechs, especially those in early growth stages, can leverage content marketing to stand out from the crowd. Content marketing plays a unique role in helping FinTech brands overcome many of the challenges associated with emerging into a new market and launching the brand from the startup stage.
Keep reading to discover the top four ways Fintechs can benefit from building an online presence and creating quality content.
1) Communicating Complex Tech in Simple Language
Most Fintech solutions are based on complicated technology, like Blockchain. But despite complex underlying technology, most Fintechs target customers with little or no understanding of the tech.
For example, Fintech Blockchain adoption rates are expected to grow by 75.2% by 2023. Yet, customers’ understanding largely hasn’t kept up ”” an HSBC survey shows that 59% of customers don’t understand Blockchain.
Without this fundamental understanding, Fintech solutions can seem risky or scary, which can prevent brands from reaching mainstream adoption. Yet, overcoming this information gap and helping customers understand the tech can significantly change the game.
Good content marketing helps you achieve this aim by ditching the jargon, breaking down complex topics and explaining sophisticated technology in a way the average consumer can understand.
2) Brand Equity: Starting From the Ground Up
Creating brand awareness is crucial for building trust, reaching new customers and driving sales. So much so, that 77% of B2B marketing managers say branding is vital for growth.
Traditional financial providers can fall back on their brand name. After all, they’re a household name.
But, Fintechs face an entirely different situation as most startup brand names aren’t known. Successfully attracting customers and establishing yourself on the market requires you to quickly build brand equity and awareness.
“A brand does not exist within a company or organisation. A brand exists in the minds of your customers. A brand is the sum total of impressions a customer has, based on every interaction they have had with you, your company, and your products.”
Content marketing incorporates many aspects of your online presence to create one, unified brand. So your customer has a consistent and reliable interaction with your company whether they’re engaging with you via social media, emails or on your website.
3) Communicating Founders’ Mission & Values
Most Fintech founders are driven by impressive and admirable visions of how they can improve business owners or customers’ lives and relationships with finances.
Whether it’s creating fairer lending or helping people make smarter budgets, Fintech companies are founded for a reason.
But, this mission and value need to be communicated and shared with the world to attract customers and build brand loyalty.
Accenture calls purpose-led branding the movement from me to we’. Their research shows that customers increasingly choose to work with brands with a strong purpose or mission. So much so that 52% of customers would rather use the services or products of a brand that serves for something bigger and aligns with their clear personal value.
Content marketing can help you bring your visions and missions to light. Think founder interviews, a kickass about page on your website or even social media videos explaining your fundamental values. Sharing this type of content with prospective and current customers boosts brand loyalty and drives growth.
4) Employer Branding
As a Fintech company, you need to find employees with the right skills and mindset. Developers, data scientists and other tech professionals are often in short supply. As technology continues to evolve, this skills gap will only worsen.
FinTechs also have to overcome the additional challenge of attracting developers and data scientists to a new company. Prospective employees could worry about the insecurity of joining a startup or entering a relatively new market.
Employer branding can play an essential part in helping you attract the industry’s best and brightest. Capturing your values and unique selling point on your website and through thought-leadership articles improves your credibility and shows your company as an exciting place to work.
Note: Kathryn is the CEO at Copy House, they specialise in helping Fintechs bring their brand to life and create a strong online presence with SEO optimised websites, thought-leadership content and social media. Find out more about Copy House by scheduling a call or visiting their website.
Diversity in Recruitment ”“ FinTech can make it Happen
Photo by Ivan Bertolazzi from Pexels
I recently handed in my notice to my current employer and I now face not only the challenge of finding a new job but of also whether to declare my disability or not in the application process.
My current employer, Meraki Talent, is a disability confident and a member of ENEI (Employers Network for Equality and Inclusion), so they are fully supportive of me, as they understand I need a new challenge and even offered to help me in my search, as I look to take my career in a new direction.
Despite my own disability, having dwarfism, I have successfully worked in recruitment for over 9 years but even I am fallible to unconscious bias (Unconscious biases are learned stereotypes that are automatic, unintentional, deeply ingrained, universal, and able to influence behaviour) when identifying suitable candidates, so I do understand the recruiters need to fill jobs. That is how they build relationships and make commission.
The unconscious bias is sometimes referred to as the Halo Effect. The Halo Effect is a type of cognitive bias in which our overall impression of a person influences how we feel and think about his or her character. With these biases will my disability stop me even getting through the door?
Having also been on the candidate side in the past, I have declared my disability, as part of the application process a number of times. In doing so this is claimed to guarantee you an interview, if you meet the essential criteria. However, I am yet to receive an interview through these means in my working career. Despite being proud of who I am, I have had a lot more success when I don’t mention that I am disabled. Am I bypassing the biases? This then means the interviewers are put in a difficult position when it reaches interview! They have to judge me on my abilities, rather than my disability.
It does make you question why it is so difficult to recruit people from these groups. Could it be that that people with disabilities or from diverse backgrounds won’t fit in or would need more time or resources?
If an effort was made, to create jobs for people from these groups, perhaps people like myself would be more encouraged to apply?
So, if we truly want to be more inclusive, have greater variety in gender, age, ethnicity, social background, sexual orientation, education, religion, and disability then we must change our mindset and resist the temptation to stereotype. Also, if there is a desire to recruit people from these groups, the expectations of what is essential has to be counter balanced with the benefits it would bring.
Not only does it look great for brand, it means there is a greater variety of perspectives, increased creativity, productivity and people feel more included. Recently, I have been to Diversity & Inclusion events and I am keen for these great ideas to be a reality rather than a PR exercise and feel FinTech companies have a massive opportunity to do so.
FinTech companies are already admired with their culture – agile, flexible working, unlimited holidays, day off on your birthday, social events etc. FinTech organisations have a massive opportunity to take the lead in making their workforce a truer and fairer reflection of society.
In order to attract these candidates, we have to change the level of acceptability and I would encourage FinTech’s to take the lead, work with recruiters and create jobs for these minority groups.
How to create a meaningful Employer Value Proposition
Photo by Rebrand Cities from Pexels
Blog written by Puneet Sachdev, Human Capital Expert from Singularity Labs
Note: This is he continuation of the EVP conversation we started here
1. Understand your EVP preferences
Try a top-down and a bottom-up approach. Top-down as in the person responsible for people and culture’ i.e. your people leader and the leadership of the organisation discussing and debating the EVP. Ideally the people leader creates a baseline document / template, circulates it in advance and the leadership gets together to have a conversation around it. And bottom-up as in a listening exercise with your employees. Ask them what they find great about working for your organisation and what can be done to make further improvements.
2. Design your EVP
Gather data from important sources and competitors to inform your EVP design. Use the internal and the external data you have gathered, design your bespoke EVP. Use the five core elements of a robust EVP to structure your proposition. (link to previous article on the core elements of the EVP).
3. Segment the communication
You have the sound bites by now. Here you will think about how this will be communicated to the different types of talent you want to attract into the organisation (engineers, customer service advisors) as different language will appeal to these different mindsets. Think about how you want to communicate this internally. You can consider a video message by the Head of People and some existing employees. And consider using a good copywriter.
4. Create your employer brand
A strong employer brand needs a clear value proposition, which by now you have created. Now is the packaging and positioning. You can use your internal branding team to create this or use the same people you used to help create your organisation’s brand. You can also consider creating a boilerplate’ i.e. your EVP in a tweet and text, in a sentence – strapline, in a paragraph and in a page. Some organisations create well crafted infographics for exhibitions, conferences and other events to promote their brand. Also consider some guiding principles like what L’Oreal has done.
Here is L’Oreal’s: Strapline – “Lead the future of Beauty. When you love your work and the people you work with, amazing things can happen.”
Their employer value proposition is broken down into three pillars:
A thrilling experience ”“ a truly global business with a clear purpose and vision will ensure that candidates can see how they would fit this into their own trajectory
An environment that will inspire you ”“ with the amount of science, corporate social responsibility and sustainable business practices, there will be something to inspire most employees
A school of excellence ”“ world leading brands and products would attract the best people and skills, as a candidate you could be attracted to that environment for your career growth.
This is what Hubspot has – “We’re building a company people love. A company that will stand the test of time, so we invest in our people and optimize for your long-term happiness.”
Suggested channels of communication
- On your careers page
- Intranet website
- Glassdoor
- LinkedIn page
- Social channels used
- Welcome packs
The investment – and if you are thinking about the cost of doing all this work, which you probably are, consider the opportunity cost of not getting all this accurately aligned to the impact it can potentially have on the acquisition of key talent at the different levels in your organisation. If you want to attract A’ players and top on-demand talent, then you want to create an A’ grade EVP. Like attracts like. Here is an article by SAGE People on the impact on Employer Brand on talent acquisition.
Please feel free to get in touch with me if you have any questions or clarifications.
Me and my colleagues at Singularity Labs specialise in designing interventions that solve People and Culture challenges and help creating engaging and High Performing Environments. We have worked across multiple industries and geographies and more recently with growing tech companies such as Nucleus Financial (Fintech) and Craneware (Healthcare Tech). Get in touch with for a no-obligation consultation about your people and culture aspirations.
Employer Value Proposition: your ticket to attracting and retaining top talent
Blog by Puneet Sachdev, Human Capital Expert from Singularity Labs
The Context
The number of innovative fintech SMEs based in Scotland has grown by over 60% from 72 to 119 over the last twelve months. Add to this the explosion of Fintech in London and the ease of workforce mobility, you have a people’ challenge at hand. And this is not withstanding the number of tech companies that are continuing to grow in verticals like digital healthcare, retail etc.
What was inside is now outside. Now, Glassdoor lets any employee publicly rate their CEO, LinkedIn allows your competitors to pillage your top talent, and news outlets regularly publish stories exposing the internal workings of companies. In such a context, the culture of the organisation becomes one of the key sources of competitive advantage.
The Employer Value Proposition
One of the first steps is to get clear on who you are as an employer and your value proposition to potential and existing employees. In HR jargon, you create an Employer Value Proposition (EVP). It is the dating profile’ of your company to attract the right people and then keep the talent you have agonised to acquire. Easier said than done and easily side stepped as soft’ and fuzzy’. Not only does this soft’ and fuzzy’ have a quantified impact on performance but it is powering the growth of organisations. Here is a slightly dated (2016) Deloitte human trends report on culture but the tenants still hold true.
The EVP is the complete experience of working in your organisation. It’s the summarisation of the culture and values you embody, what employees can expect from you – such as learning, career opportunities, benefits, recognition etc. It is the why’ you are creating to attract and retain talent at every level of the organisation. It is the core of your employer brand that defines your positioning, what you stand for as an and the source code for the work environment that you will build internally. Your dating profile!
Gartner says: When you invest in developing and delivering a strong EVP, you can attract significant talent and boost employee engagement. For example, your organisation can reduce the compensation premium by 50% and reach 50% deeper into the labor market when candidates view an EVP as attractive. Organisations that effectively deliver on their EVP can decrease annual employee turnover by just under 70% and increase new hire commitment by nearly 30%’
Here are five main areas to consider as part of developing your employer value proposition. There can be more, but here is what I believe are core:
1.The culture – how things get done in your company. In this guide, you articulate various things about your company for e.g. who you are as an organisation i.e. your vision and mission, your exponential purpose, the journey so far, the team, values, your development philosophy, testimonials from employees, and so much more. You can start with your elevator pitch of why your company matters, and why they should be excited to be a part of it.
Think about this as your illustrated storybook that an employee can read and get a good sense of a) what it’s like to work at your company b) how to integrate themselves into the company in their early days c) behavioural do’s and don’ts guidelines i.e. the code of conduct / values d) what does success look like e) rituals and practices. This should instill pride and inspiration into the hearts of those who read it for the first time or the 100th time.
2. Development Opportunities – a major driver for keeping the workforce motivated, especially the top talent. Here you can include the a) your development philosophy b) skills development opportunities employees have be it access to online learning, events etc. c) career development opportunities i.e. future career options that employees may have with you as you continue to grow e.g. movement from product development to customer success etc.
3. Rewards and Recognition – this will cover the financial and non-financial compensation / benefits as well as the practices you have in place for recognising employees for the great work they do. Here you can think of including a) the competitiveness of your compensation package, health benefits, vacation b) other benefits such as onsite yoga, vouchers for different services etc. c) recognition such as best team performance’, extra miler’, display of organisational values’ etc. d) employee referral scheme if you have one.
4.The Quality of Work – here you define elements that are intrinsically baked into the nature of the work at your organisation, such as a) the ability to innovate on the job b) getting to work on interesting projects c) balancing work with non-work priorities and flexible working / remote working d) whether the work environment is collaborative and team orientated e) the quality and approachability of the company’s management f) the quality of the other employees within the company.
5.Social Impact – the current workforce is getting more and more concerned about the ethical profile of companies they consider working for or are working for. They are concerned about sustainability and employment practices. Social impact or CSR (corporate social responsibility) as it is also known, is now an important aspect of the employer brand. This is worth considering.
At the simplest level companies tend to have VTO’s i.e volunteer time off, create an internal CSR group driven by employees who choose a cause to get behind for the year and then find ways to support the cause. You get as creative with this as you want to. The 2019 Deloitte Human Trends review makes a clear case for the social enterprise
Suggested: what is not often spoken about, but if done right, I believe add to the competitive advantage in attracting the right talent – the explicit communication of Employee Data protection policies and practices. As companies embrace people analytics and AI based applications, a lot more employee data will be generated. And with GDPR growing in its veracity and statutory impact, employees will have greater awareness of data and the mishandling impact. It is worth considering your approach to employee data.
Please feel free to get in touch with me if you have any questions or clarifications.
Me and my colleagues at Singularity Labs specialise in designing interventions that solve People and Culture challenges and help creating engaging and High Performing Environments. We have worked across multiple industries and geographies and more recently with growing tech companies such as Nucleus Financial (Fintech) and Craneware (Healthcare Tech). Get in touch with for a no-obligation consultation about your people and culture aspirations. https://www.linkedin.com/in/puneetsachdevpro/
The Socio-economic Impact of the Adoption of AI in Financial Services
Photo by Markus Spiske temporausch.com from Pexels
Artificial Intelligence (AI) and Robotic Process Automation (RPA) present new approaches to doing business, with potential to trigger innovation and the growth and productivity improvements needed to gain a competitive edge in today’s modern, disruptive, digital economy.
A key change from previous industrial revolutions is that AI goes beyond automation of simple, mechanical, rote tasks to transformation of underlying business models, processes and the legacy technology stacks business increasingly relies on. Further, the scope of AI is increasing, with growing capability to carry out non-deterministic, knowledge-based tasks, as technology rapidly advances.
A number of viewpoints exist on merit for business, the economy and wider society, influenced by differences in understanding and application of the technology, and historical evidence of socio-economic impact of previous industrial revolutions.
Successfully harnessing AI and RPA requires fundamental transformation to legacy systems, models and processes, supported by long-term investment in rare, highly-skilled technology capability and strategic change leaders. Success requires also change to mindsets. This allows implementing organisations to adapt to new, agile ways of working across big data, to gain insight into customers, the market and the wider environment. Evidence shows that market leaders obtain real gains from improved process and risk management, and conversion of insight into effective design and delivery of high-quality, value-added services. An added benefit is organisational reputations that foster trust, aiding customer retention.
At the same time AI and RPA are set to disrupt the workforce with skill-biased technical change. Individuals possessing skills that both complement and support AI technology stand to gain. The agility that accompanies transformation to AI in the workplace augments task completion and supports flexible working practices. Further, because such roles require skills that are both difficult to acquire and require constant updating, such talent is highly sought and highly paid.
At the other end of the spectrum, significant advances in the technology increase potential to substitute digital capital for human labour. To remain relevant individuals must reskill, or risk redundancy or a move to lower-skill, low wage employment.
The resulting skill and income polarisation and potential for significant, long-term unemployment in a growth economy risks further disruption.
The study, for a dissertation for an Executive MBA at Edinburgh University’s Business School, examined the wider socio-economic impact of adoption of AI/RPA, using the financial services sector as a case study, to determine:
- the scenario for changes in roles and skills within the workforce, and
- item potential wider socio-economic impact of adoption.
A mixed methods approach was used, employing, primarily, in-depth interviews with subject matter experts across financial services, technology provision and consulting and advisory roles. The study sought to identify challenges faced in transitioning to the new ways of doing business AI/RPA adoption requires, and to explore different perspectives on formulating strategy to manage the transformation process. Considering both opportunities and threats that the technology poses within the workplace and the wider environment in which the sector exists, the study examined also what other institutions and actions are necessary to prevent socio-economic disruption.
The findings highlight tradeoff between business profit and societal gain.
A number of recommendations were made for formulating strategy for adoption of AI/RPA that lessens the threat of disruption, working instead toward benefit of all stakeholders — business, employees and the wider socio-economic environment.
Key Findings & Recommendations
AI/RPA present opportunities for business transformation that:
- leads to more effective, efficient operations
- fosters innovation that benefits customers, employees and other stakeholders.
AI/RPA pose threat of disruption
- at significant levels to employees whose skills are rendered redundant
- with repercussions beyond the business, that cascade to the wider socio-economic environment.
Current adoption of AI/RPA is typically hindered by:
- sandboxed experimentation that does not harness the full potential of the technology, in what is often seen to be vanity projects
- bolt-ons on incompatible and/or poorly designed technology stacks
- strategy that alienates employees by focusing predominantly on cost-cutting as a means to generate gains for the business and investors.
Successful adoption of AI/RPA however requires:
- alignment of strategic technology transformation with overall organisational strategy
- fundamental transformation of legacy systems, models and processes, along with mindsets
- effective investment and application to real business cases, to enable real return on investment
- long-term investment in human capital, technology and other relevant resources.
It is acknowledged that AI/RPA adoption will transform the workplace and workforce. While gains are clear, there is a risk these are eclipsed by negative consequences within and beyond the business. Responsibility for managing individual impact was seen to lie predominantly with the individual, supported by employers, government, civil society and education.
Strategies for managing the technology transformation start from the premise that business does not exist within a vacuum, nor is it sustainable outside wider society. Further, AI technologies rely on large data stores built using customer and other environmental data. Policy arguments are therefore being made at levels such as the EU to mandate fairer share of gains between business and wider society, through schemes such as digital taxation and the monetisation of data.
Collaboration or at least co-opetition between industry, government, education and R&D is seen to provide a strong base from which to advance AI (and other related) technology to the point where it enables productivity gains that relieve humans to seek new ways of working with technology or other employment, without sacrificing income.
Extending this further is a viewpoint that suggests decoupling leadership from a focus purely on economic gain. This requires moving to visionary thought leadership and strategy that focuses on the long-term and considers alternative, more inclusive metrics for measuring value, and that centres humans within the digital transformation process.
Fintech Fuse – A Festive FinTech Fusion, preparing for 2020!
Just time to fit in a final fusion blog for 2019 before clocking off for 2019 and the festive holiday.
A frantic run in to the festive period has meant I’ve had little time to keep up with a regular blog so please forgive random rambling of the last couple of months!
Festive Community
Very fitting that the festive spirit was very much in the air at the FinTech Scotland Fusion event with the community last week at one of Edinburgh’s most popular fintech hubs, The Green Room!
Wonderful to see so many of fabulous fintech leaders and entrepreneurs join us for a glass of wine or two for the occasion magnificently hosted by special friend Sarah Ronald. Big thanks to the brilliant Stuart, Darren and LendingCrowd team for their generous Christmas hospitality.
A similar uplifting spirt was evident at the Modulr fintech community event the previous month, recognising the terrific progress by the team and the exciting plans ahead. It was super to see so many of the fintech community there for the evening.
The diversity of Scotland fintech community is one of the core strengths and engenders amazing collaboration and innovation.
For example, as shown in the support provided by how the community in getting behind the MoneyMatix crowdfunding exercise recently, inspiring to see.
Furthermore, collaboration boosted by fintechs coming to Scotland from all parts of the world.
For example, meetings over recently with Alex and Monika of Polydigi (Hong Kong), Gopal of BlackArrow , Shendon and Michael of Gobbill as well as Izzy and Paul of Veriluma (all from Australia) reinforce the global make up of the community.
This was a key theme I was able to share in presenting at the FinTech World Forum in London last month to a very diverse global leadership audience which I am told further reinforces Scotland position as an International fintech centre attracting entrepreneurs and innovators.
Meeting our close European partners has also been a key activity over last few months and we are excited to join eight other fintech centres across Europe in the Discovery Collaboration Programme connecting firms with opportunities across our continent.
In addition, it has been great to meet with senior leaders from the French Embassy to talk about collaboration opportunities.
Our ongoing close engagement and friendship with colleagues across our European continent continues to be a key focus in demonstrating to Scotland remains very much open to shared innovation.
Mickael’s ongoing value leadership in building our global FinTech connectivity to support the community in Scotland continues to play an important role.
Alongside this it has been brilliant to work with our super Scottish Development International colleagues to welcome fast growing fintech firms from Hong Kong , Canada, China, Korea all looking at Scotland as a future home for their innovations
Massive thanks to the fabulous Andrew Wykes, Kirsty Russell, Sarah Kenrick and team at Lloyds Banking Group for recently hosting the Hong Kong and Canadian delegations and arranging the festive market to add to the fintech atmosphere in December .
All of this is reflected in the brilliant examples of the FinTech community in the Herald Business supplement a couple of weeks ago. Terrific writing Kim McAllister very much appreciate your engagement and coverage of fintech developments in Scotland.
Kim and I had the opportunity to discuss these developments with other leaders one evening recently at a session organised by Malcolm Buchanan , Mike Crow and the RBS team .
The impactful innovation and leadership by Kristen and the RBS team is hugely valuable to the significant progress and we very much appreciate their ongoing collaboration and support. It is also great to see exciting initiatives such as the exciting Accelerator Hub in central Edinburgh
Festive Collaboration
Collaboration very sits at the heart of innovation progress across Scotland and one of the most memorable examples of this was the recent Glasgow University FinTech Society challenge event, it was also one of my best FinTech Friday’ evenings ever!!
Awesome leadership by Elisabetta, Andrea, Davide and the Society committee bringing together the energetic and diverse students, terrific academic leaders John Finch and Dominic Chalmers, fintech entrepreneurs Sustainably, heavyweights Deloitte and the innovative Chris O’Neill of M3.
Wow, what an evening of fintech, wine, curry and yes a Jazz band with entertaining presentation interlude by the fabulous Lou Smith and a half time fill in by me!!
Back home after midnight with fintech jazz’ ringing in my ears but the evening said everything that is so special about the fintech movement with focus on people and a festive atmosphere.
The festive collaboration was also very much in evident at the FinTech National Network investor pitch day’ at Level 39 in London this week.
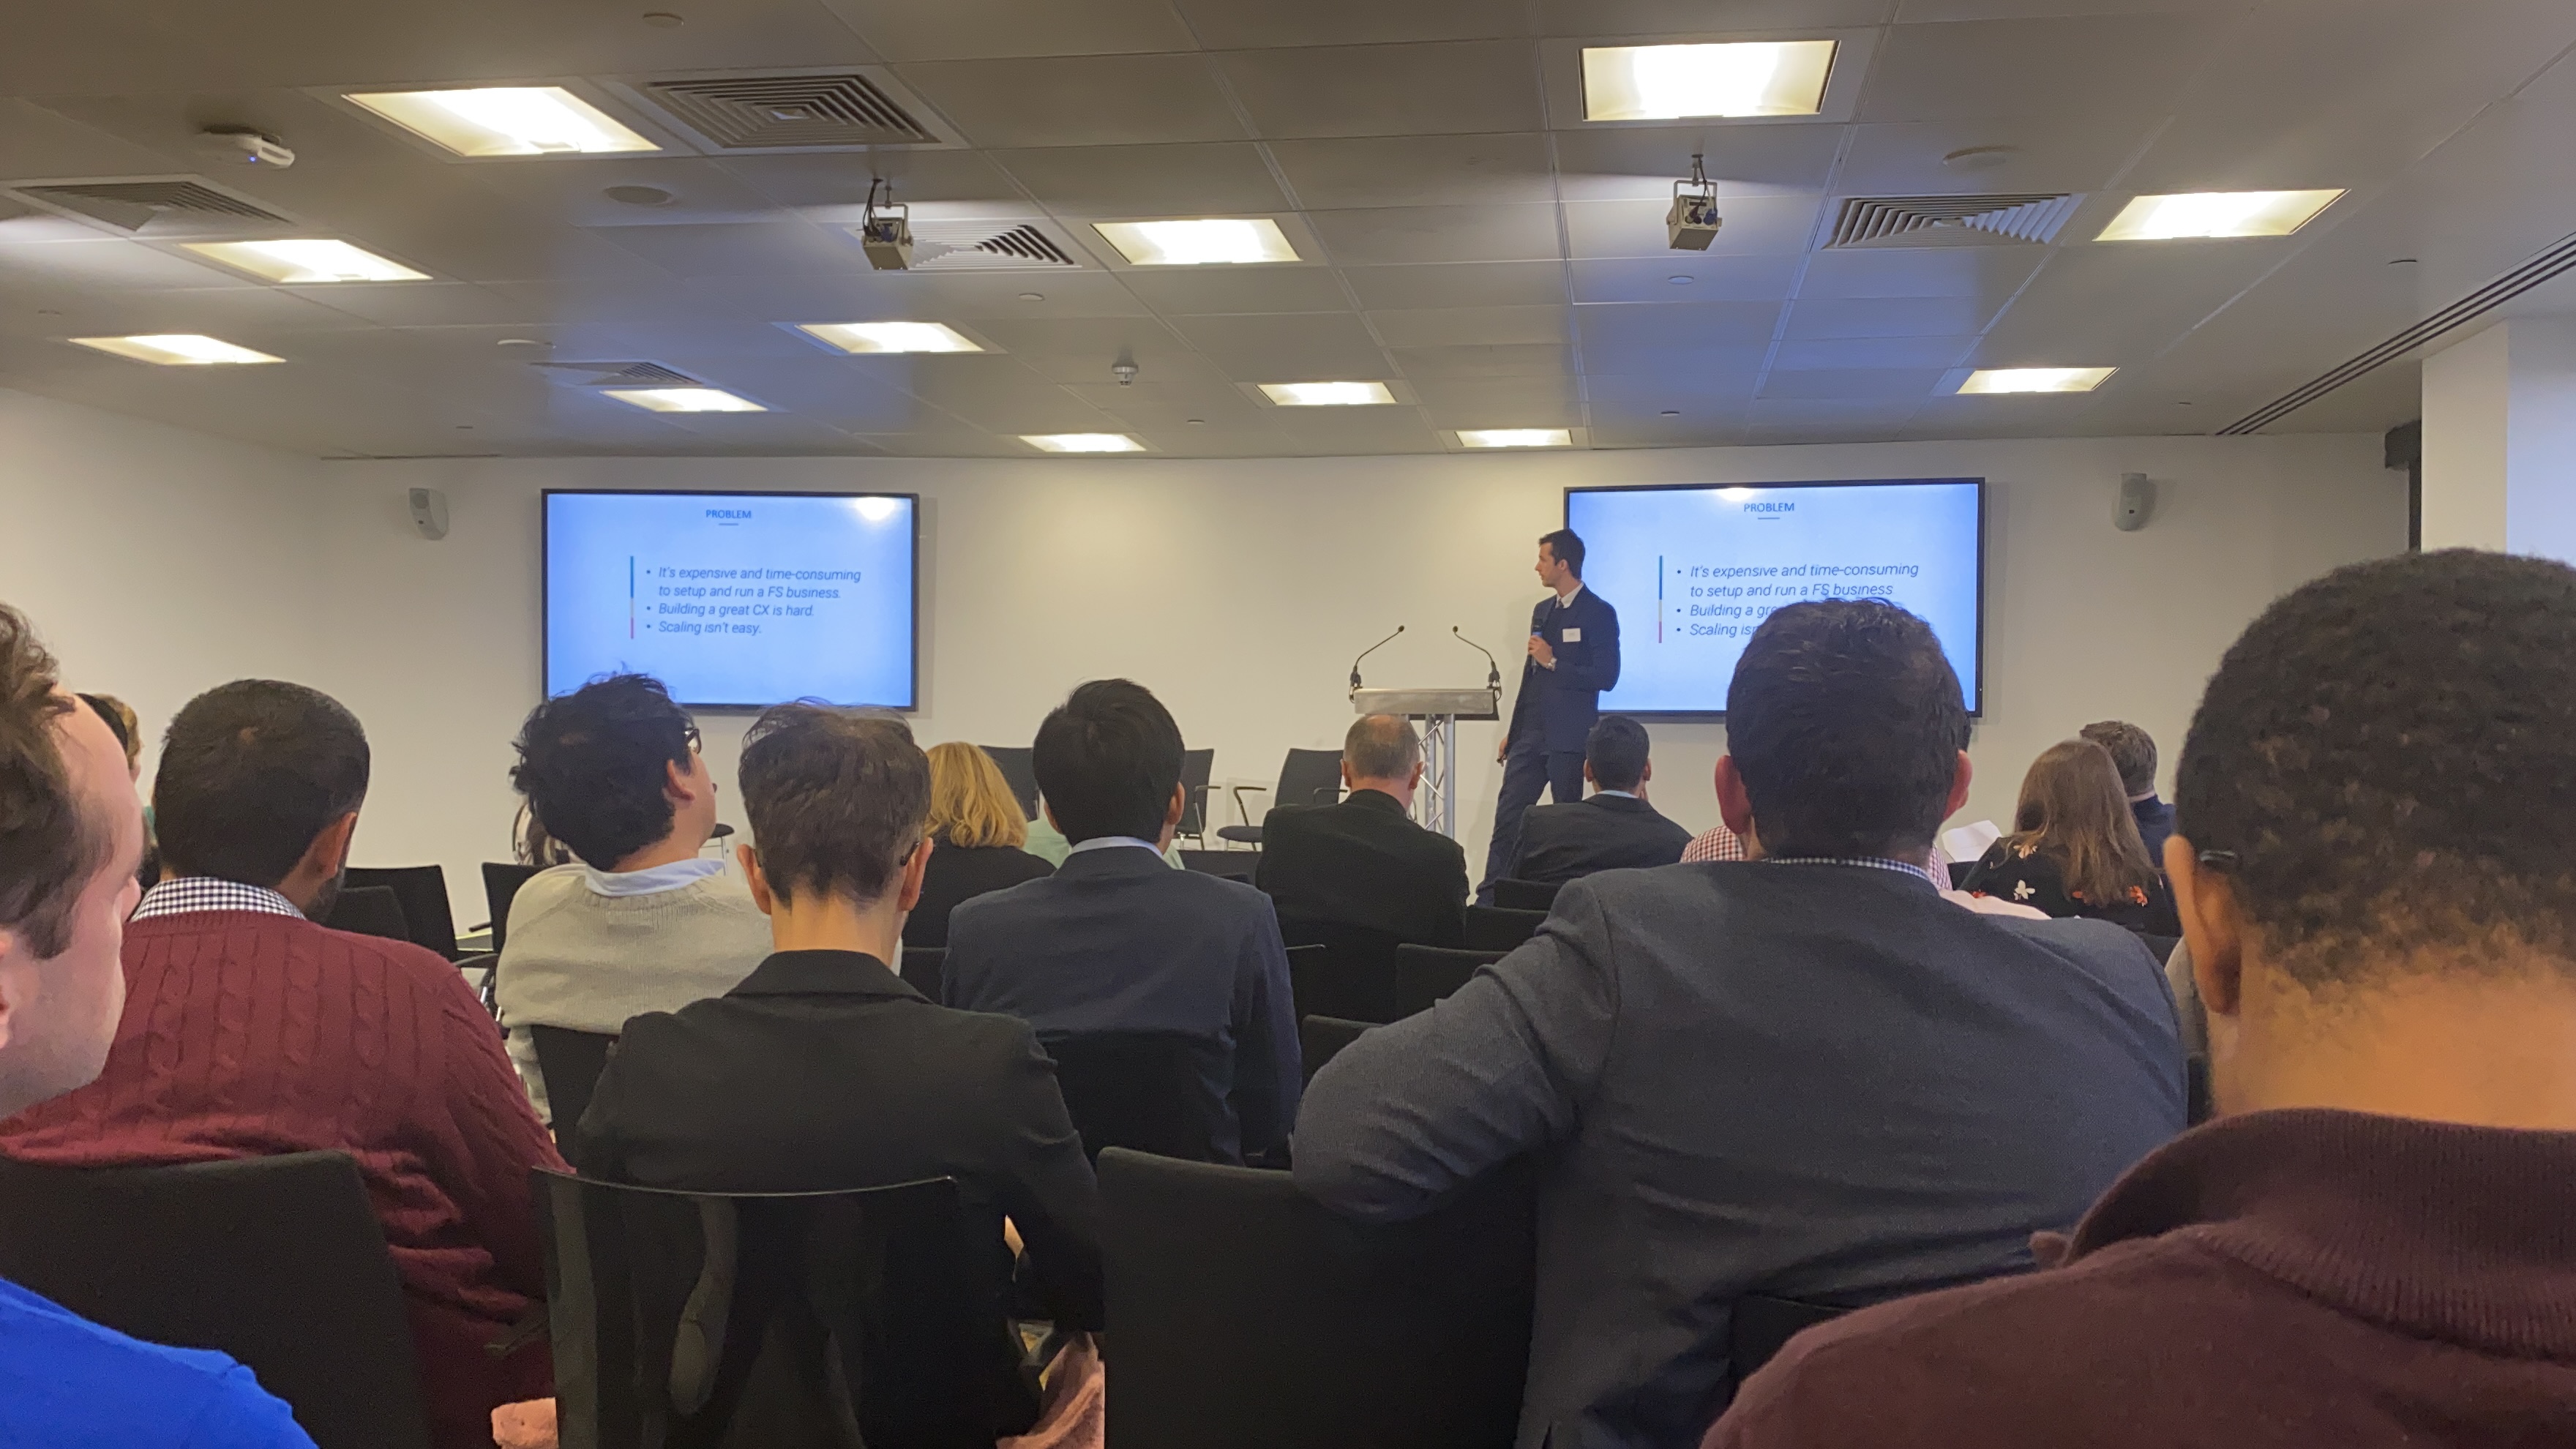
Terrific work by the super Hayley, Peter and the Innovate Finance team in bringing together investors to hear from fintech firms from around the UK. Thank you Charlotte Crosswell for fabulous day, super atmosphere and the ongoing leadership in 2019.
Very proud of the presentations by Nick of Edinburgh based Zumo and Kyle of Glasgow based Financial Cloud in articulating their compelling and innovative fintech propositions
Also, really great to catch up with fintech comrades from Wales, Northern Ireland, North and West as well as Tom Helm from DIT as we all reflected on our shared ambitions for fintech and the collaboration opportunities in 2020.
The investor pitch event followed on from the very first FinTech National Network event in Glasgow back in October.
Bringing together the Scottish fintech community with peers and stakeholders from across the UK was one of the many big highlights for 2019.
The event saw Alex of Encompass, Laura of Amiqus, James of Direct ID and Andrew of Soar from the Scottish community share compelling stories about how they are developing their FinTech proposition to make a real difference.
Also, excellent presentations from the very engaging FCA team Laura Navaratnam and Steven McWhirter as well as Kevin Telford on sharing the impact the world of open finance can have on peoples lives.
Very fitting the event was hosted in the University of Strathclyde which is leading the awesome development of the Glasgow City Innovation District of which fintech is a growing and significant cluster as brilliantly covered by Eleanor Shaw.
Many thanks to the University and City Council for supporting this significant event along with Glynn Robinson and the super team from BJSS team.
Listening to great presentations from Andrew of Northern Ireland, Gavin of Wales , Julian of West and Dan of North on the day reminded us all that we can learn so much from each other as we develop our respective FinTech communities.
The wonderful finale of the day was a focus on people inclusion and diversity with such valuable insights coming from the panel of Lou Smith, Elisabetta from Glasgow University, Laura and Nicola
It was a privilege to co-host the day with my Ant and Dec’ partner, Chris Sier who was as engaging as always in bringing alive the importance of the FinTech innovation for everyone.
I know next year will bring even more wider international collaboration opportunities and it was great to chat this through with Phil, Rory and Isaac of FinTech Alliance over a few glasses on Tuesday evening . Thanks guys, looking to hit the ground running early next year.
Festive Innovation
The run up to the festive period has certainly fueled fintech innovation examples with the community covering a very broad range of themes
For example, it was great to have the inspiring entrepreneurs Phil from Castlight and Manu from Inbest come along to the FinTech Scotland Citizen Panel to share the positive impact of fintech innovation.
The Panel plays a crucial role in identifying how we can collaboratively address issues such as financial inclusion and tackling problem debt amongst citizens working with the third sector, universities, Government and regulator.
A huge thank you to colleague Nicola Anderson for leadership on this area and privilege to work with Nicola and have the secondment to FinTech Scotland extended for another year from the FCA.
More real innovative fintech examples were on show at the University of Edinburgh Business School non executive director course one Thursday evening recently.
This again was a real pleasure for me as I was joined by three absolutely inspiring leaders for the evening to share real life case studies on the leadership needs of growing fintech enterprises.
Many thanks again to the magnificent three, Colin of Float, Sonia of Level E and Aleks of newly formed Exizent for such engaging evening with the senior leaders from across Scotland .
Thank you also to John Amis of the University as well as Ailsa and Judy of FWB Park Brown for the opportunity to put fintech in the non-executive programme for senior leaders.
This week the festive innovation extended to the world of crypto assets and I was very proud to invite three leaders in this field to join me at the Scottish Government Working Group with the Lord Advocate and Lord Hodge.
Fantastic contributions to the discussion on the opportunity by Paul of Zumo, Christine of Women’s Coin, Richard of QWallets , thank you and more to come on this in 2020 especially in demonstrating fintech as a force for good.
This was also very much brought alive during the FinTech session I was invited to host at the Global Ethical Finance Conference at the RBS campus a couple of months ago.
Fantastic examples shared by Georgia of Tumelo and Christine of Women’s Coin on the role of FinTech innovation having an important social impact.
Another area getting some good focus from fintech innovation at present is cyber security and financial crime being led by Nicola.
The joint event recently with Police Scotland and National Crime Agency was very insightful. Many thanks to Leanne of Nucleus, Rachel and Dave of Amiqus and Mike of Modulr for their valuable engagement and leadership on this.
The FinTech collaboration initiatives extend across the public sector and it was brilliant to witness first hand the progress being made in collaboration with the Scottish Government Digital team.
Fantastic to see this demonstrated with Minister Kate Forbes by the fabulous Trish, Hugh, Carron, Mike and terrific teams last week, very much looking forward to the collaboration progress in 2020.
Fintech was very much on show at the CanDo Innovation Summit recently in Glasgow and it was terrific to be part of an amazing event with the other exciting industry clusters driving new initiatives.
The fintech examples were brought alive in the auditorium by Loral and Eishel of Sustainably, Colin of Float and Duncan of Modulr and it was a privilege to host the showcase.
Festive Cluster
The Glasgow fintech cluster is very much going from strength to strength in so many ways and it was great to share the progress with the City Economic Leadership team a few weeks ago, thank you Mark Napier, JP Morgan for the opportunity and continuing collaboration
The action packed FinTech Scotland partnership with University of Strathclyde team is giving valuable momentum to the fintech initiatives and we are really excited about progressing in 2020 as part of the City Innovation District.
Thank you to Eleanor Shaw, David Hillier and terrific team for valuable leadership on this
Building on this with great sessions with innovative leaders Samantha Bedford and Virgin Money team, Tara Foley and Bank of Scotland team, David Ratcliffe, Stuart Brown and Barclays team as well as Ali Law and Paul Gallagher of Royal London provide great new collaboration opportunities for 2020.
Sharing these Scottish fintech developments with a worldwide audience is always on the agenda and it was great to join Alex Ford of Encompass on a podcast along with Lou Smith.
Thank you Cheri Burns for making this happen and the opportunity to share the message. Also, very best wishes to Alex has she moves to New York to expand the Encompass innovation on the other side of the Atlantic.
Of course, the fintech cluster is developing across Scotland and it has been great to work with inspiring Jane Morrison-Ross, chief executive of ScotlandIS along with fabulous Svea, Katy and Ciara on joint initiatives to develop the digital economy. This is a core focus for us in 2020 with much more to come!
The fintech cluster developments require broad collaboration such as with ScotlandIS and Edinburgh Chamber of Commerce who provide valuable leadership in the Scottish economy.
Great working with the super Liz McAreavey, on the Scottish and international opportunity.
In addition, its been fantastic working in collaboration with our colleagues at Scottish Enterprise and the fintech network integrator team, Vivolution, making the Scottish cluster embrace the innovation opportunities.
Working with the University of Edinburgh team on a range of opportunities means the fintech cluster in the capital is going to go from strength to strength in 2020.
The Wayra cohort in Bayes , led by the brilliant Charlotte Waugh is a terrific example of this and it is great to see the progress by James of Xpand and Evangelos of Ocyan
Then wider across Edinburgh, great to catch up with Paul, founder of Inifinity Works who have recently set up in Edinburgh as well as Scott and Raymond from Exception to talk through collaboration opportunities. These are just two examples of many that make life so fascinating in Scotland’s developing fintech sector
We have been running hard to keep up with the fintech momentum across the whole cluster in Scotland and Shery has done an amazing job in keeping us organised between meetings , speaking engagements and project sessions throughout the year.
Festive Running
I’ve also been fortunate enough to maintain my running addiction during this last frantic few months of 2019, infact it seems to have helped my racing performance!
The highlight being the recent Loch Ness Marathon with my best time in nearly three years at 3 hours 16mins which is giving me great hope for my times next year!!
This was followed up a couple of weeks ago with a 1 hour 32mins for the Water of Leith Half Marathon which also left me buzzing.
As with fintech developments in Scotland, if I can keep this race momentum into next year then we could be hitting some new peaks results in 2020!!However, for now it is time to relax and enjoy the festive holidays with my very special family as well as a bit of running around the roads and paths of Scotland whilst having a few small dreams on what the year ahead will bring. Until then…..
Financial wellbeing and the impact in the workplace
Photo by energepic.com from Pexels
Financial wellbeing ”“ the theme of Talk Money Talk Pensions Week 2019 ”“ is about feeling secure and in control of your money as well as being able to manage day-to-day while working towards a healthy financial future. We think it’s important to not only consider how individuals can build their own financial resilience wellbeing but also how employers can support their staff in developing lasting financial capability strategies.
A recent report from Natwest (https://www.moneyadvicescotland.org.uk/Handlers/Download.ashx?IDMF=f4148ec3-ec0e-468b-ae07-7f615fc34548) recommends that employers should, at a minimum, include financial capability training and support as a standard part of their employee induction process, and a growing body of evidence shows that there are clear benefits of investing in this for all employees at all stages of their career. The importance of financial education at work and the benefits it has for both employees and employers is why we developed Money Works ”“ a programme that exists to promote financial wellbeing in the workplace and provide vital financial inclusion skills for employees and apprentices across Scotland.
Research has found that levels of financial capability and wellbeing very greatly from person to person. An individual’s salary, age, or employment history does not necessarily correlate to their confidence or ability to manage their earnings or their state of financial wellbeing. It therefore makes sense to offer financial wellbeing support to all employees.
The arguments for providing financial wellbeing support in the workplace are strong; firstly, the impact of poor financial wellbeing on productivity is significant. Anxiety about finances leads to worse mental, physical, and social wellbeing which can affect attendance and performance at work. The Chartered Institute of Personnel and Development found that money worries were the biggest source of stress for UK employees.
According to research from Barclays:
-Almost half of employees worry about their finances
-1 in 5 lose sleep worrying about their finances
-1 in 5 said that worrying about their finances affects their work
-Almost 80% of employees are not satisfied with the efforts of their employer when it comes to managing their finances
This evidence shows how great an impact an individual’s financial wellbeing has on their overall wellbeing, and how intrinsically linked money worries and work are. Both employers and employees agree that if employees had access to help and guidance, they would have better control over their money and feel better prepared for future planning. If this support is available in the workplace, employers can help ensure their staff are better prepared to respond to financial unpredictability, in turn alleviating some of the pressure points that lead to absence and stress.
One of the aims of Money Works is to provide a reliable, flexible source of financial guidance. Participation in our financial wellbeing in the workplace sessions benefits both employees and employers. Employees gain vital financial resilience skills and get access to resources that research shows is needed and wanted. Employers benefit from a more motivated and productive workforce, as well as highlighting them as an employer that is committed to investing in employees’ overall wellbeing.
Our Financial Capability team designs custom workshops and works with employers to meet the needs of their staff, and workshops are delivered in the workplace.
Possible topics include:
-Planning for retirement
-Day-to-day financial management
-In-work benefits
-Savings (including emergency funds, ISAs, saving for a deposit)
-Insurance (including life insurance)
-Managing credit card debt
-Understanding taxes and payslips
These topics are based on research of what employees would benefit from knowing more about. For example, 22 million working-age adults don’t feel that they know enough about pensions to make decisions about saving for retirement, so we offer sessions on this.
If you’d like to learn more about Money Works, contact financialcapability@moneyadvicescotland.org.uk or complete this form https://www.moneyadvicescotland.org.uk/forms/money-works-enquiry
Can diversity lead to better recruitment and retention?
Photo by Helena Lopes from Pexels
The challenges for growing Fintech’s in recruiting and retaining top talent in the face of larger firms with greater resources is well documented. This is particularly true in the main Scottish tech hubs of Glasgow and Edinburgh and with more large firms investing in new and expanded bases in the area this trend is likely to continue, so smaller, less well known firms with lower budgets really need to leave no stone unturned when it comes to seeking talent.
The main advantage smaller firms have is being nimble ”“ the ability to adapt hiring processes and to respond to market and candidate needs more quickly than their larger competitors. In this blog I provide some thoughts on diversity in the workplace and practical steps that can be taken.
I have attended numerous events and read countless articles on the benefits of improved diversity within workplaces. I hear the same things over and over as if employers still need to be convinced of the fact that more a more diverse workforce leads to greater creativity, innovation, staff retention and ultimately improved profitability.
It is my belief that employers do understand this. We need to move the dialogue on to the next step ”“ what should firms do about it? It’s a huge topic ranging across diversity in gender, age, disability, ethnicity, neurodiversity etc., and it can feel a bit overwhelming particularly for small to medium companies who may not have the resources that larger companies can lend to the topic.
If it seems daunting as a whole, break it down into manageable steps and prioritise these. Thinking about the stages where diversity plays a part, the biggest of these is probably recruitment as this is where the source of your diverse talent will come from. Breaking this down further how do you ensure you attract applications from the most diverse range of candidates then how do you ensure your selection process is fair to all?
Job Design
Consider what is actually essential for this hire and what can be taught once in post. What could be offered in terms of flexible working, part-time hours, agile working etc? What adjustments could be made for neuro diverse candidates?
Candidate Attraction
If your job design is done well this should automatically lead to a job advertisement which will attract a wider pool of applicants. Also check that the words used in your advertisement don’t accidentally appeal more to a particular gender, there are online tools to assist with this. Now consider how to actively target a wider pool of talent i.e. taking your roles directly to them rather than simply hoping they will find them e.g. where could the advert be placed?
Return to Work Candidates
There has been a rise in the number of returner programme in UK from 4 in 2014 to 70+ in 2019. These are for candidates who have a had a career break of one year or more and are looking to return to the workplace. Research shows that the biggest barrier for them is often loss of confidence so however appealing your job advertisement they still may not apply to you.
The Back in Business returner programme offers workshops to the candidates to help them regain that confidence and get them work ready. We will also consult with your firm to help design a “returnship” opportunity to ensure a manged return to work which more often than not will lead to a permanent hire for your business. Returner candidates tend to prove to be mature, established and loyal which is not always the case with regular hires.
Selection Process
Consider what steps you can take to anonymise applications e.g. removing name, age, gender etc., from CVs before they are passed to hiring managers. Unconscious bias training should be compulsory for all interviewers. Review any assessments being used for ”“ could they disadvantage any groups of candidates?
Back in Business is a diversity led recruitment service which offers returner programmes in Scotland and can also support with each of the other steps mentioned above.
Blog written by Morna Ronnie, Head of Programmes at Back in Business
Cryptoassets businesses and Money Laundering Regulations
From January 2020 the FCA will be the UK supervisor for cryptoasset businesses in respect of Anti-Money Laundering and Counter Terrorist Financing, under amended Money Laundering Regulations (MLRs).
Cryptoassets are developing change connected to the financial services sector.
Both the concept, and the underpinning distributed ledger technology are attracting significant attention and the UK Government established a Cryptoassets Taskforce in 2018 as part of its FinTech Sector Strategy.
The Taskforce published its final report in October 2018, providing an overview of its perspective on the subject, including the underlying technology, the associated risks, potential benefits and a way forward with respect to regulation in the UK.
In reaching conclusions the Taskforce outlined the need for action to mitigate the risks for consumer harm, prevent the use of cryptoasset for illicit activity and guard against threats to financial stability that could emerge in the future.
It’s report sets out three broad types of cryptoassets and typical uses, which together help establish a framework for considering the impact, potential risks and need for regulation.
In setting out its role the FCA has specified a range of Cryptoasset activities that are captured under the new regime and businesses conducting these activities will be required to comply with the MLRs.
The businesses include existing financial institutions that offer the option to convert cryptoassets to fiat (government issued currency), or accept cryptoassets as collateral against a loan or purchase.
The regime will also apply to new businesses and developing business models such as peer to peer providers, digital wallet providers offering a crypto service such as exchange or custodian services, Cryptoasset ATM’s, and issuers of cryptoassets.
Fintech innovators are taking advantage of the growing cryptoasset trend. Some are aiming to make crypto work seamlessly with traditional currencies by developing technology capability that will enable cryptoassets such as Bitcoin to convert to fiat money. It presents new opportunities and challenges for many and is another developing example of the potential directional change digital will bring to financial services.
All impacted businesses will be expected to comply with the MLRs in relation to cryptoasset activities by 10 January 2020. The expectations include the ability to demonstrate that each business has thought about the respective nature, scale and complexity of its activities and the associated risks. Businesses also need to have the appropriate controls in place to mitigate risks and will be expected to keep these under review and regularly assessed to ensure they remain fit for purpose and relevant.
In setting out its responsibilities and the approach it will take to this work the FCA has signposted firms to a number of existing resources to help build an understanding of its expectations when it comes to managing financial crime risks.
These include the FCA’s Financial Crime Guide: to countering financial crime risks, the Joint Money Laundering Steering Group (JMLSG) website, and recommendations from The Financial Action Task Force (FATF) an inter-governmental and global body. Further detail on the FCA’s approach can be found here.
Liberation: Banking
So, if you’ve been following the news lately you probably have heard PSD2’ and Open Banking’ mentioned at least a couple of times.
There’s a lot of fuss going on about them and we wanted to prepare all that we could find into a short article to get you up to date.
What is PSD2?
PSD2, formally referred to as the Second Payment Services Directive, is a regulation that covers the entire European Economic Zone.
PSD2 has been on the radar of European economies since 2015. It’s a major step towards keeping up with the rapid digitalization of the commerce industry.
PSD2 aims at making online payments more secure through various regulations that make online fraud much more difficult and third parties more accountable.
If you are remotely interested in finance and fintech you probably know all of these already. In case you have no idea what PSD2 is, you can check this comprehensive guide about the PSD2 regulation.
Other than regulating and securing the way online payments are done, PSD2 actually has paved the way for one of the biggest finance experiments ever.
What is Open Banking and Why Should I Care?
Open Banking is a gigantic experiment that is set to liberating the banking sector by returning the control of financial data to consumers.
This is possible thanks to a small detail that was introduced with PSD2. PSD2 allows third-party financial services to access banking data easier and more secure.
A bit of a history lesson here. Personal finance solutions aren’t something new and there are many successful companies that have provided such services. However, what they lacked was a consistent and secure way of getting access to the financial data of consumers.
The widespread method that these solutions relied on was named as screenscraping. When using third-party financial assistants, users would provide their username and passwords to the third-party software and the software would periodically login into the bank accounts and save the screen of the account information.
Based on the data they gathered, they would give suggestions to the user on how to better spend their money.
As you can guess, screen scraping wasn’t the most consistent or safe method of gathering user data. After all, who would feel safe sharing their banking credentials to someone else? On top of that, if you were using multiple banks you wouldn’t have a complete picture of your finances.
This is where PSD2 promises a safer and better ecosystem for third-party financial services to thrive.
In addition to making online payments safer, PSD2 also has provisions that aim at liberating banking data. Traditionally, your financial data (how much you spend, where you spend, what you but, etc.) was kept safe by banks. Now, to be honest, banks have historically done a great job of protecting their clients’ financial data.
The only problem here is that the data does not belong to the banks. It belongs to the consumers who normally have almost zero control over how the data is utilized.
With PSD2, banks will still be the keepers of the data. But, they are forced to share the data with verified third-party services only when requested by the user. This will be done through an Application Programming Interface (API). So, you won’t share your password with anyone and your data will be provided from a safer and more reliable channel.
Even better, you get to decide which data points will be shared. An option that was previously impossible through screen scraping.
By default, you shouldn’t care too much about Open Banking unless you’re relying on 3rd party financial service providers.
Is Open Banking Good?
On paper? Yes.
However, we still don’t know how things will play out.
The main idea of Open Banking is that it will transform the banking sector in such a way that it will become more competitive and innovative.
By giving control of the data back to the consumers and lowering the barriers to entry drastically, open banking is expected to force banks to innovate and adapt to the digital realities of our time.
The lower barriers of entry might make banking more competitive which should force banks to improve the quality of their services and also constantly innovate. At least that’s the assumption.
More actors, more transparent banking, better services, constant innovation. This is what awaits us if Open Banking will succeed.
Let’s not get ahead of ourselves for a second here.
All of these sound great but Open Banking is an enabler and not a proposition in itself. It is what companies do with Open Banking that will make it a success or not.
It’s true that competition fosters innovation but we need to ensure that innovation only happens to benefit customers and/or clients.
If customers don’t understand the value they’re getting back they won’t share their data and Open Banking will fail.
Author Name: Su Kaygun Sayran
Author Bio: Grown up in various corners of the world, Su loves writing about all things tech. His experience with various SaaS businesses has enabled him to carry his passion for writing into the tech industry.