
High confidence in Glasgow’s regional tech sector
Startups and scaleups in the Glasgow City Region are experiencing remarkable growth in venture capital investments, surpassing many of Europe’s prominent and emerging ecosystems.
The Glasgow City Region Tech Ecosystem currently holds an enterprise value of £3.4 billion, marking an impressive 89% increase since 2018.
This positive economic performance has attracted a wave of enthusiastic investors and entrepreneurs. The encouraging news stems from a report published by Dealroom.co on behalf of Glasgow City Council’s Digital Economy team, released on Wednesday, May 24, 2023.
Leading the charge in this emerging ecosystem are regional clusters focusing on healthtech, precision medicine, net zero/climate technologies, space, fintech, advanced manufacturing, and the digital and creative economy.
Councillor Susan Aitken, Leader of Glasgow City Council, stated,
“Glasgow’s reputation for innovation, invention, and ambition continues to shape the city, and this report by Dealroom demonstrates that we are attracting new businesses and entrepreneurs throughout the region. This confidence in our city as a business hub is generating numerous specialised, high-value jobs across Glasgow.”
Dealroom.co, a global data platform, diligently tracks the performance of regional tech businesses, ranging from startups to high-growth companies and their associated investments.
Glasgow City Council announced its collaboration with Dealroom six months ago during the 24th State of the City Conference. At the conference, they unveiled the Glasgow City Region Tech Ecosystem Platform, the UK’s first standalone regional Dealroom platform designed to support local government, academia, and other public-private agencies.
This platform highlights the value of in-depth analysis of startups, scaleups, and innovation assets headquartered, founded, or significantly present in Glasgow. It provides reliable data crucial for entrepreneurs, potential investors, and facilitators operating in or considering entry into the Glasgow marketplace.
Additionally, the platform offers all startups and scaleups a valuable and free, open-source business platform and profile. Meanwhile, the data they contribute aids in shaping the overall growth landscape of Glasgow’s tech ecosystem.
Key findings from the recently published inaugural annual report include:
- Startups in the Glasgow metropolitan area continue to attract increasing levels of investment, showcasing an 8% growth over the past 12 months. This growth stands in contrast to many leading and emerging ecosystems across Europe.
- Startups in the Health, Energy, Real Estate, Fintech, and Semiconductors industries have secured nearly two-thirds of the total investment rounds in Glasgow over the past five years. Notable companies benefiting from these investments include EnteroBiotix, HVS, arbnco, AlbaCo, and M Squared Lasers.
- The first quarter of 2023 marked Glasgow City Region’s third-highest venture capital investment period on record. Noteworthy investments since the beginning of the year include companies such as Phlo Technologies, Causeway Therapeutics, DxCover, and IbisVision.
- Research conducted in city regional universities has led to the creation of over 100 spinout companies. Solasta Bio, Krucial, and Novosound are among the regional companies contributing to this achievement.
- This growth has generated more than 1,000 jobs and has inspired a new wave of entrepreneurial graduates to pursue careers in startups.
Anne McLister, Head of Digital Economy, commented,
“As Scotland’s largest city, Glasgow offers tremendous business appeal, boasting abundant talent and collaborative networks within our thriving tech and creative communities. Our emerging tech ecosystem benefits from the resources provided by renowned higher and further education institutions, including a highly educated pool of individuals with strong research and innovation capabilities.”
Glasgow’s three distinct university-anchored Innovation Districts underscore the region’s unparalleled allure as an attractive, high-quality, and cost-effective living environment for entrepreneurs and startups.
Standards for Innovation: Mapping the global financial landscape in Open Banking
The expansion of Open Banking across the globe has led to a burst of innovation within financial products, leading to improved customer money management where consumers give access, and consent to their data being used. The opportunities to transform the economy and society are even greater with more countries embracing Open Finance and putting in place a secure data-sharing infrastructure across multiple industries and not just banking.
With Open Banking initiatives gaining momentum around the world, a range of different standards are emerging. Smart Data Foundry and Ozone API have collaborated to develop the Standards Library and Innovation Atlas, outlining the features and similarities between different standards being set across the globe. Beyond a general desire to drive innovative outcomes, not all standards are designed with the same intentions in mind. As nations look to allow API access to customer-consented data, it’s clear that the main drivers may differ, from competition and inclusion to stability or innovation.
For the UK, with its ground-breaking Open Banking Standard, increasing competition was key. The Competition and Markets Authority’s (CMA) 2016 report found that big banks dominated the market and wanted consumers to benefit from introducing other players. Has the mandating of Open Banking worked to achieve this in the UK? The FCA reported in 2022 that large banks’ historic advantages were starting to weaken, in part due to digital innovation.
As well as increasing competition, Open Banking’s other advantages are consumer based- such as increasing the ease of charitable spending and financial decision-making.
So how do the main objectives of other standards vary?
Countries with financial inclusion in mind in their Open Banking regimes, such as Brazil, Mexico or Indonesia, look to embrace a broader scope of data exchange and invite new participants into the regime to ensure a greater diversity of products and services for the financially vulnerable.
From the outset, Banco Central do Brasil’s goals aimed for a more inclusive and competitive business environment’, highlighting the promotion of financial citizenship as one of their four objectives. Also listed were encouraging innovation, promoting competition and increasing the efficiency of the National Financial System and the Brazilian Payment System. From the outset, a broad range of products were included in their standards to tackle these objectives.
The Open Banking move for India was part of a bigger infrastructure build called India Stack, encapsulating a digital identity infrastructure, a digital documents system, a payments system (UPI) and the account aggregator framework. This was part of a massive digital overhaul of the management of the economy, with paperwork dominant, to address financial inclusion. Cross-border interoperability, particularly for remittance payments, is another target being addressed by the nation.
Financial access is a top priority in Mexico for the government, whose Fintech Law was enacted in 2018. However, regulated Open Banking is not yet a reality, but with a FinTech ecosystem growing rapidly and it being a hotbed of software engineering talent, Mexico will be one to watch when Open Banking does come into force.
Finally, in the Kingdom of Saudi Arabia, Open Banking has been driven as a pillar of the ambitious vision for Saudi 2030. Open Banking and Open Finance are key enablers in transforming the financial services sector, economy, and society.
As Open Banking standard frameworks are developed globally, it allows for innovative products to spread across borders. Smart Data Foundry’s aizle synthetic data engine looks to drive innovation and produces Open Banking compliant synthetic data. Ozone API provides compliant open API technology to monetize Open Banking globally. The global environment for applying APIs and synthetic data can be understood with Standards for Innovation.
Learn more about the global financial landscape by exploring Smart Data Foundry’s”¯Standards for Innovation.
Written by Magdalena Getler and Lucy Lloyd (Smart Data Foundry), Huw Davies, Chris Michael (Ozone API)
Going global? 3 MUST DO’s when assessing new markets for expansion and growth
Blog written by Greg Watts, CEO at Findr
You’ve established yourself in your first market, and now looking to expand to new ones.
When assessing new markets, what characteristics should companies look for and how should they prioritise them?
What makes a good’ market and what makes for a risky one?
In this article, we’ll look at three key considerations for any business looking to enter new markets.
1) Assess the landscape
Do you know how many fintechs actively operate in the UK vs other markets across Europe?
In 2019, Demand Creation Partners undertook an assessment of the fintech landscape in Western Europe. It found that out of a pool of 7,200 companies, nearly 3,000 ”“ or 41% of the total ”“ are active in the UK.
Further, the data shows that 81% of all fintechs in Western Europe actively operate in just eight countries. This is illustrated in the breakdown below.
You can now start to get a picture of how the region is constructed, allowing you to make an initial assessment of the suitability of different markets.
It may make sense to target a market with less competition and potentially lower barriers to entry to create a compelling use case for future growth.
2) Identify your launch criteria
When considering options for expansion, it can be tempting to start with larger, more mature markets such as the UK or US.
Despite leaving the EU, the UK remains the leading fintech market in Europe, accounting for half the region’s VC deals ”” for example, the $80 million funding of BitFury and $110 million funding of Monzo.
However, even with significant investment, the UK can be a hard market to crack.
It’s mature, with just over half of all payments made via card. And even though the US and UK share the same language, there are subtle cultural differences which must be understood before engaging potential partners or signing up users.
To assess your chances of success in a particular market, it’s important to research and weigh up your launch criteria, such as:
- Macroeconomic factors including GDP, economic performance and availability of government incentives.
- Competitive landscape ”“ How many other fintechs operate locally? How do they differ from you? Do you offer a compelling advantage?
- Barriers to entry ”“ Are these high or low? How will local legislation or regulation impact your launch?
- Structure of the local retail and payments market ”“ Is it comprised of home-grown players you’ll need to establish partnerships with or global organisations with which you already have relationships?
- Consumer behaviours and indicators, such as penetration of mobile phones and percentage of cash versus digital payments.
Knowing where you stand vis-Ã -vis these criteria will help you to realistically gauge and prioritize which markets to invest in.
3) Undertake a detailed market assessment
Now that you’ve prioritised your launch market(s), the next step is to undertake detailed assessments of each.
A market assessment is a comprehensive analysis of market trends, entry barriers, regulatory requirements, competition, risks, opportunities and available company resources. Whether you’re thinking of venturing into a new market or launching a new product, conducting a marketing assessment is a critical step in determining if there is a need or customer base for your product.
A well-executed market assessment will enable you to decide where to apply resources for the best return.
4) Develop a go-to-market plan
Now that you’ve prepared your market assessment, the next step is to develop a go-to-market plan to ensure successful entry. Some key considerations include:
- Access to local talent is crucial. Recruit leaders and sales and marketing personnel with a thorough understanding of the market. Be aware, however, that securing the best people can be difficult for a lesser-known brand, so think carefully about your resourcing strategy. In the short term ”“ while momentum is being built and resources are constrained ”“ you can support functions such as product, legal, operations and technology from HQ.
- Identify local partners who can help you raise awareness and introduce you to prospects ”“ for example, chambers of commerce, payment associations or retail consortiums. Who are the banks, acquirers, PSPs and retailers you need to cultivate relationships with? Can you leverage existing relationships? Choosing partners with a presence in your target markets will save you a lot of time.
- Differentiate yourself from local players. Understand local issues and market nuances and develop a proposition that resonates. Ask local experts to review your collateral to ensure your messages are relevant and cannot be misinterpreted through subtleties of language.
- Create an integrated demand generation plan to qualify opportunities for the sales team such as must-attend events where you can build relationships with target clients and partners.
- Identify a local PR agency to support your launch and develop a map of local influencers to form relationships with ”“ for example, journalists, bankers and retailers.
Bringing it all together
When assessing markets for expansion, it can be tempting to prioritise more mature countries such as the UK or the US ”“ particularly when you’re under pressure from investors.
However, these markets often have higher barriers to entry, making them harder to crack.
The goal for any fintech must be to create one or more use cases that prove a solution works; that there’s genuine demand for it; and ultimately, that customers will use it. In order to create these success stories it may make sense to prioritise markets with lower barriers to entry, where the chances of success are higher.
Taking the time to identify criteria for market entry will allow you to focus your resources more effectively and accelerate your plans for growth.
Photo by fauxels: https://www.pexels.com/photo/photo-of-person-using-laptop-3183174/
Stories from female fintech entrepreneurs
To celebrate International Women’s Day 2023, we met with two female fintech entrepreneurs to hear about their stories, why they chose to become fintech leaders, their successes and challenges.
Ana Gallacher, founder of BabyReady Finance
Sheila Hogan, CEO and founder of Biscuit Tin
I am Sheila Hogan CEO and Founder of Biscuit Tin a “death-tech” SaaS business – we make life admin easier for you now and easier for those you love in the future by helping you create a digital legacy to be proud of. Biscuit Tin is a digital secure vault holding all your life information that is released to those you nominate when you die, providing them with the direction they need to easily and effectively close down your life and a digital biography of your life to hand down the generations.
I had an entrepreneurial flair from a young age ”“ from making pencil cases that I sold to my school mates, Pencil skirts with my own , clothes label ItFitz and I tried everything to make money ”¦ every party plan going. I left School at 16 and went into Tech as I had a feeling it was a thing of the future. I started at Bradford Council as a Junior Computer Officer, I then went to study Computer Studies part-time at Huddersfield Uni.
A Programmer in the early days, I progressed onto analysis project & programme management and up to creating Biscuit Tin I was a Consultant Business Architect designing the way businesses need to operate to leverage technology. Predominantly for large financial services institutions.
The challenges I faced before Biscuit Tin were mainly my own making ”“ always looking for the next thing’ and trying to find my niche and the career I felt destined for. It appeared after closing down the lives of both of my parents armed with a physical Biscuit Tin of old papers. The two worlds of my professional technology career and personal experience collided as I realised that the life close-down’ process is completely broken and needs to change.
It seems many of my challenges since then have revolved around money ”“ from bootstrapping, winning grants and investing what I could from my pension to get the business off the ground. To the challenges of raising capital I face now to forge ahead to scale-up and deliver to our mission to make a difference in this space and be a global Digital Legacy leader within 5 years.
Pathways: A New Approach for Women in Entrepreneurship
Last week, the Scottish Government published Pathways: A New Approach for Women in Entrepreneurship. This landmark report was overseen by tech entrepreneur Ana Stewart and the Scottish government’s chief entrepreneurial adviser Mark Logan, and was commissioned to help identify ways to unlock untapped potential, close the gender gap and boost Scotland’s economy.
We met with John Cushing, CEO and founder of mnAi, who provided detailed data analysis for the report.
The report “seeks to change how we think about the under-participation of women in entrepreneurship, to more rapidly and effectively move our society away from its current extreme gender imbalance in this field of endeavour.”
Startups founded by women in Scotland currently receive only 2% of overall investment capital, representing, the report states, a “denial of opportunity on an industrial scale”.
Just how significant is the report, and its findings?
“It’s the most comprehensive report of female entrepreneurism ever undertaken in Scotland,” says John Cushing.
mnAi use proprietary data and technology to supply unique research, analytics and insight on all UK companies.
“The Stewart Report lays bare the fact that fundamentally things just aren’t moving on as fast as they should be,” says Cushing.
“This is in spite of some amazing achievements by female entrepreneurs in and across Scotland – much more needs to be done to support their ambitions, particularly growth stage companies and those seeking investment. The report not only lays bare the problem, but also identifies the solution. That’s the critical part of all of this, that the Pathways Report actually does exactly what it says ”“ it lays a pathway to success.”
“With 12bn+ data points, our core product is a data asset encompassing 9m+ UK companies and 37m+ people that is updated and refreshed in real-time,” Cushing says. “Our unique insight on hard-to-find data points including emissions, diversity, gender, productivity, investment, debt, grants, financials and more, helps improve decision making, increases efficiency and removes complexity. Having learned about our gender disaggregated algorithms and the work we did with the 2022 Rose Review and The Gender Index, Ana and her team extended an invite to also support her ground-breaking research.”
The report makes 31 recommendations such as tailored funding packages, attention to diversity in education, and quotas to ensure women get proper recognition and a fair share of investment.
First Minister Nicola Sturgeon described the list of recommendations as “compelling”, adding: “The review’s findings are challenging but underline the need to tackle the root-causes, as well as the immediate barriers, of this inequality ”¦ The Scottish Government will respond quickly to the review as a whole, and its recommendations.”
Despite the progress made in some areas there is work to be done.
“I’m very confident that things will change… however this is a collective issue,” says Cushing.
“From secondary education to investment capital, I think we all have a responsibility to support those in need or who need help. Being a business owner is not easy, and yet many people choose to do it day in, day out so why should my gender make a difference to my ability to grow my company? It shouldn’t. This report presents the facts and now it’s up to all of us to make a difference.”
For more information about mnAi’s data platform, and to book a free interactive demo, click here
Open Banking – the UK’s next biggest export?
According to Accenture, there’s $416bn of revenue at stake for fintechs and banks across the world by the end of this decade. That’s roughly four times the size of the scotch whisky market ($91bn) – so is Open Banking the UK’s next iconic export? Maybe”¦ but only if we make some important changes
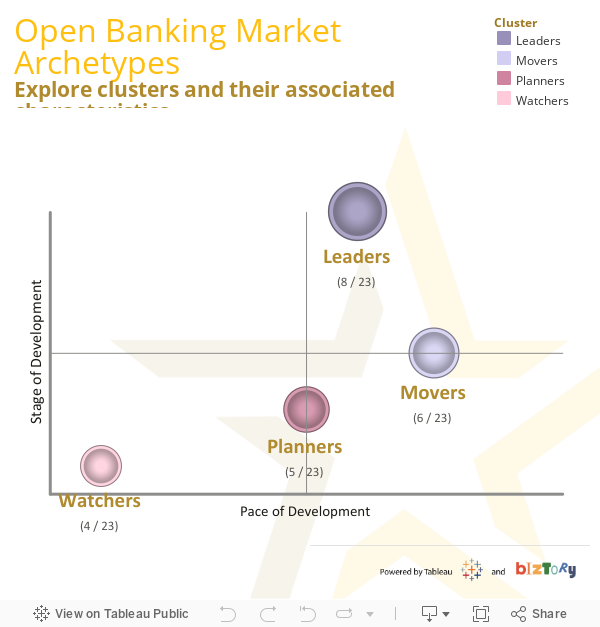
Last week, we released a piece of research – The Global Open Finance Index. It tracks the development of Open Banking across the world and focuses on the 23 countries where we’re seeing the most progress. Its findings are fairly stark. The UK’s position as a leader in the space, which was once completely uncontested, is now in serious danger of evaporating.
Countries like Brazil and Australia are accelerating with regulatory regimes that already go far beyond the UK’s initial blueprint whilst markets like India and the US are finding different approaches leveraging market forces and industry collaboration to create huge potential. India’s Open Banking standard now covers a group of more than 1 billion accounts whilst in the US 42 million accounts have coalesced under the FDX standard with zero regulatory push. Perhaps even more significantly, that regulatory push is coming in the US and soon. The Consumer Federal Protection Bureau (CFPB) is already in the late stages of consultation on how that process should be rolled out and they have the legislative backing to get it done.
So where does this leave UK fintechs?
I have no doubt that Open Banking and (eventually) Open Finance will have profound impact on the UK, revolutionising our credit market, bringing huge, excluded groups into mainstream finance and providing differentiated competition to the card rails, but in terms of the economics, the real prize is still on the table.
UK firms have built businesses that are designed to handle large quantities of API-driven transaction data. They’ve developed the security systems to protect the data, the skills to handle, clean and contextualise it and the case studies to prove how impactful that data can be. They are, in short, in a position of huge competitive advantage vs companies at the beginning of this journey in evolving markets. In order to maintain that advantage though, they have to keep working at the cutting edge of the technology, here the UK is falling down.
Australian firms are already working with Open Energy data, Brazilians are getting to grips with the wider financial product set through their country’s Open Finance programme.
We have to accelerate progress in the UK and the opportunity to do that is here.
On the public policy side, we need to establish a strong, independent body to preside over the future of the sector, we need to move on Open Finance, (the data bill is sitting in a drawer in parliament and should be moved forward as a priority) and we need to think about how we can build regulatory passporting into trade deals as we sign them.
On the market forces side we need more banks to take a leaf out of NatWest’s book and accelerate the development of premium APIs, we need to align on risk and liability frameworks for the use of these and work towards clarity for the market on commercial details. Finally we need better engagement between institutional lenders and retail lenders that use open banking data. Cost of capital is a major hurdle for Open Banking’s proliferation in the lending space and this both can and should be addressed.
This is a blockbuster agenda for 2023, but if we can get it done the prize for UK firms will be transformational. If we can’t, Open Banking will still have a major impact on our domestic economy but it might not be the firms hiring UK talent and paying UK tax that deliver it. This is not beyond us. There’s a lot to do but if we lace up our trainers, I’m very confident that we can make it happen.
A FinTech welcome to 2023!
January 2023 marks FinTech Scotland’s 5th birthday! Across that time we’ve seen fintech numbers grow, investment build, partnerships develop, international opportunities prosper and fintech adoption accelerate.
The occasion gives us an opportunity to reflect, consider the future and celebrate the fantastic progress of fintech firms in Scotland.
Over the years these fintech businesses have grown in number, collectively raised over £530m in investment and continue to build businesses with longevity and scale in mind, that deliver positive outcomes for people, businesses and society. It’s a resilient and inspiring group of innovators and leaders and I’m looking forward to the year ahead and the future opportunities to come.
The birthday celebrations were one reason to cheer, another was the news that Stephen Ingledew, our founding father and now our Executive Chair was honoured in the New Years honours list!
A further cause for celebration on two fronts.
Firstly, it’s a richly deserved mark of Stephen’s leadership and commitment, and secondly, it’s another indication of the value that’s placed on fintech innovation across the UK. We’ve always known the value that fintech will bring and it’s given us a further spring in our step as we welcome the possibilities for 2023.
We started those possibilities with an event connecting Space innovation and FinTech innovation. On a bright morning on the 11th of January, in a room full of space tech and fintech innovators, financial and professional service experts we gathered to discuss what we could achieve if we explored the connection between Finance and, Satellite data such as earth observational data or EO to those working in the Space sector.
The answer came when we joined the dots on sustainable finance, and ESG’. There are several pioneering companies, already innovating in this space.
Trade in Space, EarthBlox, Space Intelligence or Terrabotics are great examples of fintechs using earth observational data and technology. Their capabilities can help build confidence in green investing, will shape the future of infrastructure and real estate insurance, build clarity on the environmental impact of supply chains, and help businesses demonstrate regulatory compliance!
The day set the tone for more to come, watch this space!
Data Driven Innovation continues to inspire us, and while we might be at the beginning of our work with Space to drive Climate-FinTech possibilities, other data driven innovators are striving ahead.
January has seen an even stronger renewed focus on financial inclusion, with fintechs including Inicio.ai, Amiqus, DirectID, MoneyMatix, Soar and Inbest.ai continuing to grow and deliver change for citizens across Scotland and the UK.
More than ever, we’re confident that the purpose and intent from the Scotland’s fintech community will help drive the products and services needed to help address the challenges we continue to face.
The potential for 2023 continues, with partnerships and investment top priorities. Br-dge kicked off the year announcing its partnership with Visa and its growth plans for the year ahead! Gigged.ai kicked off investment news with a £1.6m raise to fuel next stage development.
And I’m looking forward to more! Welcome 2023, I’m looking forward to seeing business grow, fintechs scale, investment continue, and more collaboration develop.
On a personal note I’m looking forward to more daytime daylight and a stretch to the evening!
I’m also looking forward to seeing you in February! Please join us on Wednesday 15 February for our first in-person gathering of the year as we celebrate success and look forward to 2023.
”˜Consumer’ data has failed its creators
Consumer data’ is a remarkable quantity for the lack of ownership afforded to its eponymous creator ”“ the internet browser, the Google-er’, the consumer. Indeed, all of us are the creators of digital data from which Big Tech ”“ Google, Facebook, Amazon (you know the names) ”“ have achieved their giant status.
In fact, each time we open a website or app we leave behind a digital footprint used to track our movements across different websites and applications. This trail is inspected by Big Tech’s pack of algorithms, subsequently, determining’ a web user’s probable interests in products, ideas, and trends. With such an accurate’ determination of human interest at its disposal, Big Tech amasses a library of consumer data that it sells to advertisers, generating a lucrative revenue stream.
The relationship between consumers and advertisers goes back to Roman market squares and still serves just as important an economic function today. Yet, in today’s digital context, the creators of the industry’s most prized resource ”“ data ”“ have been excluded from sharing in its reward.
How has such an intrinsically unjust state of affairs survived for so long? Largely because consumers have been misled. In the first instance, consumers have been made to believe that their data holds no personal value. Secondly, that lack of control over data and, indeed, privacy is inseparable from the internet. While, this is slowly changing, with users now able to opt out of certain trackers, Big Tech is still aggressively trying to force us to adopt them: even if a user chooses to reject certain targeting preferences, they are often forced to confirm every time they enter the site or until impatience overcomes concerns.
Although they have certainly been egregious, we cannot place the entire blame on Big Tech, advertisers also have much to answer for. Advertisers spend approximately £27 billion a year on digital marketing, for the most part, this goes straight to Big Tech. This enormous expenditure is justified because it is, in actuality, an investment ”“ an investment made to entice consumers to spend. Moreover, in today’s digitally entangled economy in which jobs, networking, and day-to-day life are so dependent on internet access, the reach of advertising is inescapable. And so, we exist within a digital ecosystem that demands we share our thoughts and data with Earth’s largest corporations, only to boost our own likelihood to spend.
Undoubtedly, this status quo must change. Consumers must recognise the worth of their data and demand remuneration. Meanwhile, advertisers must stop encouraging and feeding Big Tech with the dirty cash that encourages such malpractice. The objective of advertisers must shift from only selling to selling and rewarding. In short, advertisers who seek access to consumer data must provide them with benefits.
Fortunately, the emergence of direct-to-consumer marketing apps and platforms has made such solutions a reality. For advertisers who market via such platforms, they unlock the ability to directly communicate with target consumers, in return offering the latter cash benefits and rewards. It is the responsibility of the platforms themselves to keep the end-user in mind, leveraging their position to ensure consumers get access to the highest value rewards. Furthermore, consumers are able to identify a preferred level of privacy, exchanging a level of data access on a quid quo pro basis to maximise cash benefits, all while driving a positive feedback loop of more relevant ad targeting.
By using direct-to-consumer marketing platforms, consumers can finally reclaim the right to their data and expect a fair price for its exchange. The current economic environment, undoubtedly, makes such solutions particularly enticing.
Though, far more importantly, direct-to-consumer platforms are resetting the relationship between data and advertising, shifting power away from Big Tech and back to consumers. Slowly, we march towards a future where digital data is not a price tag of the modern economy, but a precious commodity back in the hands of its creators, who financially benefit from its transparent and consensual exchange.
Mohsin Rashid is the CEO and co-founder of ZIPZERO, which offers a mass-market consumer solution to the cost-of-living crisis. Shopping via the ZIPZERO app earns users cash to pay bills ”“ the cash rewards are funded by retailers and brands, which gain access to a formidable direct-to-consumer marketing platform, allowing them to divert a collective £27 billion digital advertising spend back to their own customers. Through its compelling consumer proposition, ZIPZERO has become a prolific source of first-party, product-level consumer data. ZIPZERO is inviting major utility firms, leading retailers & brands (advertisers) to make active use of its progressive platform and help UK consumers tackle the cost-of-living crisis.
The Critical Role Partnerships Play When Scaling Fintechs
Blog written by Greg Watts, CEO at Findr
Alongside raising investment, securing the right partnerships is critical for business survival.
Indeed, in a recent research report from PwC, over 75% of CEOs rated partnerships as important’ or critical’ to their success.
Yet with many partnerships taking months if not years to come to fruition, it’s no wonder that so many businesses fail ”“ and waste considerable resources ”“ in the process.
So why do so many fintechs struggle with what we call the partnership problem?
Here are some reasons:
- They haven’t identified the right target partners;
- Their approach is too generic;
- They haven’t spent sufficient time identifying key stakeholders;
- Their offering and content doesn’t resonate with target partners;
- They don’t spend enough time or resources in the right places generating awareness.
In this article for Fintech Scotland, we’ll explore why businesses struggle with the Partnership Problem and provide tools and tips to enhance your approach and accelerate your efforts.
Get focused
In theory, partnership development is a straightforward process.
However, many businesses often fail at the first hurdle ”“ which is to have a razor-sharp focus on targets.
For example, it’s quite common to hear that a fintech wants to create partnerships with all’ retailers or banks in a particular market, then expect their sales teams to hit the phones and secure meetings.
However, with finite resources, that approach often misses the mark.
Fintechs ”“ and indeed, all businesses ”“ need clear partnership criteria.
The criteria for each business will vary, but some questions to consider may include:
- Which verticals, sectors or categories do you want to focus on? Within those, what are the priorities and why?
- What are the characteristics of your target partners? For example, are they high frequency retailers such as coffee chains or do they boast high transaction values, such as luxury brands?
- How easily can you partner with them? For example, a Tier 1 retailer such as BP or Asda is likely to take more time to partner with than a smaller coffee chain. Given how important time to market is ”“ it can often take months if not years to partner with large businesses ”“ targeting smaller partners initially to create case studies that demonstrate the value of your proposition may be a more efficient strategy.
Once you’ve evaluated your target partners, assign weightings to provide focus on where to spend your time and resources.
Sharpen your door opening approach by creating buyer personas
How often have you received a cold, un-researched introductory note on LinkedIn or via email?
It’s remarkable that so many businesses don’t tailor their approaches, then wonder why they don’t receive a response.
In fact, if you haven’t met someone before, you have less than a 3% chance of securing a meeting with them (unless you’re on Findr of course – where we average 27%)
It’s imperative you know as much as you can about your target partners before you approach them ”“ or any resources used to try and engage them will simply be wasted.
To maximise your chances of getting a meeting with a target partner, you need to make assumptions about what they may be looking for to help you tailor your approach.
To do this, it helps to develop buyer personas from which you can create content that makes them want to engage with you.
As you create the personas, points to consider are:
- What problems do you fix?
- What benefits do you offer? How do these compare to other players or competitors?
- Why should they engage with you?
- What channels do they engage with? How can you reach them?
- Which events or forums do they attend?
- Who ”“ if anyone ”“ do they currently partner with? And, critically, why would you be a better partner?
Cluster them to create segments with common challenges and issues you can solve.
Ultimately, you need to articulate why they should engage with you.
Once the personas have been created, you can focus on your content plan, encompassing your website, social media feeds, thought leadership and other marketing efforts.
Make it a team effort
Too frequently, partnership development and lead generation are viewed as the sales team’s responsibility.
Yes, the role of a salesperson is to sell ”“ however, he or she must have the full support of the business behind them to generate leads. Without that, the effort is likely to fail.
At Findr, we believe that the entire organisation should be involved in generating business and creating partnerships ”“ albeit in different ways ”“ and that any efforts not focused on growing the business should be questioned.
Thinking of it in these terms can help galvanise and focus your resources.
Bringing it all together
Creating partnerships sounds easy. However, without the right planning and focus, the results may be disappointing.
Being ruthlessly clear on who you’re targeting and why they should engage with you ”“ and then creating content that resonates ”“ is the most effective approach to creating long term, valuable partnerships.
Photo by Savvas Stavrinos: https://www.pexels.com/photo/monochrome-photography-of-people-shaking-hands-814544/
Tackling security and trust in digital payments
Fintech Tables are back for their second event. Sponsored by Pinsent Masons it focusses on payment, one of the 4 key themes highlighted in the FinTech Scotland Research & Innovation Roadmap.
Those events, organised by BDM Media, provide a platform for discussion to support developments and initiatives around the four key pillars of the Roadmap; financial regulation, payments & transactions, climate finance, and open finance data.
This second event focusses on payments and transactions and more specifically about how organisations can build security and trust in digital payments.
Payments has always been the leading area of innovation for fintech companies in Scotland utilising innovations such as open banking and embedded payments making it faster and more convenient to pay and transfer money both locally and globally.
As digital payments continue to grow in the UK and around the world, so do online fraud, digital crime and cyber attacks with over £1.2 billion through fraud and scams in 2019.
This event will welcome many guests including:
- Lloyds Banking Group
- Eeden Bull
- BR-DGE,
- Transfer Mate
- Occamsec
- Police Scotland
- Scottish Business Resilience Centre
- The Payment Systems Regulator.
The group will consider the exciting opportunities offered by digital payments alongside the strategies that financial services organisations need to deploy in order to build and maintain security and trust in these innovative solutions.
More details on the event and others in the series can be found at www.fintech-tables.com